


- Horizon Air pilots at Alaska Air Group held informational pickets after years of contract disputes over wages, staffing, training, and operational issues, and are moving toward a no confidence vote in senior operations leadership.
- The unresolved pilot negotiations highlight Alaska Air Group’s exposure to higher labor costs and potential disruption in its regional network at a time of planned international expansion and Hawaiian Airlines integration.
- This article examines how Alaska Air Group's investment narrative is influenced by Horizon labor unrest and the additional pressure on operating costs.
Alaska Air Group Investment Narrative Recap
To own Alaska Air Group, you need to believe the airline can grow profitably while absorbing higher labor, fuel, and integration costs. The near term story revolves around stabilizing operations as Hawaiian Airlines folds in and the Seattle international build out scales, without letting unit costs run away from revenue.
The immediate swing factor is execution around labor and the next earnings print. Wall Street expects quarterly EPS of $0.35, which would be a 66.7% drop year on year, even with forecast revenue of $4.31b. Horizon’s unrest adds pressure right where Alaska Air Group most needs predictable regional feed and cost discipline.
The most relevant data point here is the sharp reset in earnings expectations ahead of the October 20, 2026 report. Consensus EPS has been revised down very heavily over the past month, which indicates that analysts are factoring in more cost and operational friction just as Alaska Air Group leans into expansion and integration work.
For investors, the link is straightforward. Horizon labor uncertainty now sits alongside already rising unit costs, integration risk around Hawaiian, and a regional heavy network. Execution on international routes, premium products, and digital efficiency gains becomes the key counterweight, because any further wage or disruption shock would land on an already pressured earnings base.
Alaska Air Group's current loss of $175.0 million is set against analyst expectations for $1.4 billion in earnings on $18.7 billion in revenue by 2029, which implies revenue growth of 8.3% per year and an earnings swing of about $1.6 billion over that period.
Discover why Alaska Air Group's fair value suggests a 57% potential upside to its current price, which some investors believe could materialize sooner than expected.
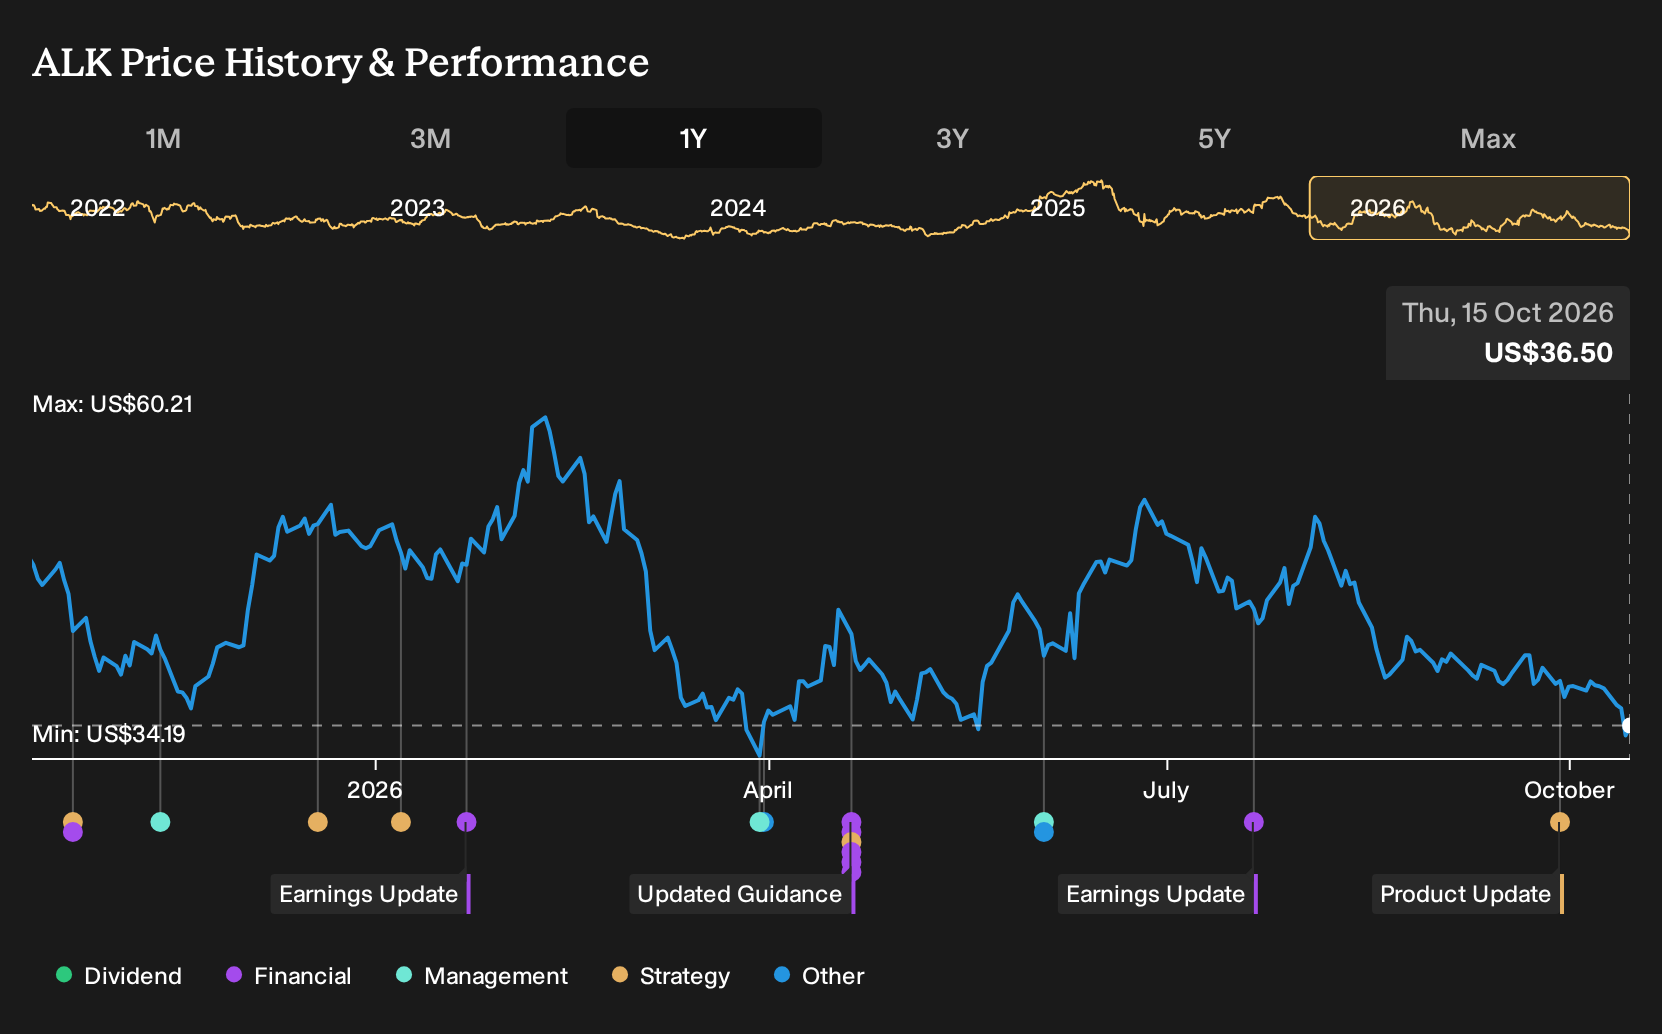
Exploring Other Perspectives
One alternate angle focuses less on Horizon and more on fuel costs. The most bearish analysts were already penciling in about US$18.1b of revenue and US$860.6m of earnings by 2029, well below the US$1.4b consensus. That is a much tougher story. With today’s Horizon news, those pre news forecasts may shift again, in either direction.
Explore 2 other Alaska Air Group fair value estimates, including one that suggests it could be worth just $55.25.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alaska Air Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alaska Air Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alaska Air Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alaska Air Group?
If Alaska Air Group has sharpened your focus on earnings risk, labor costs, and balance sheet resilience, it can help to cross check those themes against a wider set of companies using the Simply Wall St Screener.
- If you want potential value with quality fundamentals, review a curated 33 high quality undervalued stocks that align with strong cash generation and disciplined financial profiles.
- For investors who care most about resilience, scan a 32 resilient stocks with low risk scores that combine lower risk scores with more robust balance sheets and business models.
- When you are hunting for less crowded opportunities, sift through a 20 high quality undiscovered gems that pair solid fundamentals with relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com