


KB113 trial results put Krystal Biotech in focus
Krystal Biotech (KRYS) moved into the spotlight after early KB113 trial data in Gorlin syndrome showed regression in more than 80% of basal cell carcinoma lesions and prompted fresh FDA discussions.
Recent KB113 headlines have landed on a stock that has already seen a 33.65% year-to-date share price return and a 75.22% total shareholder return over the past year, with the KB113 data feeding into a story where short-term momentum has softened but longer-term gains remain very strong by three- and five-year total shareholder return measures.
Scan beyond Krystal Biotech and line up other potential biotech movers with strong fundamentals using our hand-picked list of solid balance sheet and fundamentals (25 results) as a starting point.
Krystal Biotech now carries a strong commercial franchise, a growing pipeline and a share price near US$330 after a powerful run. The real tension for investors sits in the math. Do the current fundamentals justify this valuation?
Most Popular Narrative: 16% Undervalued
Krystal Biotech’s most followed valuation storyline pegs fair value at $392.11 per share, above the recent $330 close. This puts the KB113 surge in the context of an already supportive long term earnings view.
Advancement of Krystal Biotech toward a multiproduct genetic medicines company through late stage programs such as KB803, KB801, KB407, KB111, KB707 and KB408, supported by HSV 1 platform technology designations, could broaden the revenue base beyond Vyjuvek and spread fixed costs across multiple products.
See why 33 investors see Krystal Biotech as 16% undervalued.
Result: Fair Value of $392.11 (UNDERVALUED)
Still, pricing pressure in Europe and heavier HSV 1 pipeline spending could drag on Vyjuvek margins and earnings if new product contributions arrive more slowly.
Find out about the key risks to this Krystal Biotech narrative.
Another View: Krystal Biotech Through The P/E Lens
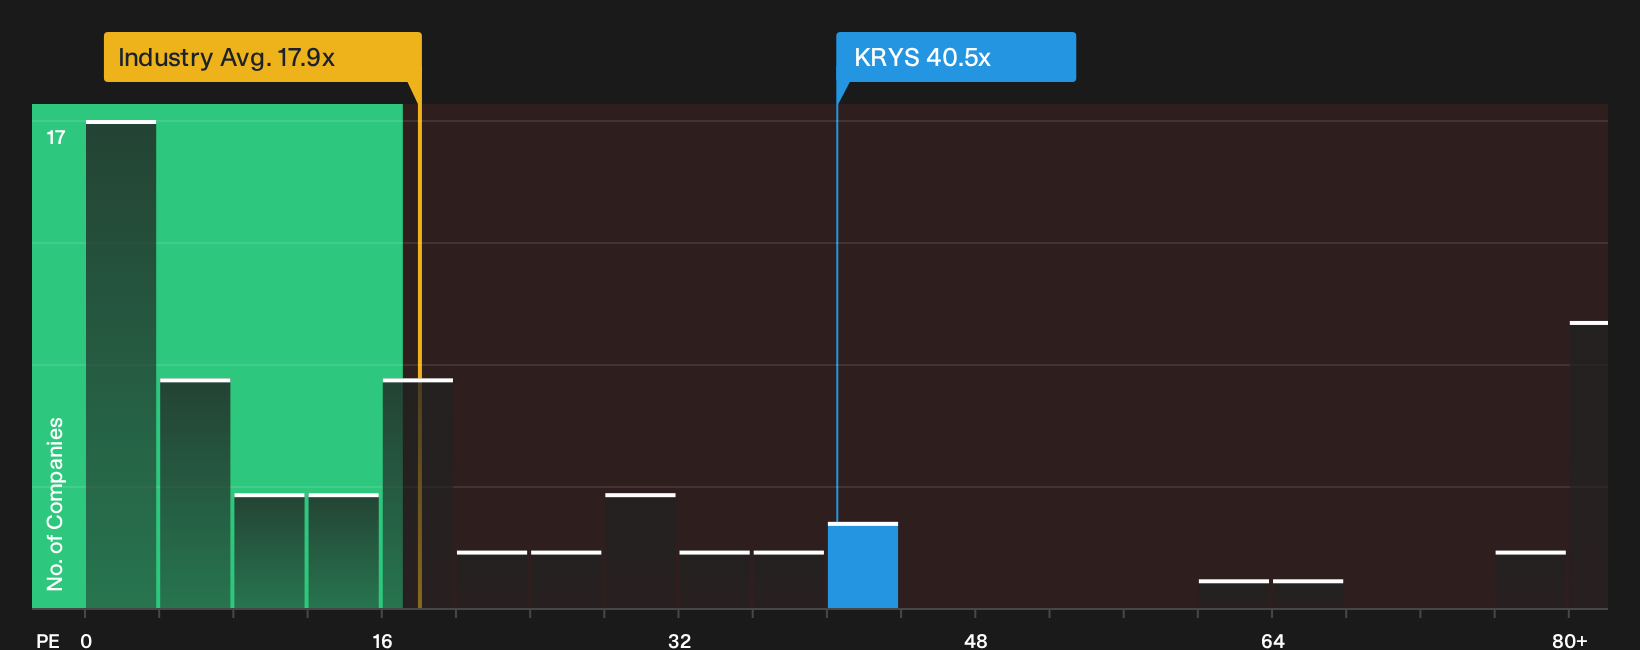
There is a very different story when you look at Krystal Biotech through its P/E ratio. The stock trades on about 40.5x earnings while the fair ratio is 34x, and the broader US Biotechs group sits near 17.6x. That difference may indicate higher valuation risk if expectations cool.
For a closer look at how this earnings multiple compares across peers and where the fair ratio might influence the valuation over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Krystal Biotech story so far. If you want a firm grip on the trade off between concern and optimism, start with the 3 key rewards and 1 important warning sign.
Looking for more Krystal Biotech sized ideas?
If Krystal Biotech has your attention, do not stop here. Broaden your watchlist with fresh ideas that balance quality, risk and income potential.
- Target resilient cash generators by focusing on companies with strong finances using the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount and compare Krystal Biotech with a curated pool of potential bargains through the 33 high quality undervalued stocks.
- Secure potential income streams while you research growth by scanning high yielding payers via the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com