


TKP entered this Q2 2027 earnings print with the label of a low P/E real estate stock and a complicated story after a large one off gain in the past year. The fresh quarter delivered Basic EPS of ¥33.85 on revenue of ¥34,794m, solid on paper but far less dramatic than the trailing figures built on that prior ¥10.4b boost.
Yet the share price closed today at ¥1,960, leaving recent buyers reacting more to the bargain headline than to the quality and sustainability of those profits.
Like the low P/E on TKP but uneasy about profits flattered by that one off ¥10.4b gain, and looking for companies where earnings power is less distorted by special items? Scan our list of solid balance sheet and fundamentals stocks (21 results) to find a cleaner set of businesses whose fundamentals better reflect their reported results.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥34,794m vs. ¥25,433m (change of about 37% year on year)
- Net Income Excl. Extra Items (Q2 2027 vs. Q2 2026): ¥1,262m vs. ¥544m (change of about 132% year on year)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥33.85 vs. ¥14.31 (change of about 137% year on year)
- Trailing 12M Net Profit Margin (to Q2 2027 vs. prior year): 9.8% vs. 3.4% (higher profitability over the last 12 months)
Ask Charlie what TKP’s one-off gain really means.
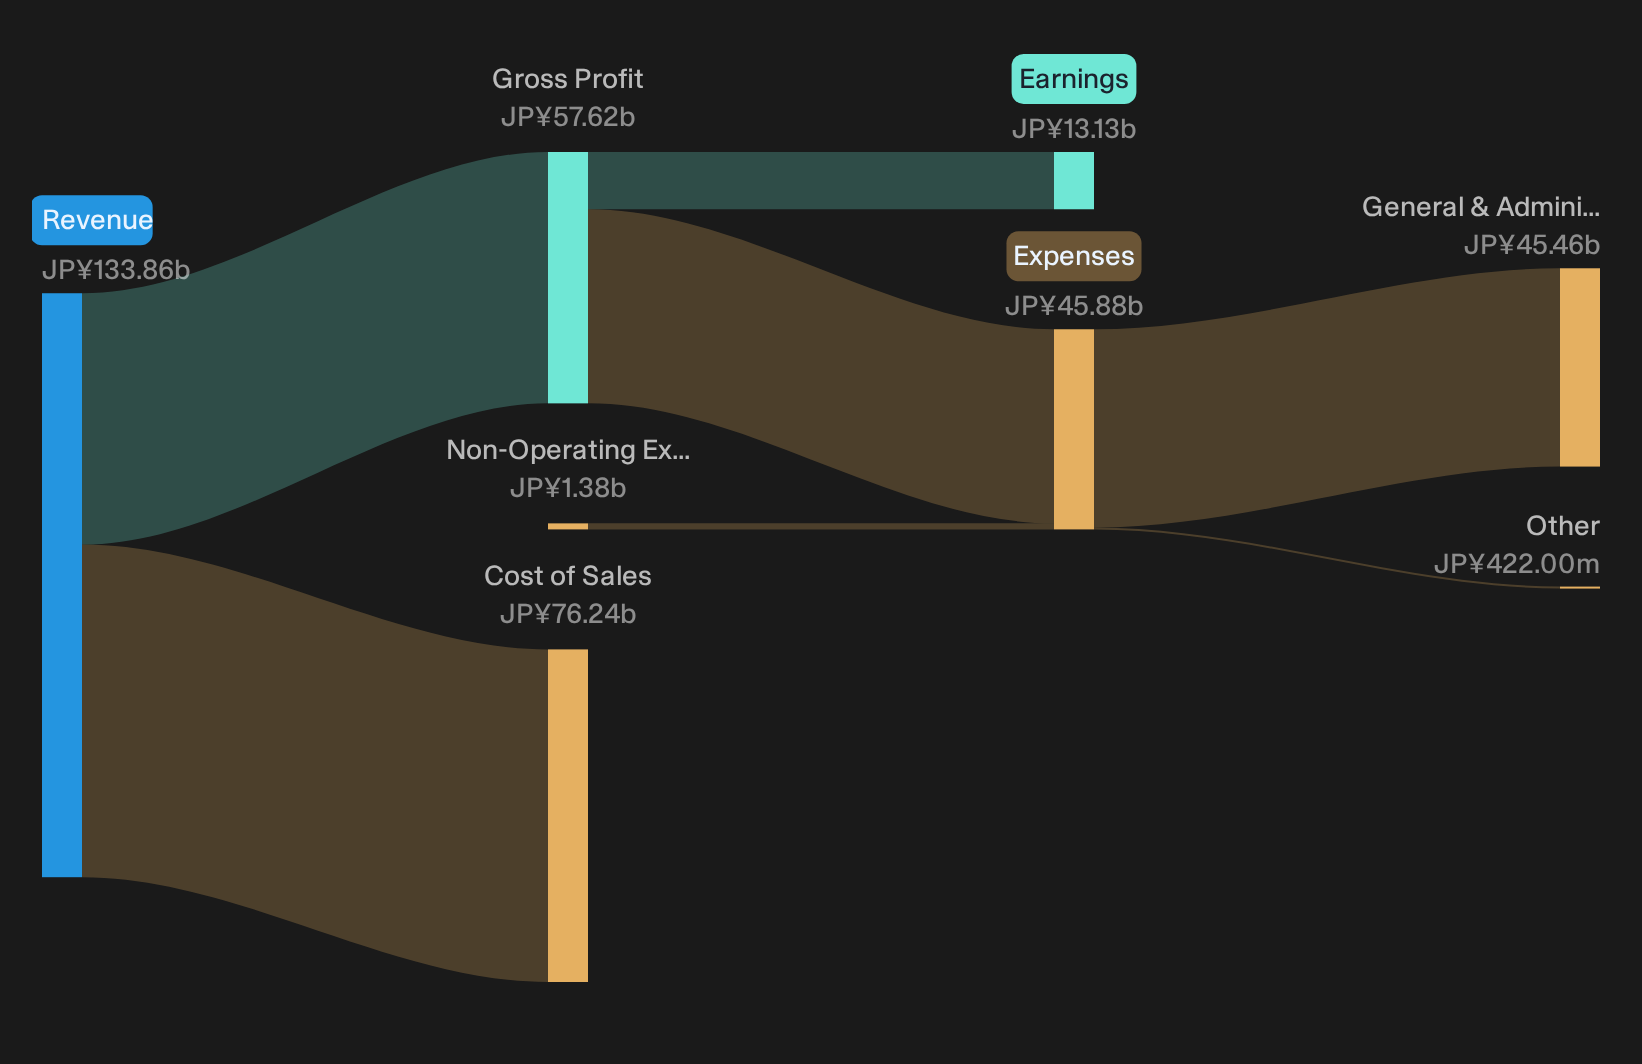
TKP growth story meets early efficiency test
TKP’s bullish story hinges on acquisitions and facility growth turning into a cleaner, stronger earnings engine rather than just a bigger one.
"The company plans to leverage the consolidation of acquired businesses like Lilycolor and Novarese to boost operational efficiencies and expand service offerings, which should help increase revenue and enhance net margins."
Revenue of ¥34,794m and net income excluding extra items of ¥1,262m show that scale and earnings both moved in the same direction. The trailing 12 month net margin at 9.8% versus 3.4% a year earlier lines up with the efficiency goal, although the large prior one off gain means investors still need more clean quarters to call this a fully proven trend.
Testing TKP risk narrative around cash and capex
There is a darker version of the story that says aggressive expansion and weak subsidiaries quietly erode future flexibility.
"Despite proactive investments, TKP's cash has decreased significantly due to increased fixed assets, impacting liquidity and potentially restricting future capital investments necessary for growth."
The latest quarter shows higher earnings and a stronger trailing margin, so profitability is not yet signaling liquidity stress. The share repurchase program of up to ¥3,500m running through August 2026 adds another demand on cash, which makes the risk of tighter investment capacity credible. With acquisitions like Lilycolor still flagged as underperforming, the combination of capex, buybacks and mixed subsidiary contribution remains an unresolved pressure point.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Hunt For Quiet Mismatches
TKP just reminded investors that earnings quality and share price sentiment do not always move together. The real opportunity could be finding stocks that could be undervalued before the market corrects them.
- Company 1 - 18% below our estimate - targets firms that need form design and data platforms once scattered reporting tools create operational strain. The real opportunity could be finding stocks that could be undervalued before the market corrects them.
- Company 2 - 19% below our estimate - expands fee-based projects where storage assets and apartment hotels monetize underused urban land. The real opportunity could be finding stocks that could be undervalued before the market corrects them.
- Company 3 - 24% below our estimate - supplies optical and electronic materials that device makers adopt when redesigning displays and sensors. The real opportunity could be finding stocks that could be undervalued before the market corrects them.
Three companies from the same screener. Open the full list of 14 companies trading below our fair value estimates →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com