


Albemarle has been through a rough stretch on the market, and the latest moves now raise a simple question for investors who care about valuation. Given the slide in the share price, attention naturally turns to whether the current market value lines up with what the business generates in sales.
- Over the past 5 years the stock has fallen 55.4%, which puts the spotlight firmly on whether the current market value can still be squared with the revenue it brings in.
- A recent analyst upgrade that flagged a "remarkable recovery" story hints that expectations for Albemarle's core operations and future sales trajectory may be shifting, which can reshape how much investors are prepared to pay for each dollar of revenue.
- The analysts covering Albemarle have run their own numbers. See what analysts think Albemarle's shares could be worth.
The issue now is whether Albemarle's latest share price around US$98 sits on solid footing when you judge it against its sales.
To see how Albemarle's sales-based valuation argument compares with other opportunities on the market, evaluate it alongside a curated list of 33 high quality undervalued stocks.
Has Albemarle Run Too Far on Sales?
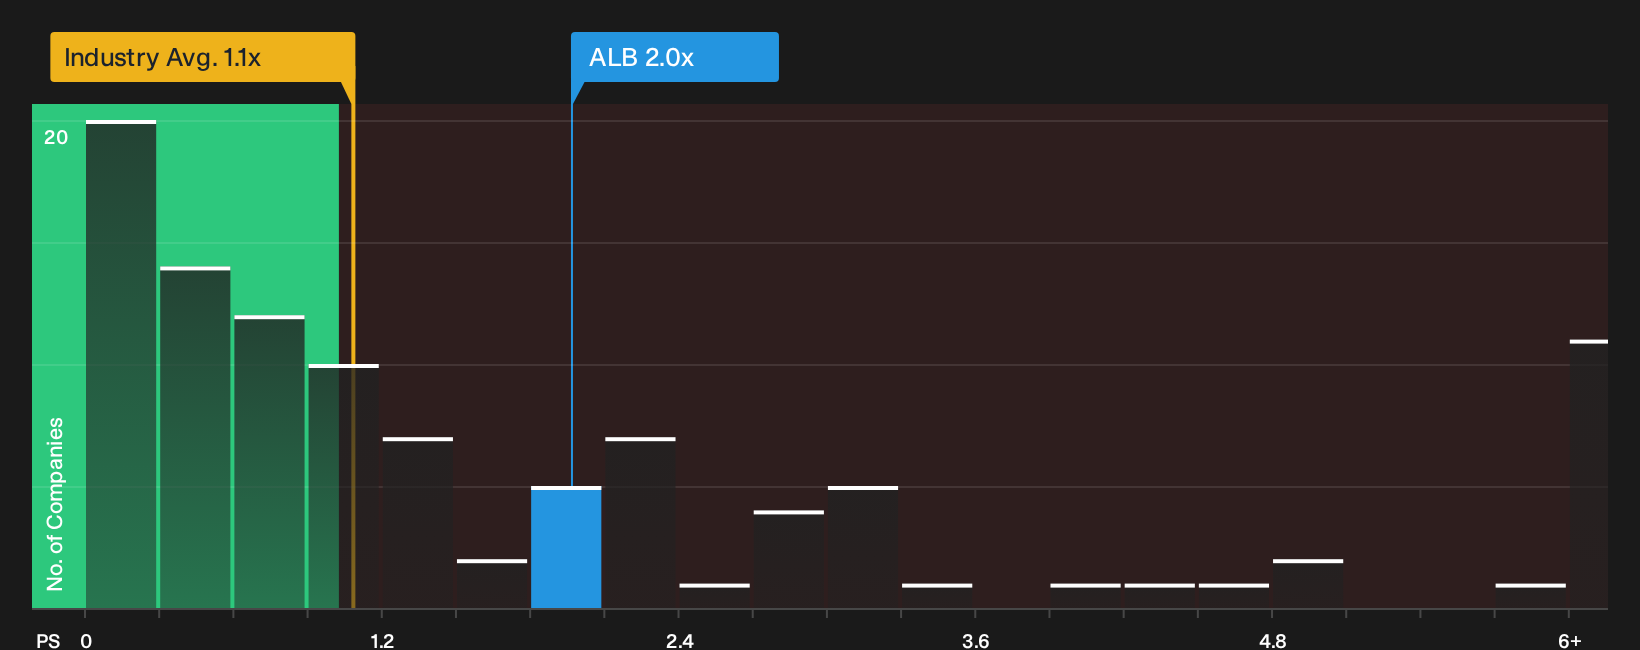
P/S fits Albemarle because the company is often judged on sales potential rather than current earnings, which can be more volatile. At around 2.0x P/S, the stock trades below the peer group on roughly 2.4x, but above the wider Chemicals industry at about 1.1x. That mix suggests investors are paying a premium to the broader sector for Albemarle's revenue stream, while still not matching the pricing of closer competitors.
The Fair Ratio model, which adjusts the P/S benchmark for Albemarle's specific profile, points to a lower multiple than the current 2.0x. That gap means the shares screen as overvalued on this framework, even after the recent Mizuho upgrade that framed the story as a recovery. For anyone weighing the stock today, the question is whether Albemarle's future revenue quality and risk justify paying more than the tailored benchmark implies. Explore the numbers behind Albemarle's P/S valuation.
The Albemarle Narrative: What Would Justify Today's Price?
Narratives for Albemarle pick up where the P/S debate leaves off, spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth significantly more or less than today. Where a single valuation ratio or model gives one neat figure, these scenarios unpack the future that figure quietly relies on so you can monitor how Albemarle's actual progress compares with it over time on Simply Wall St's Community page.
Community views on Albemarle split between those who see more upside in the story and those who think expectations already look full.
Bull case: 42% undervalued
"With ~50% of sales volumes locked under long-term agreements with major Western OEM and battery customers, Albemarle benefits from enhanced revenue stability and reduced cyclicality..."
Discover why this Narrative puts Albemarle at 42% undervalued.
Bear case: roughly fairly valued
"Ongoing global lithium supply expansions, combined with visible overcapacity in Chinese conversion facilities and periods of market surplus, point to intensifying commoditization, eroded pricing power, and heightened cyclicality..."
Explore why this Narrative puts Albemarle at roughly fairly valued.
Before acting on Albemarle's valuation, there is one more angle to check
Price tags rarely tell the whole story, and for Albemarle the research checks have highlighted specific areas of concern that deserve a closer look before you commit fresh capital. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com