


China Taiping Insurance Holdings has delivered a very strong 3 year share price return, yet the recent pullback puts a fresh spotlight on whether that move is fully supported by its earnings power. With the stock now trading at HK$17.46, the question is how much of the story is already reflected in the multiple investors are paying for profits today.
- Over the past 3 years the share price has gained about 161.0%, which puts real pressure on the current earnings to justify that kind of compounding.
- AM Best’s affirmation of an A Financial Strength Rating for Taiping Reinsurance, a core subsidiary, can support investor confidence in the group’s balance sheet and its ability to keep writing business that feeds future earnings.
- There is a second opinion on China Taiping Insurance Holdings worth weighing. See what analysts think China Taiping Insurance Holdings's shares could be worth.
For investors, the debate is whether China Taiping Insurance Holdings' recent share price, after both a strong multi year run and shorter term weakness, is appropriately aligned with what its earnings currently support.
If you want a yardstick for China Taiping Insurance Holdings' recent run against other value ideas, compare it with companies in the 194 high quality undervalued stocks.
Does China Taiping Insurance Holdings Look Undervalued on Earnings?
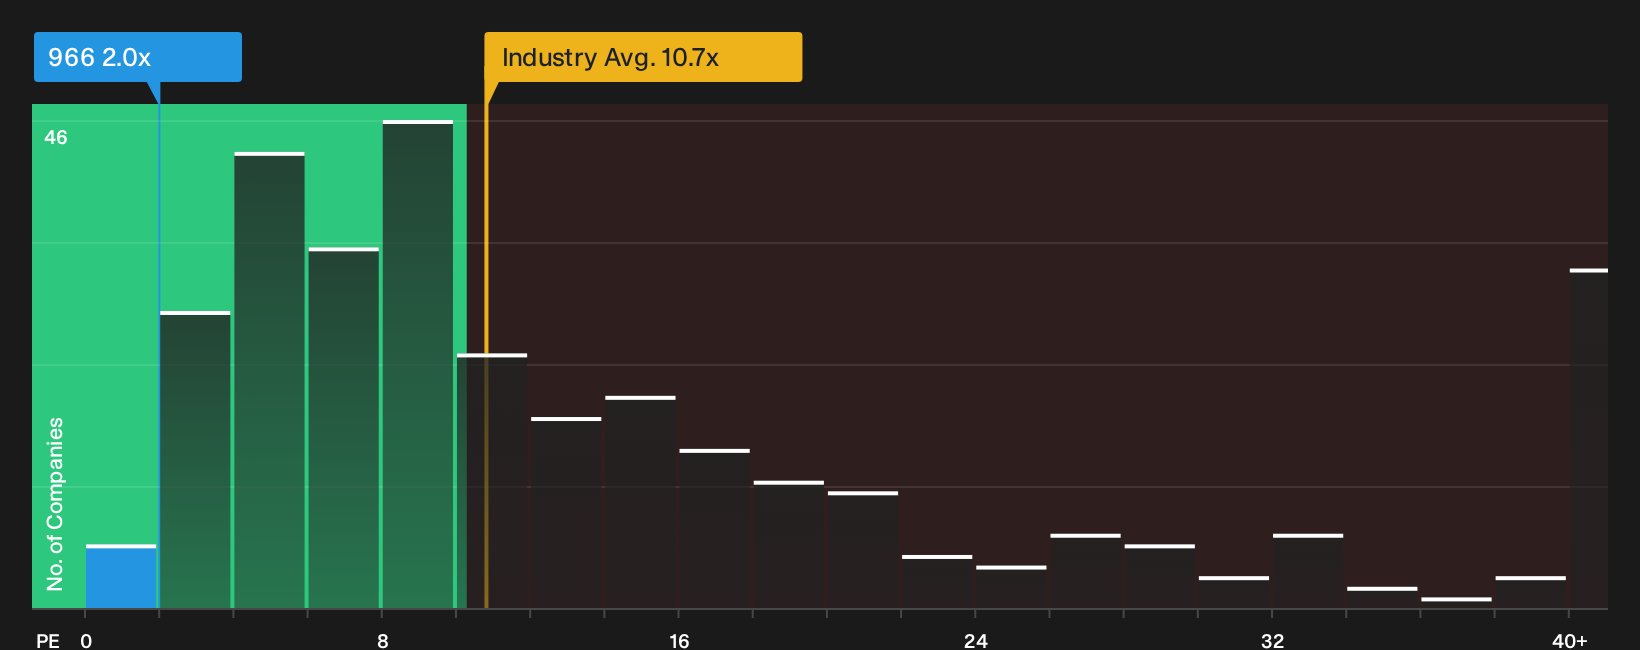
The P/E ratio fits China Taiping Insurance Holdings well because earnings are a central yardstick for insurers. On this measure, the stock trades on a P/E of about 2.0x, versus an insurance industry average of roughly 11.3x and a peer group closer to 11.1x. That is a wide gap for a business that does have reported profits to anchor the calculation.
Because the AM Best affirmation highlights solid capital strength at a key reinsurance subsidiary, the low earnings multiple looks more like a valuation question than a pure balance sheet concern. The Fair Ratio model, which adjusts for the company’s own growth profile, margins, scale and risk, points to a higher P/E than where the shares change hands today, so the current pricing screens as undervalued on this framework. For anyone weighing whether the recent pullback has already reset expectations, the size of the discount relative to that tailored benchmark is what really needs a closer look. Explore the numbers behind China Taiping Insurance Holdings's P/E valuation.
The China Taiping Insurance Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for China Taiping Insurance Holdings pick up where this valuation question leaves off and explain what growth, margins and earnings path would need to occur for the shares to be worth materially more or less than today’s price, using the Community page as the hub. Each scenario links a fair value to a clear set of potential catalysts and risks so you can track which story about China Taiping Insurance Holdings' future is gaining traction over time.
A clear, number driven narrative on China Taiping Insurance Holdings gives you a way to spell out what assumptions around earnings, capital strength and valuation you are actually making and to keep those views consistent over time. With AM Best affirming strong credit ratings at Taiping Reinsurance, a written framework also helps you track whether that support from the subsidiary and the group’s balance sheet ends up justifying today’s pricing or pointing to a different risk reward profile.
Share your own Narrative for China Taiping Insurance Holdings and set out the assumptions behind your valuation.
One last piece to check for China Taiping Insurance Holdings
Before treating the current pricing story as complete, it helps to look at who is steering China Taiping Insurance Holdings and how their pay packets line up with your interests. See who runs China Taiping Insurance Holdings and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com