


Pre-market market trends
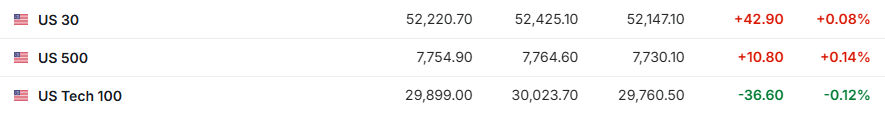
1. Before the US stock market on October 16 (Friday), futures for the three major US stock indexes had mixed ups and downs. As of press release, Dow futures were up 0.08%, S&P 500 futures were up 0.14%, and NASDAQ futures were down 0.12%.
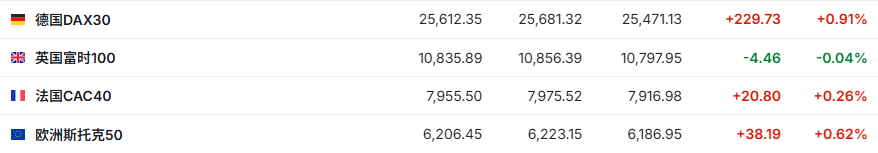
2. As of press release, the German DAX index rose 0.91%, the UK FTSE 100 index fell 0.04%, the French CAC40 index rose 0.26%, and the European Stoxx 50 index rose 0.62%.
3. As of press release, WTI crude oil fell 0.04% to $97.93 per barrel. Brent crude rose 0.39% to $106.33 per barrel.

Market news
Walsh is actively setting the long-term outlook for AI, and the market maintained unchanged expectations for October. Federal Reserve Chairman Kevin Walsh did not dismiss the market's expectations that the Fed's month-end meeting would keep interest rates unchanged. Walsh reiterated on Friday that the Federal Reserve will stabilize prices and described the September rate hike as removing “some easing.” Regarding the October monetary policy meeting, he made it clear that he would not predict the Fed's monetary asset path, nor would he announce the actions that may be taken during the remaining meetings of the year in advance. He emphasized that every decision made by the Federal Reserve will form a policy judgment based on output, employment, and inflation, rather than a pre-determined policy path, and reiterated his personal preference for the Fed not providing any forward-looking guidance. At the same time, in his speech, Walsh viewed AI as the most profound economic transformation of his life. At the same time, he emphasized that the impact of AI on the demand side will come before supply-side improvements. Walsh's speech strengthened the judgment that cutting-edge AI technology will change the economy over a long period of time, yet he did not give a promise to suspend interest rate hikes in October. As for global semiconductor sector stocks, which have recently experienced sharp sell-off and have fallen into a pullback trajectory, the positive point is that he has not further strengthened expectations for recent interest rate hikes, but whether US bond yields can continue to cool down, AI computing power-themed stocks that have been hit hard recently, and whether the broader semiconductor and technology-related sectors can launch a counterattack still depends on whether inflation, corporate financing conditions, and AI profit can be realized at the same time.
Wall Street is waiting hard for Bezent to take another step: the aftermath of the August “treasury bond reversal” is unresolved, and the November refinancing announcement may become the next flashpoint. As the Treasury prepares to update its debt management plan in November, key clues could surface on Friday. Traders are closely monitoring the quarterly financing questionnaire issued by the US Treasury Department to Tier 1 traders on Friday to try to determine whether Bezent is preparing to reduce the supply of long-term US Treasury bonds or further expand repurchases in the new round of financing plans announced in November. The reason why the market is highly sensitive is related to an unexpected action by the Ministry of Finance in August. At that time, Bezent suddenly expanded the repurchase scale of old securities, increasing the repurchase amount for 10-30 year US bonds in addition to normal quarterly financing arrangements. This move has been called a “reversal operation by the Ministry of Finance” by the market, and is widely interpreted as an attempt to ease the pressure brought about by rising long-term yields.
“Don't work against AI!” HSBC: The bond market storm cannot stop the stock market from rising, and the main AI line is still constructive. The latest opinion from the HSBC Global Investment Research Team put it bluntly that investors should not “trade against AI.” The bank believes that the AI sector has strong profit momentum, the monetization path is more clear, and the valuation is no longer expensive after adjustment, so the overall risk-to-benefit ratio is still attractive. According to HSBC strategists, AI is still one of the most difficult trends in the current market to counter. The monetization signal continues to be positive. At the same time, demand for AI inference is growing at an accelerated pace, driving the cloud revenue of major hyperscale cloud vendors to strengthen, and GPU rental prices have remained strong. This means that the AI industry chain is shifting from a “capital expenditure story” to a “revenue cashing story,” and the market's concerns about the return on computing power investment have abated. The recent sell-off in the bond market has boosted yields, which usually puts pressure on highly valued growth stocks. However, stock market performance shows that AI's main profit support is hedging the impact of rising interest rates. HSBC believes that as long as AI monetization continues to be verified, corporate IT spending is skewed towards AI, and demand for cloud and computing power remains strong, there is still further potential for AI-driven stock market growth.
Does the “hidden bear market” of US stocks hide big opportunities? Goldman Sachs predicts that “three-way buying” is poised to return. A recent report released by The Kobeissi Letter, a well-known financial research institution on Wall Street, shows that the US stock market benchmark index is still high, but the valuation has “gone through the winter.” According to the agency, energy inflation, US bond yields, and interest rate hikes are depressing valuations that the market is willing to pay; if these pressures ease and profits continue to be realized, technology stocks led by the “Big Seven” may usher in strong valuation repairs. The Goldman Sachs capital flow team provided another bullish clue: the reopening of corporate repurchase windows, inflows of retail capital at the end of the year, and foreign purchases after the election may bring incremental demand for stocks whose valuations have been reduced. The two point in common is that high-quality technology-based growth assets that can continue to be strongly realized with profits are expected to be promoted by capital return and valuation repair at the same time.
Is a “giant bull market” brewing within the S&P 500 index? Hedge fund bosses are betting on “the remaining 493 stocks.” AI concept stocks have continued to be under pressure recently, but hedge fund boss Thomas Hayes believes that investors may have overlooked another change that is taking place in the US stock market: at a time when the S&P 500 index is still dominated by a few large technology stocks, the broader stock market within the index is preparing for a round of strong market. Hayes, founder and managing member of Great Hill Capital, predicts that in the next six months, the “remaining 493 stocks” (unspectacular 493) of the S&P 500 constituent stocks other than a few large technology companies may become the main driving force for the rise in the market. Hayes' judgment is based on changes in AI investment logic: in the past, investors were keen to buy companies that provided chips and computing power for AI infrastructure construction; however, as competition intensified and supply increased, the high profit margins of these companies might be difficult to sustain. In contrast, companies that can use AI to improve productivity and expand profit margins may be the next investment direction worth paying more attention to.
Individual stock news
Memory chip stocks generally fell before the market. Before the US stock market on Friday, as of press release, SK Hynix (SKHY.US) fell nearly 3%, Micron Technology (MU.US) and SanDisk (SNDK.US) fell more than 2%, and Western Digital (WDC.US) and Seagate (STX.US) fell more than 1%.
After nearly ten years of ticket skipping, Tesla (TSLA.US)'s next-generation Roadster was finally unveiled: it broke 100 in 0.81 seconds, can fly, and will only be mass-produced in 2028. After nearly a decade of delays, Tesla's second-generation Roadster has finally been unveiled. The second-generation Roadster supercar was unveiled at the press conference. The supercar is equipped with an air-conditioning propulsion system co-developed with SpaceX (SPCX.US) and codenamed “A71.” In the display, the vehicle can hit an almost vertical wall and achieve absorption, land in the air like a rocket, and complete tumbling and jumping movements. From a financial perspective, according to analysts, Roadster's direct contribution to Tesla's overall sales volume is expected to be limited. The car is positioned as high-end and low in production, and will compete with high-performance models from brands such as Porsche, Lamborghini, and Ferrari, but the high profit margin may make it a considerable source of profit. As of press release, Tesla's US stocks rose more than 3% in the premarket on Friday, while SpaceX rose more than 1%.
After 40 years of cooperation with Pepsi (PEP.US), KFC in the US will switch to Coca Cola (KO.US)! US KFC announced a new partnership with Coca Cola. Beginning in January 2027, KFC will transfer its US beverage partnership to Coca Cola, and Coca Cola products are expected to be available at all KFC restaurants across the US by spring 2027. Since Pepsi bought KFC in 1986, US stores have been supplying Pepsi-owned beverages. KFC US President Kathryn Tan-Gillespie said that Pepsi remains an important partner for KFC's parent company and its international markets. PepsiCo, on the other hand, said that its cooperation agreements with Taco Bell and KFC for international business have recently been renewed.
IBKR.US (IBKR.US)'s third-quarter revenue increased 16% year over year, and announced a quarterly dividend increase of more than 70%. Driven by increases in net interest income and commission revenue, Yingtou Securities' net revenue for the third quarter was US$1,914 million, up 15.6% from US$1,655 billion in the same period last year; adjusted net revenue after excluding special projects was US$1,872 billion, up 16.3% from US$1,610 million in the same period last year. Judging from the revenue structure, net interest income is still the most important source of revenue for Yingtou Securities. In the third quarter, the company's net interest income was US$1.154 billion, up 19% from US$967 million in the same period last year, mainly driven by an increase in the average balance of clients' securities loans and customer lender balances. In terms of commission business, Yingtou Securities' commission revenue for the third quarter was US$602 million, up 12% from US$537 million in the same period last year. The company said this was mainly due to an 18% year-on-year increase in the number of customer daily revenue transactions (DARTs) and an increase in regulatory expenses passed on to customers.
Alcoa (AA.US)'s third-quarter revenue was US$3.7 billion, up nearly 24% year over year. Alcoa's third-quarter revenue was US$3.704 billion, up 23.7% year on year, but decreased 6.6% from the previous quarter; net profit attributable to the company was US$483 million, up from US$407 million in the previous quarter; earnings per share were US$1.81, up from US$1.53 in the previous quarter. Excluding special projects, Alcoa's adjusted net profit for the third quarter was $485 million, lower than the previous quarter's $562 million; adjusted earnings per share were $1.82, down from $2.12 in the previous quarter. Adjusted EBITDA was US$789 million, down 12.4% from the previous quarter.
Key economic data and event forecasts
At 21:15 Beijing time, the monthly rate of US industrial output in September