


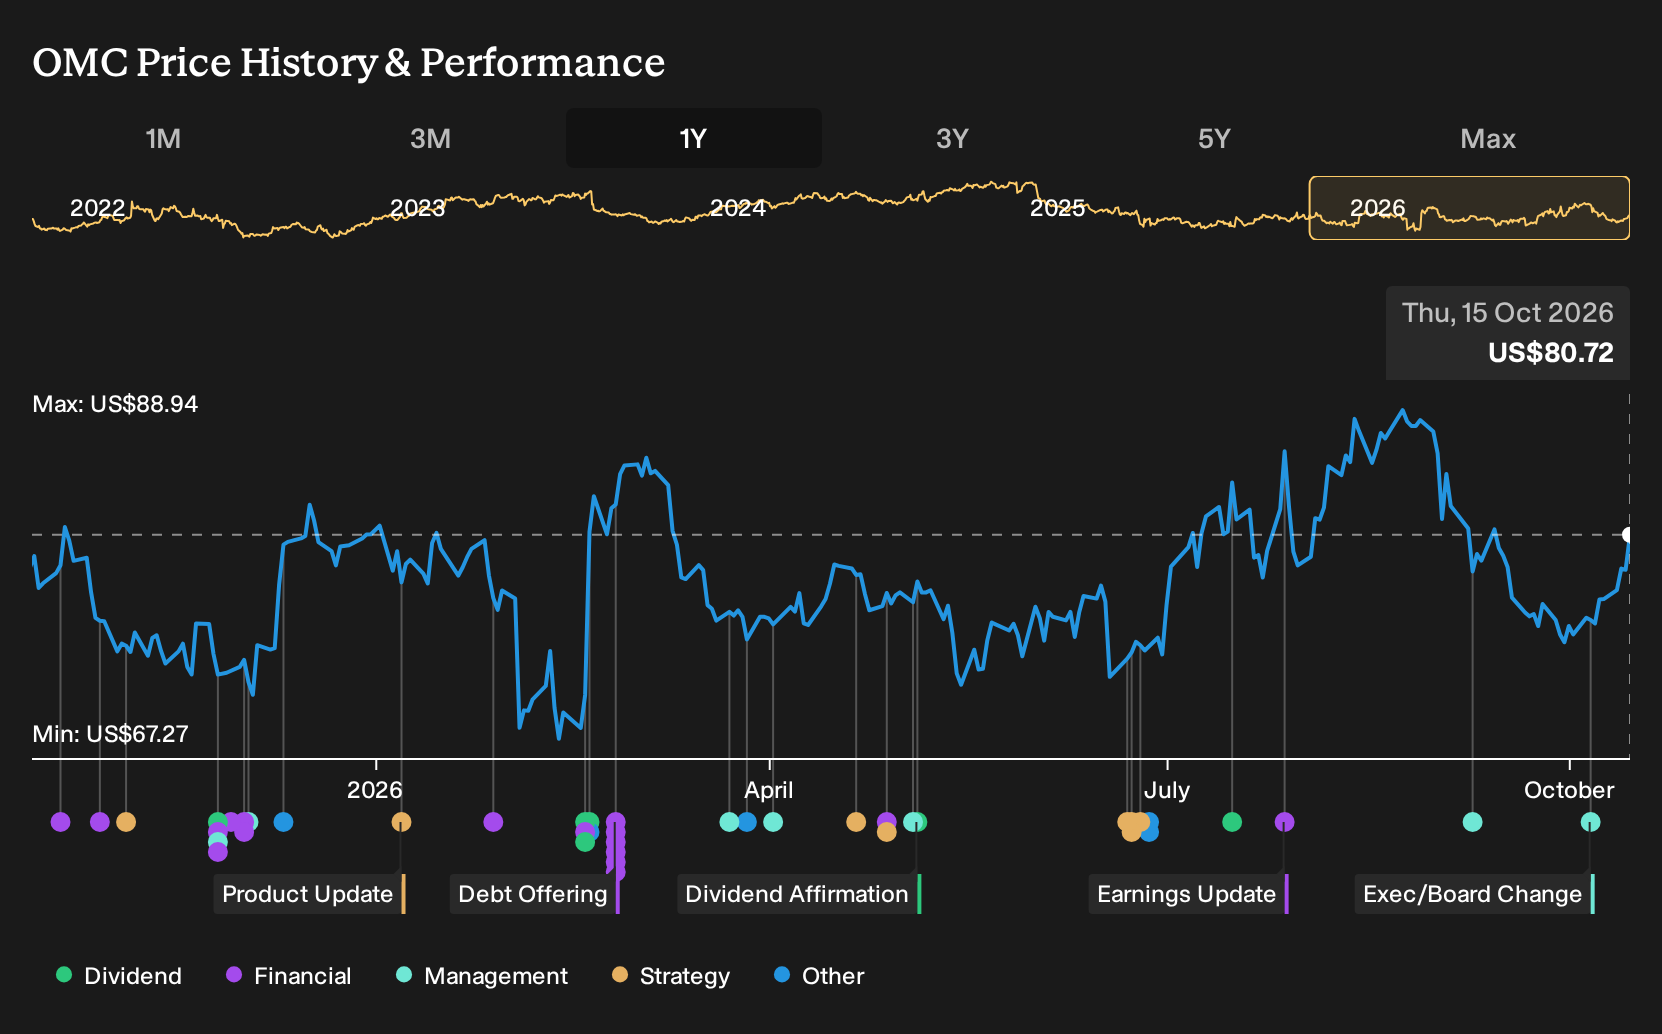
- Omnicom Group reported that long time Senior Vice President and Chief Accounting Officer Andrew Castellaneta retired on 1 October 2026, with Jordan Farnam, previously Vice President of Global Financial Reporting, stepping into the Chief Accounting Officer position to oversee the company’s financial reporting.
- The handover to Farnam, who brings corporate controller and technical accounting experience across media and data focused businesses, comes at a time when Omnicom Group is running a broad cost reduction and portfolio pruning effort aimed at supporting Core Operations margins and EBITA.
- We will now assess how Omnicom Group’s investment narrative could shift as investors weigh the new Chief Accounting Officer appointment.
Scan how investors are pricing leadership and reporting shifts like Omnicom Group’s by reviewing our hand picked 33 high quality undervalued stocks, which some see as trading below fair value estimates.
Omnicom Group Investment Narrative Recap
For an investor to stay with Omnicom Group, the core belief is that the shift toward data and AI centric marketing, along with the integration of Interpublic assets, can offset pressure in legacy advertising and uneven regional trends. The expanded cost reduction and portfolio pruning program is the near term swing factor. Execution here matters more than this Chief Accounting Officer change for short term EBITA and cash flow expectations.
The biggest operational risk remains pressure on traditional advertising, plus higher interest costs and macro exposure in regions like Asia Pacific and the Middle East and Africa. The leadership handover to Jordan Farnam looks more like a governance and reporting continuity event than a change that alters those core business risks.
The appointment of Jordan Farnam as Chief Accounting Officer ties directly into a story that already leans heavily on complex integration work, outcome based contracts and sizeable disposals. Clean, consistent financial reporting becomes especially important when Omnicom Group is targeting about US$3.5b to US$3.6b of revenue disposals and US$1.5b of gross cost synergies by mid 2028.
Investors watching the cost program as a key catalyst will likely pay attention to how Farnam presents margin trends, one off items and debt service costs, given high leverage and rising net interest expense. Clear disclosure around Core Operations margins, advertising softness and AI related investments can either reinforce confidence in the DCF based undervaluation case or highlight execution risk more quickly.
Omnicom Group's analyst narrative points to revenues of US$26.0b and earnings of US$2.6b by 2029. This build assumes revenue growth of 5.2% per year and an earnings increase of about US$2.2b from US$390.2m today.
Uncover why Omnicom Group's fair value indicates a 26% potential upside to its current price before that discount closes.
Exploring Other Perspectives
One alternative take on Omnicom Group focuses on revenue risk from outcome based contracts rather than upside from AI tools. The most cautious analysts were pencilling in about US$25.8b of revenue and US$2.7b of earnings by 2029 before this finance leadership change. You can treat this handover as a prompt to compare those forecasts with other views and decide which story you find more convincing.
Explore 3 other Omnicom Group fair value estimates, including one that suggests it could be worth just $77.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Omnicom Group research is our analysis highlighting 2 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Omnicom Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omnicom Group's overall financial health at a glance.
Looking For More Ideas Beyond Omnicom Group?
If you want to stress test your view on Omnicom Group, it often helps to line it up against a few very different opportunities. Use the Simply Wall St Screener to see how other businesses stack up on value, balance sheet strength and income potential, then decide where Omnicom Group really fits in your portfolio.
- For investors hunting for what they see as quality at a discount, compare Omnicom Group with a wider pool of companies that some regard as trading below fair value by reviewing our 33 high quality undervalued stocks.
- If capital preservation sits higher on your priority list than aggressive upside, weigh Omnicom Group against a 32 resilient stocks with low risk scores that many see as better aligned with lower volatility and sturdier risk profiles.
- When you want to balance Omnicom Group with under the radar opportunities that still show solid fundamentals, scan through a curated 20 high quality undiscovered gems that might broaden your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com