


PTC (PTC) just secured a renewal from the United States Air Force for its Servigistics service supply chain software, extending a relationship focused on aircraft readiness and more data driven parts planning.
PTC’s share price has shifted only slightly in the last week, with a 7 day share price return of 0.30% and a 1 day move that was also marginal. However, the 30 day share price return of 45.50% and 90 day gain of 55.30% point to strong recent momentum following the Schneider Electric acquisition agreement and related calls. Over a longer horizon the picture is more mixed, with a 1 year total shareholder return that declined 4.38% compared with a 3 year total shareholder return of 36.68% and a 5 year total shareholder return of 50.91%. This suggests that recent short term excitement has arrived on top of more measured long term outcomes.
Spot opportunities around PTC’s momentum by scanning a curated group of resilient software and infrastructure peers through the 32 resilient stocks with low risk scores.Bulls see PTC’s recent surge and Schneider Electric offer as proof the stock still sits below intrinsic value. Bears argue the premium already reflects that. The valuation work next shows which case the current numbers lean toward.
Most Popular Narrative: 6% Overvalued
PTC closed at $193.15, while the most followed narrative pegs fair value around $183.08. The story now leans slightly toward deal driven pricing rather than open ended upside.
The current valuation implies that the market is not fully pricing in this bullish narrative that PTC is undervalued given its raised ARR and revenue guidance, increased repurchase plans and the role of its product data platforms as a foundation for industrial AI.
See why 21 investors see PTC as 6% overvalued.
Result: Fair Value of $183.08 (OVERVALUED)
Still, elevated churn in ServiceMax and the risk that investors assign a lower future P/E to PTC could easily undermine this slightly overvalued narrative.
Find out about the key risks to this PTC narrative.
Another View: PTC Through The Earnings Lens
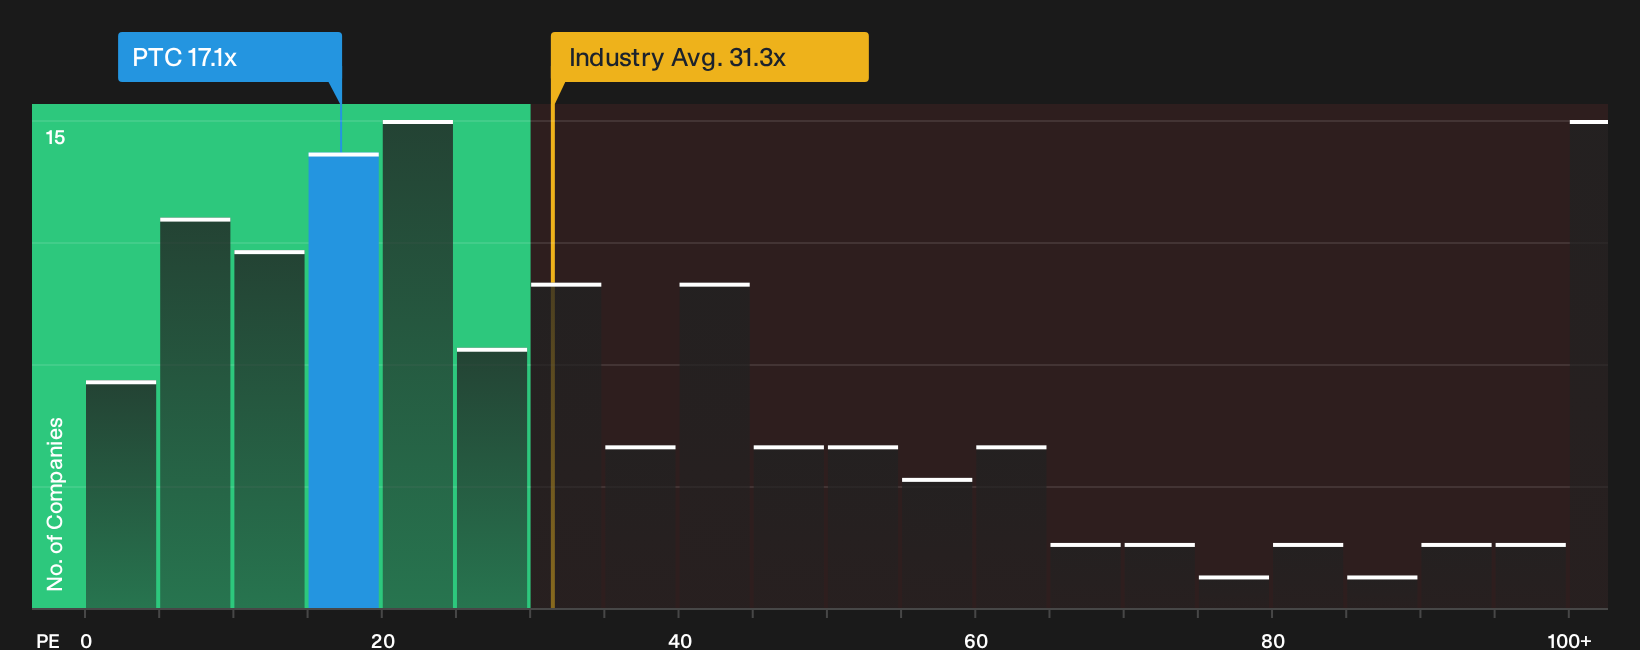
The earlier fair value of $183.08 came from analyst projections and price targets. A simple earnings multiple tells a different story. PTC trades on a P/E of 17.1x, while peers average 31.3x and the fair ratio sits at 22.2x. That gap points to a meaningful valuation mismatch. Is the market overpricing deal risk or underestimating the underlying business?
To see how the current pricing stacks up against these earnings comparisons in more detail, take a closer look at the valuation breakdown with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around PTC can either be a warning or an opening, so move fast, review the full picture, and decide where you stand by weighing its 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond PTC?
If PTC has sharpened your focus on quality, do not stop here. Use the Simply Wall Street Screener to surface fresh ideas that match your game plan today.
- Target stocks that combine quality and reasonable pricing by scanning a curated pool of 33 high quality undervalued stocks before the crowd chases the same stories.
- Strengthen your income engine by reviewing a focused set of 8 dividend fortresses that aim to deliver meaningful yield with disciplined fundamentals.
- Prioritise financial resilience by filtering for companies on the list of solid balance sheet and fundamentals (25 results) so you are not caught off guard by weak balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com