


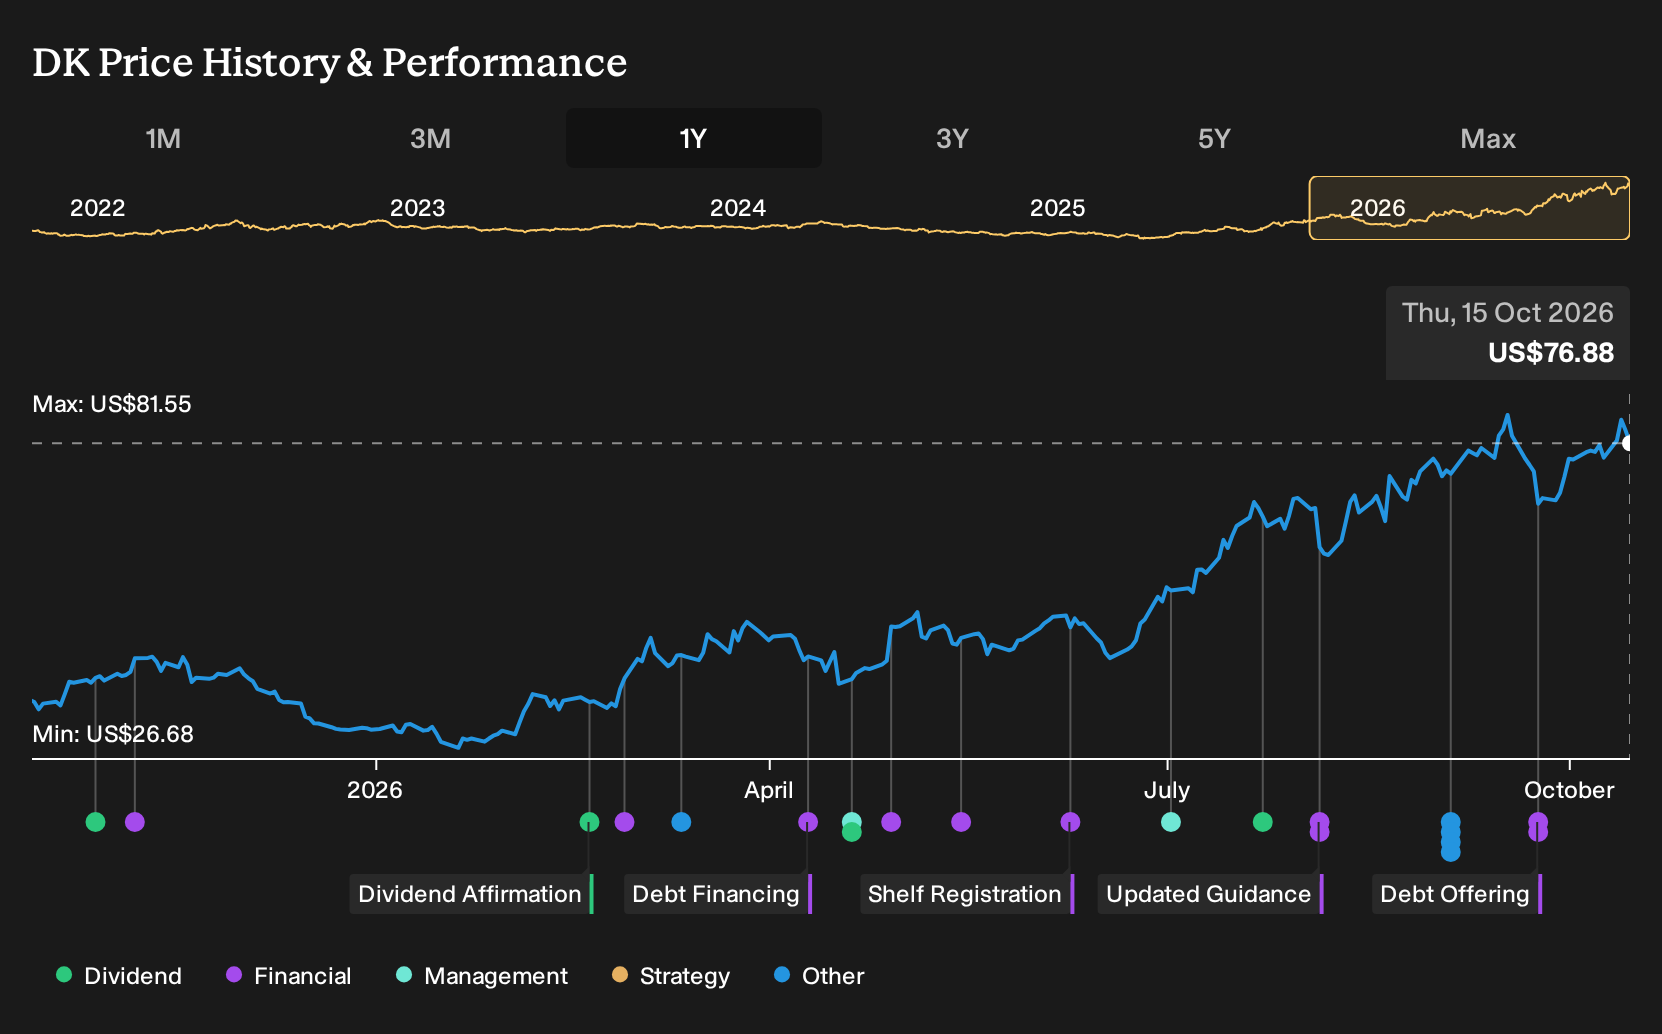
- Delek US Holdings reported stronger second quarter results, supported by refining margins, operational execution, and progress on its Enterprise Optimization Plan, alongside improved refinery reliability and contribution from its Logistics segment.
- The planned government backed expansion of Delek US Holdings' Tyler refinery under the Defense Production Act highlights how federal support could influence its long term fuel production role for both commercial and military customers.
- The potential impact of the government backed Tyler refinery expansion plan on Delek US Holdings' broader investment narrative remains to be seen.
Scan other energy producers aiming to convert operational projects into durable cash flow using our curated list of list of solid balance sheet and fundamentals (25 results) to compare them alongside Delek US Holdings.
Delek US Holdings Investment Narrative Recap
To own Delek US Holdings, you need to believe this is primarily a story about running complex refineries and pipelines more efficiently, not reinventing the business. The Defense Production Act backed Tyler expansion and the recent margin supported quarter both point to an operating focus on utilization, reliability, and cash generation from a concentrated Gulf Coast and Mid Continent footprint.
The near term catalyst is execution on the Enterprise Optimization Plan, while keeping refineries running smoothly after the Big Spring turnaround. The biggest risk is that heavy exposure to U.S. fuels, ongoing net losses in prior quarters, and meaningful debt servicing needs keep free cash flow tight even as capital spending stays high.
The Defense Production Act announcement around the Tyler refinery is the clearest recent development for this story. A government backed project tied to commercial and military grade fuels directly links Delek US Holdings to U.S. energy security and could influence how consistently the Tyler site runs once any expansion work is completed.
For you as a shareholder, that connects to two key levers. First, higher potential throughput and product mix could interact with the Enterprise Optimization Plan and the Logistics segment to support margins, if executed well. Second, the same project could magnify existing risks around regulatory exposure, capital intensity, and concentration in traditional fuels at a time when analysts already expect earnings and revenue to decline over the next few years.
Delek US Holdings' analyst narrative projects US$11.2b revenue and US$154.7m earnings by 2029, based on a forecast yearly revenue decline of 2.5%. This implies earnings would decrease by about US$71.3m from US$226.0m today.
Uncover why Delek US Holdings' fair value indicates that Delek US Holdings is roughly in line with its current price.
Exploring Other Perspectives
One alternate view treats the Defense Production Act news as a test of whether Delek US Holdings can support a much higher P/E over time. The most optimistic analysts were already working off around US$12.7b of 2029 revenue and US$117.9m of earnings. Those estimates came before this expansion plan, so you may see forecasts and opinions shift quite a bit from here.
Explore 3 other Delek US Holdings fair value estimates, including one that suggests potential upside of up to 17% from the current price.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Delek US Holdings research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Delek US Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Delek US Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Delek US Holdings?
Once you have a view on Delek US Holdings, it can help to set it alongside other potential opportunities so you can judge risk, balance sheets, and income potential on the same footing.
- For investors who care most about financial resilience and low leverage, compare Delek US Holdings with companies from a curated list of solid balance sheet and fundamentals (25 results) that score well on strength and fundamentals.
- If the goal is to hunt for mispriced quality, line Delek US Holdings up against a broader universe of 33 high quality undervalued stocks that pair sound fundamentals with potentially attractive entry points.
- Income focused readers who want to weigh Delek US Holdings against high yield alternatives can scan a hand picked set of 8 dividend fortresses built around robust payouts and balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com