


- Thomson Reuters recently launched the next generation of CoCounsel Legal globally, adding a Multinational Profile that brings cross border legal and regulatory content from more than 100 countries into a single AI supported workflow for legal teams.
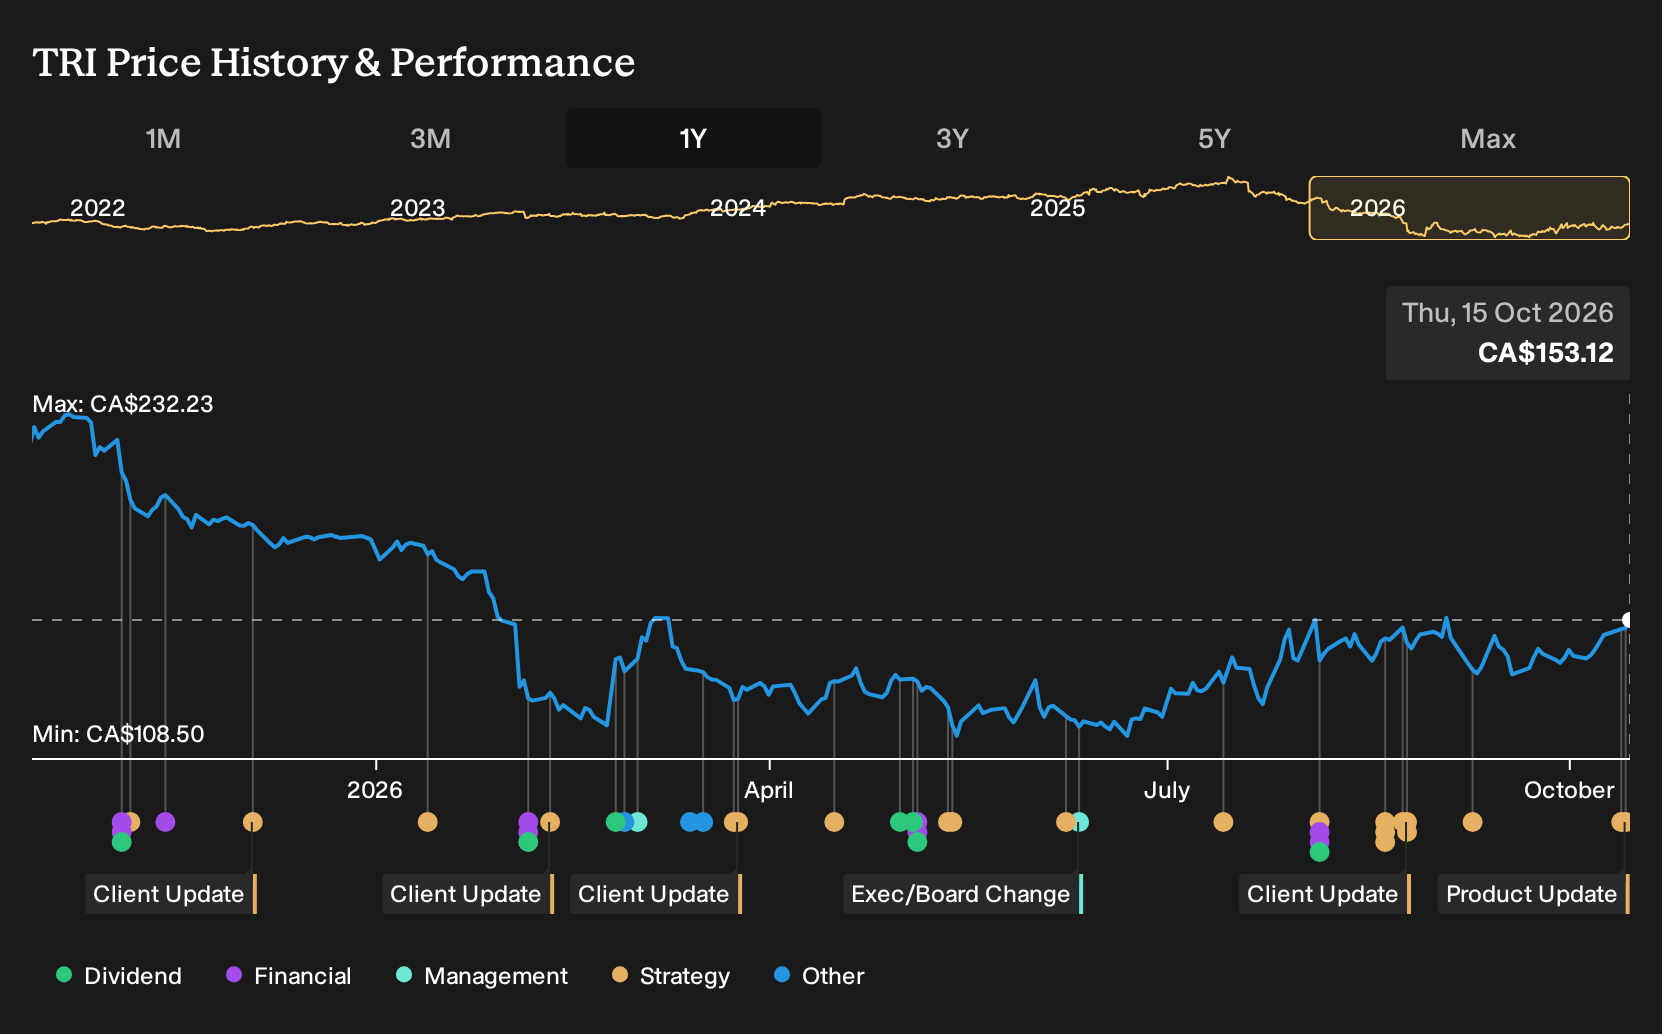
- The move pushes more of Thomson Reuters' proprietary Westlaw and Practical Law content into integrated, agentic AI tools that sit directly in day to day legal workflows. This can influence how clients budget for research, software, and cross border advisory work.
- We will now look at how Thomson Reuters' investment narrative could be affected by CoCounsel Legal's expanded cross border AI workflow coverage.
Thomson Reuters Investment Narrative Recap
To own Thomson Reuters, you need to believe its mix of proprietary content and AI workflow tools can keep customers locked in and paying for premium subscriptions, even as competition in legal tech intensifies. The key near term swing factor is how quickly legal and tax clients actually adopt products like CoCounsel Legal and Westlaw Deep Research at scale.
The global CoCounsel upgrade, with cross border coverage in more than 100 countries, supports that thesis but does not remove the main risks. Heavy AI spend, integration complexity and potential pricing pressure from open source tools still matter. Execution on product rollouts through 2026 remains the real test.
The Smokeball partnership update ties directly to the CoCounsel and Westlaw agentic AI push. Integrating Westlaw Deep Research into Archie AI puts Thomson Reuters content and reasoning engine directly inside a practice management system where small and midsize firms already work. This is the workflow positioning that the broader narrative depends on.
For you as an investor, the interest is in whether these embedded deployments translate into durable subscription usage rather than one off curiosity. The deal also highlights platform dependency risk. As more third party tools plug into Thomson Reuters, any technical issues, slower feature delivery or weaker security posture could quickly affect adoption and the perceived edge of its proprietary content.
Thomson Reuters' current analyst script points to $10.0b in revenue and $2.4b in earnings by 2029, built on assumed yearly top line expansion of 8.3%. That path implies earnings today of $1.7b would need to climb by about $0.7b to meet consensus by the 2029 forecast year.
Uncover how Thomson Reuters' fair value indicates a 16% potential upside to its current price, which could narrow quickly as expectations adjust.
Exploring Other Perspectives
Some of the most optimistic analysts frame Thomson Reuters as an AI rollout story where faster adoption is the real catalyst. They were already penciling in revenue of about $9.9b and earnings of $2.4b by 2029, with a higher 29.8x P/E, before this global CoCounsel step. You can treat those upbeat views as one end of the spectrum and explore how this news might shift them.
Explore 6 other Thomson Reuters fair value estimates, including one that suggests as much as 81% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your instincts.
- A great starting point for your Thomson Reuters research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Thomson Reuters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Thomson Reuters' overall financial health at a glance.
Looking For More Investment Ideas Beyond Thomson Reuters?
If the Thomson Reuters story has sharpened your thinking, use that momentum to scan for other stocks that fit the kind of profile you want in your portfolio. The Simply Wall St Screener helps you move from a single idea to a short list of candidates that match your risk tolerance, income needs, or focus on balance sheet strength.
- If you prefer defence over drama and want businesses that aim to limit downside risk, start with a 8 resilient stocks with low risk scores that already filters for resilience.
- If you are interested in companies that may offer a margin of safety based on fundamentals, use the 6 high quality undervalued stocks to see where quality and pricing might intersect.
- If you are looking for sturdier finances behind the story so you are not relying only on headlines, run a list of solid balance sheet and fundamentals (8 results) to see which tickers clear that bar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com