


Production setback and buyback plan catch investor attention
First Majestic Silver (TSX:AG) has drawn fresh scrutiny after third quarter 2026 results showed lower silver and gold production linked to a 12 day labour dispute at the San Dimas mine.
Management paired that operational update with news of a new normal course issuer bid. The program allows the miner to repurchase up to 10,000,000 shares, which is about 2% of its outstanding equity through October 2027.
First Majestic Silver now trades at CA$22.79, with the 1 day share price return of 5.02% partially offsetting a 1 month share price decline of 12.21% and a softer 7 day move. The 1 year total shareholder return of 6.06% sits against a very large 3 year total shareholder return near 20 times that level.
Compare First Majestic Silver’s setback and buyback with other producers by running through our hand picked 10 top silver producer stocks poised for their own turning points.
After a production hit, a sharp 1 day rebound, and a fresh buyback, First Majestic Silver now poses a simple question for investors: Does the current price still skew the risk and reward toward buyers?
Most Popular Narrative: 34% Undervalued
On the most followed view of First Majestic Silver, the fair value sits at CA$34.75, well above the CA$22.79 last close. This puts fresh context around the recent production setback and buyback announcement.
Substantial ongoing investment in exploration (e.g., 255,000 meters drilled, addition of drilling rigs, and development of large new ore bodies like Navidad and Santo Niño) is expected to extend reserve life, increase production capacity, and drive long-term revenue and cash flow growth.
See why 46 investors see First Majestic Silver as 34% undervalued.
Result: Fair Value of CA$34.75 (UNDERVALUED)
Still, the bullish First Majestic Silver story can fray if high operating and capital spending squeeze margins, or if Mexico-focused assets face prolonged labor or regulatory setbacks.
Find out about the key risks to this First Majestic Silver narrative.
Another View On First Majestic Silver’s Price Tag
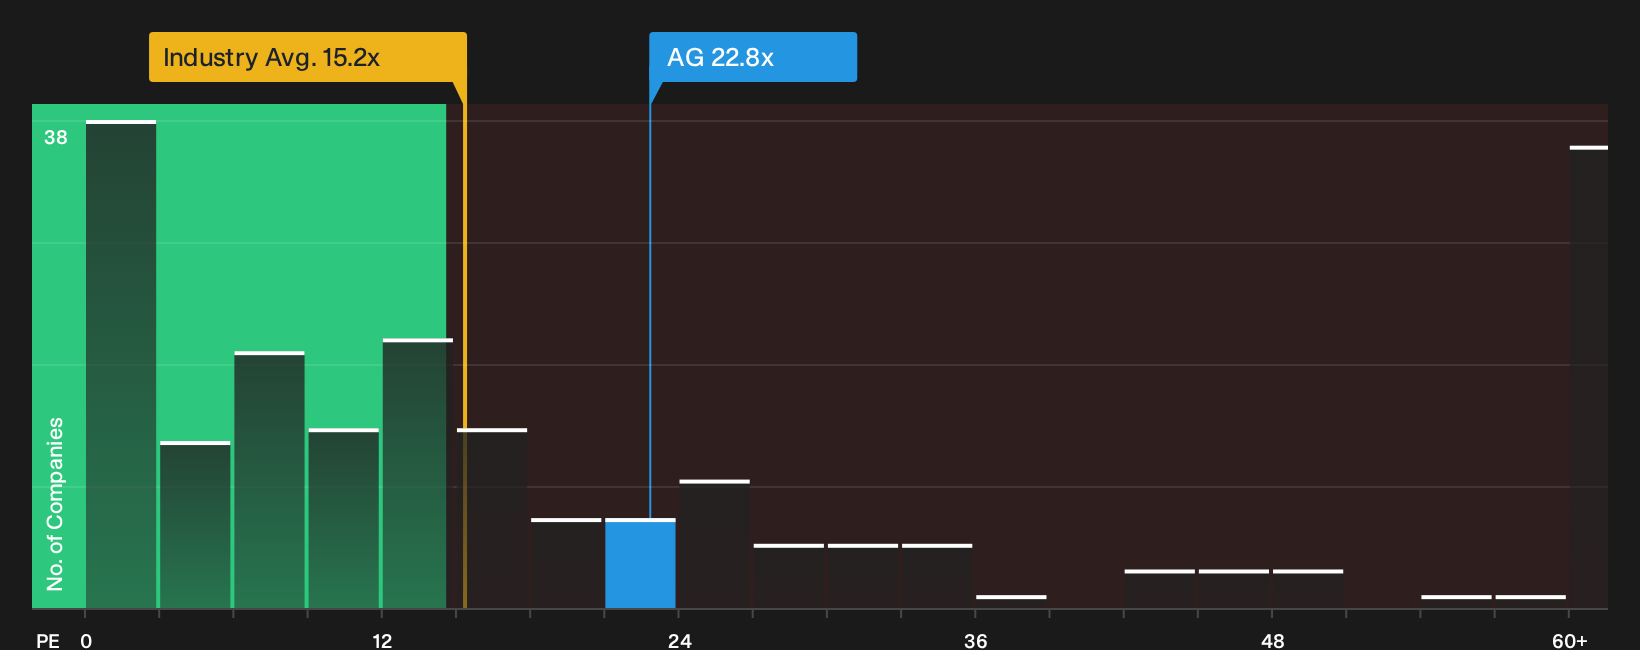
That popular CA$34.75 fair value comes from analyst forecasts. A different lens tells a cooler story. First Majestic Silver trades on a P/E of 22.8x, which is higher than the Canadian Metals and Mining industry at 15.2x and above its own 19.2x fair ratio, even though it sits below a 41.2x peer average. Does that premium to the sector, but discount to close peers, signal extra risk in the multiple or room for the share price to move toward that fair ratio over time?
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on First Majestic Silver so far. If you want to move quickly and reach your own view, start by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond First Majestic Silver?
If First Majestic Silver has your attention, do not stop here. Broaden your watchlist now so you are not chasing the next opportunity after it moves.
- Target dependable cash generators by scanning a 3 dividend fortresses that focuses on income potential backed by substantial yields and resilient payout histories.
- Hunt for quality at a discount with a 6 high quality undervalued stocks that highlights companies combining strong fundamentals with prices that sit below estimated fair value.
- Protect your downside first and build around a 8 resilient stocks with low risk scores that emphasizes resilient balance sheets and lower risk profiles across sectors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com