


Wallenstam (OM:WALL B) has released its third quarter and nine-month 2026 results, reporting increases in both sales and net income compared with the same period a year earlier. This earnings update is now drawing investor attention.
Wallenstam’s recent report lands after a choppy year for the shares. The latest SEK36.22 price comes after a 1-day share price return of 2.78% and a 7-day gain of 4.20%, while the 90-day share price return is down 13.02% and the 1-year total shareholder return has fallen 19.72%. Short-term momentum has picked up even as longer term performance remains under pressure.
Scan how Wallenstam compares with other Swedish real estate plays by checking out list of solid balance sheet and fundamentals (203 results) that may be better positioned for the next swing in sentiment.
Bulls point to Wallenstam’s recent earnings jump and short term rebound. Bears focus on the weaker multi year share record. Which side does the current valuation actually support next?
Most Popular Narrative: 7% Overvalued
Wallenstam’s most followed valuation storyline puts fair value at SEK34, slightly below the recent SEK36.22 close, so the market is leaning a bit rich against that framework.
The company's heavy geographic concentration in Stockholm and Gothenburg leaves it exposed to the risk that urbanization patterns continue to shift due to remote work trends, which could result in declining demand and lower occupancy rates for its core commercial and residential portfolios, negatively impacting rental income and overall cash flow.
See why 0 investors see Wallenstam as 7% overvalued.
The fair value estimate in that narrative is SEK34, built using a 9.76% discount rate and analyst assumptions that earnings could be materially lower by 2029 than the SEK2.7b level reported today. It treats Wallenstam as a slower growth, lower margin landlord that might still need to support a higher P/E multiple in future to justify today’s price.
The same storyline also factors in pressure on profit margins, with margins assumed to move from 80.8% to 22.9% over the next few years as financing costs, regulation and property upgrade spending weigh on profitability. That view is partially offset by arguments around high occupancy, a sizeable construction pipeline and a balance sheet that uses hedging and moderate leverage to cushion shocks.
For an investor reading this, the key question is whether those cautious inputs feel too harsh or too generous relative to Wallenstam’s mix of earnings volatility, one off gains and modest forecast revenue growth of 4.87% a year. Your own stance on interest coverage, capital needs and long term rent trends in Stockholm, Gothenburg and Uppsala will likely decide whether SEK36.22 looks demanding or acceptable against a SEK34 narrative fair value.
Result: Fair Value of SEK34 (OVERVALUED)
Still, sustained high occupancy in Wallenstam’s residential portfolio, along with a growing pipeline of new apartments, could challenge the idea that the shares look stretched here.
Find out about the key risks to this Wallenstam narrative.
Another View: What Wallenstam’s P/E Is Saying
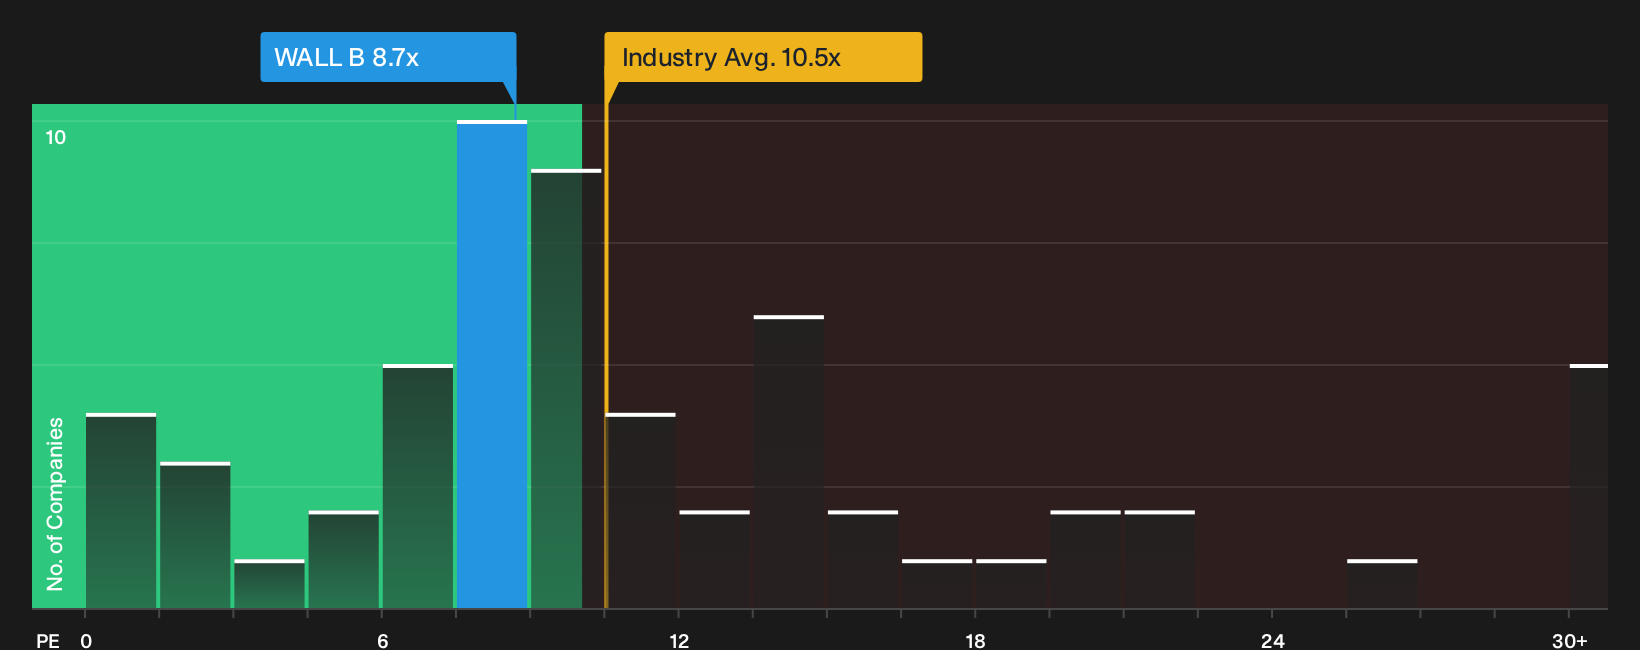
The first storyline argues Wallenstam looks a little rich against a SEK34 fair value. Yet the current P/E of 8.7x tells a softer story when set beside the Swedish real estate sector on 10.4x and peers around 21.3x, while the fair ratio also lands at 8.7x.
That mix signals a market that prices Wallenstam roughly in line with its own history but at a discount to rivals. This lowers the margin for error if earnings keep slipping, yet also limits upside if the business surprises on profits. Which side of that trade off feels more realistic to you at SEK36.22?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mix of cautious headlines and pockets of optimism feel balanced to you, or tilted too far in one direction? Consider Wallenstam’s full risk and reward profile for yourself by checking the 4 key rewards and 3 important warning signs
Looking for more investment ideas beyond Wallenstam?
If Wallenstam has you thinking harder about value, do not stop here. Fresh ideas often show up where the usual watchlists never look.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (203 results) to filter for financially grounded businesses before conditions change again.
- Hunt for mispriced opportunities by checking the 195 high quality undervalued stocks and see which stocks screen as stronger on quality and price than their current sentiment suggests.
- Put income potential on your radar with the 217 dividend fortresses and spot higher yielding payers that still clear key financial health checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com