


- Main Street Capital released preliminary Q3 2026 estimates showing its net asset value per share higher for a seventeenth straight quarter and received regulatory approval to lift SBIC debenture borrowing capacity by US$75 million to US$425 million.
- The combination of steady NAV per share gains and expanded SBIC borrowing room indicates that the business is still finding opportunities to deploy capital across its lower middle market and private loan portfolios while preserving balance sheet flexibility.
- The next area of focus is how Main Street Capital's extended run of NAV per share growth could reshape its broader investment narrative.
Compare Main Street Capital's extended NAV and balance sheet story with other potential income and credit opportunities by scanning our curated list of 8 dividend fortresses in similar financing-heavy sectors.
Main Street Capital Investment Narrative Recap
Main Street Capital appeals to investors who want a lender and equity partner focused on lower middle market and private loans that can support a relatively high distribution while keeping net asset value moving in the right direction. The key short term catalyst remains whether new investments and fee income can offset higher funding costs and softer dividend income from portfolio exits.
The biggest operational risk is that credit quality or fair value marks in the expanded lower middle market and private loan book start to work against that NAV momentum, especially with debt not well covered by operating cash flow. The latest update on NAV and borrowing capacity does not remove those concerns, but it does not materially worsen them either.
The clearest announcement for this story is the US$75 million increase in SBIC debenture borrowing capacity to US$425 million. That extra headroom gives Main Street Capital more room to write new lower middle market and private loan deals, which ties directly into the core thesis that fresh originations can support income and fair value gains.
More SBIC leverage also sharpens the execution test. Management now needs to place that additional capital without allowing nonaccruals, fair value write downs or funding costs to erode dividend coverage that already leans on interest income and realized gains. For readers, the next few quarters of deployment, credit performance and distribution metrics will show whether this added capacity is working for or against the existing risks.
Main Street Capital's analyst narrative points to forecast revenue of US$731.9 million and earnings of US$375.5 million by 2029. This reflects 8.4% yearly revenue growth but an earnings decline of about US$75.8 million from current earnings of US$451.3 million.
Discover how Main Street Capital's fair value indicates an 11% potential upside to its current price that could close faster than many income investors expect.
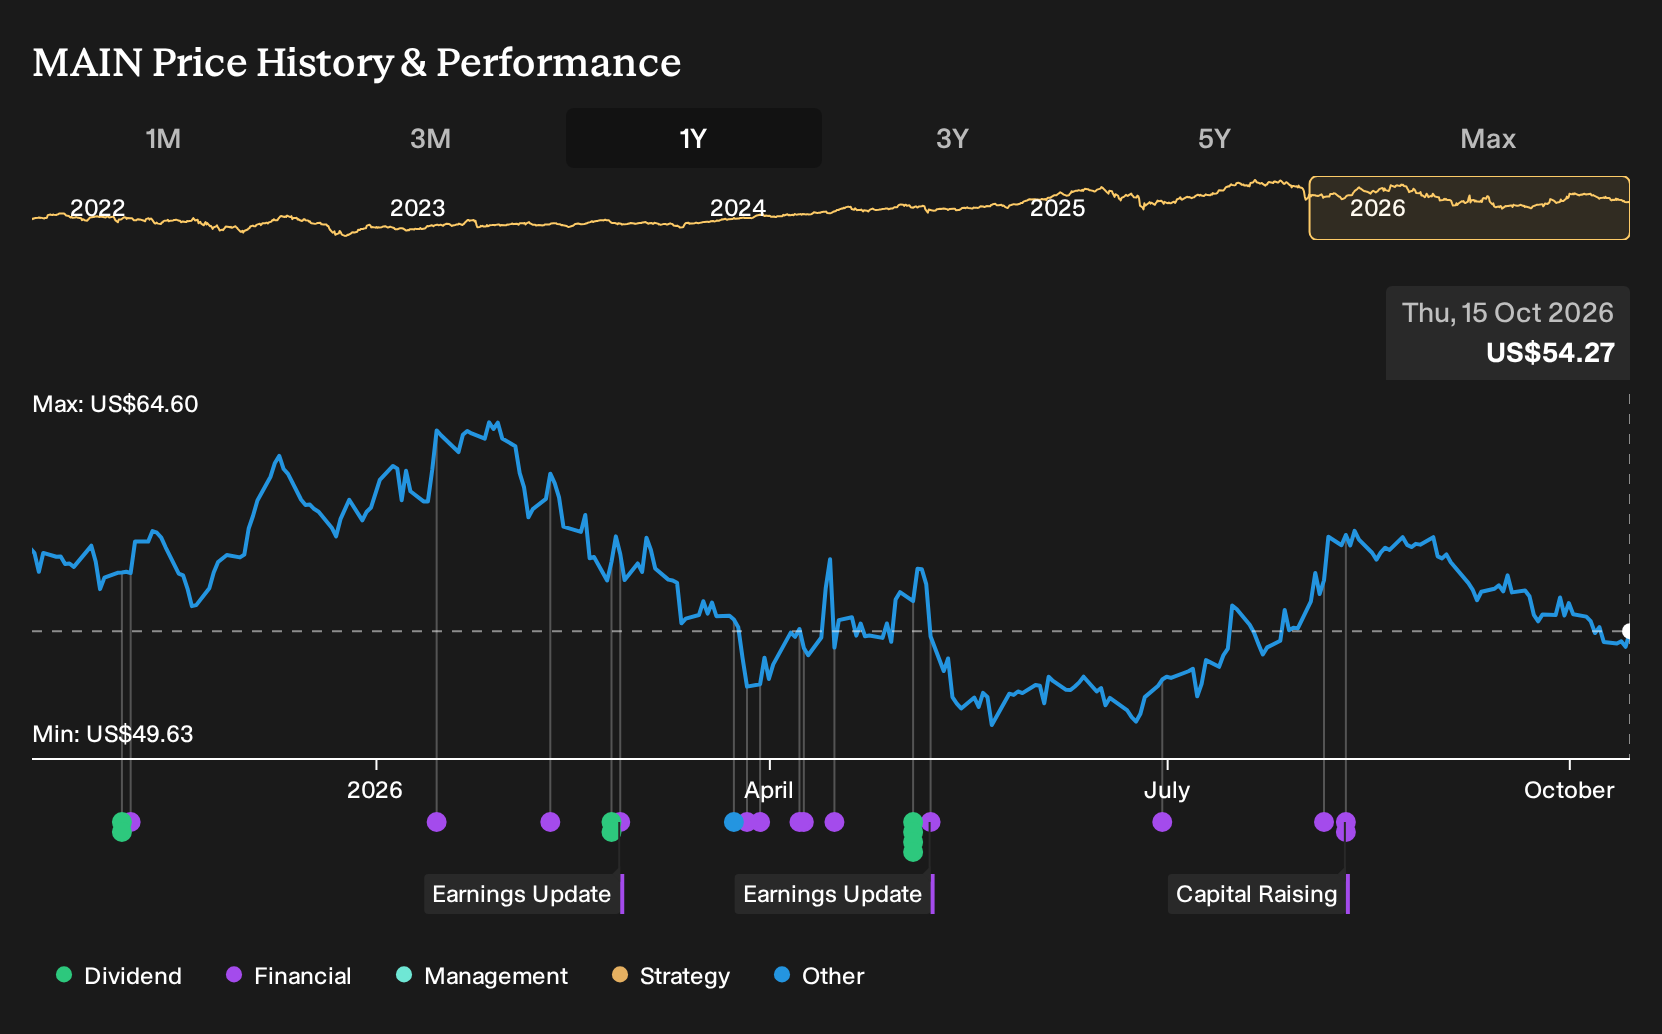
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$40.23 and US$60.33 per share, so opinions on Main Street Capital already span a wide band. You are weighing those varied views against rising funding costs and concentration in lower middle market and private loans, which could influence how future income and fair value marks evolve. Investor opinions differ widely, so explore several of these alternative viewpoints before forming your own stance.
Explore 2 other Main Street Capital fair value estimates, including one that suggests as much as 11% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Main Street Capital research is our analysis highlighting 1 key reward and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Main Street Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Main Street Capital's overall financial health at a glance.
Looking For More Investment Ideas Beyond Main Street Capital?
If you want to put Main Street Capital in context, it often helps to scan a wider field of income and credit focused opportunities using the Simply Wall St Screener.
- For readers who want potential value combined with quality fundamentals, consider a curated set of 33 high quality undervalued stocks that may warrant a closer look beside Main Street Capital.
- If capital preservation matters as much as return, compare Main Street Capital's profile with a 32 resilient stocks with low risk scores that scores well on resilience and financial strength.
- Income focused investors who like Main Street Capital's distribution can broaden their watchlist with a targeted list of solid balance sheet and fundamentals (25 results) that aims to balance yield with balance sheet support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com