


- E.ON is highlighted as a major European energy operator with regulated power and gas networks, where rising connection demand for renewables, batteries, EVs and heat pumps intersects with a pending regulatory decision that will influence how its energy networks are financially treated.
- The unresolved German network regulation is not just a legal formality but a key variable for how E.ON allocates capital across its grid investment program and manages earnings risk over the coming years.
- The focus then shifts to how E.ON's investment narrative could be reshaped by the pending German network regulation that frames grid returns.
Scan the grid transition theme beyond E.ON by reviewing a hand picked set of power infrastructure and utilities with resilient fundamentals in the 41 power grid technology and infrastructure stocks.
E.ON Investment Narrative Recap
To own E.ON, you need to be comfortable with a regulated grid story where growth is tied to approved network capex and tariff decisions, not big commodity swings. The big belief is that rising demand for connections, from renewables to data centers and EVs, keeps justifying a larger regulated asset base. The unresolved German RP5 decision sits right on that fault line.
Until RP5 is settled, the key near term swing factor is how far E.ON leans into its planned €40b plus of network investment in Germany versus pacing it more cautiously. The main risk is simple. If allowed returns or cost treatment fall short of what management has planned around, grid spending, earnings ambition and dividend headroom may all need recalibrating.
Recent communication around the €48b investment plan for 2026 to 2030 is the most relevant backdrop to the current regulatory story. Around €40b earmarked for Energy Networks sets clear expectations. E.ON is signalling an intention to spend well above depreciation from 2026, which would expand the regulated base as long as projects receive timely approval and tariff recognition.
For you as a shareholder, the open question is how RP5 terms interact with that capex roadmap. Supportive rules around cost of debt, equity returns and OpEx treatment would align with the planned step up in investment. Tougher parameters could push management to re phase or resize some German grid projects and place more weight on earnings delivery from Energy Retail, Energy Infrastructure Solutions and the planned OVO integration in the UK.
E.ON Consensus Assumptions in Plain Numbers
E.ON's narrative projects €91.0b revenue and €3.5b earnings by 2029. This rests on 6.5% yearly revenue growth and a €0.1b earnings increase from €3.4b today.
Analysts are effectively sketching a picture where the grid and customer platforms scale up together, even as margins soften a little. Revenue is expected to compound at 6.5% a year over the next three years, while profit margins are modelled to edge down from 4.5% today to 3.9% by year three.
Earnings in this framework move from €3.4b today to a consensus €3.5b by 2029, with a wide spread of views around that central line. At the bullish end, forecasts reach €3.9b of profit; the most cautious estimates point to €2.7b, which shows how much uncertainty investors are placing on regulation, execution and mix across networks and retail.
The same 2029 snapshot that anchors the E.ON story also carries a valuation assumption. To line up with the current analyst targets, the shares would need to trade on a P/E of 18.2x those forecast earnings, compared with 13.3x today and 15.6x for the wider GB Integrated Utilities peer group cited in the report.
On the revenue side, the consensus path to €91.0b by 2029 sits alongside the earnings forecast of €3.5b. That pairing of top line and profit implies the lower margin profile analysts are already baking in, and it makes the allowed returns in RP5 a key piece of the puzzle for anyone stress testing these outcomes.
Uncover why E.ON's fair value indicates a 20% potential upside to its current price that could close faster than many investors expect.
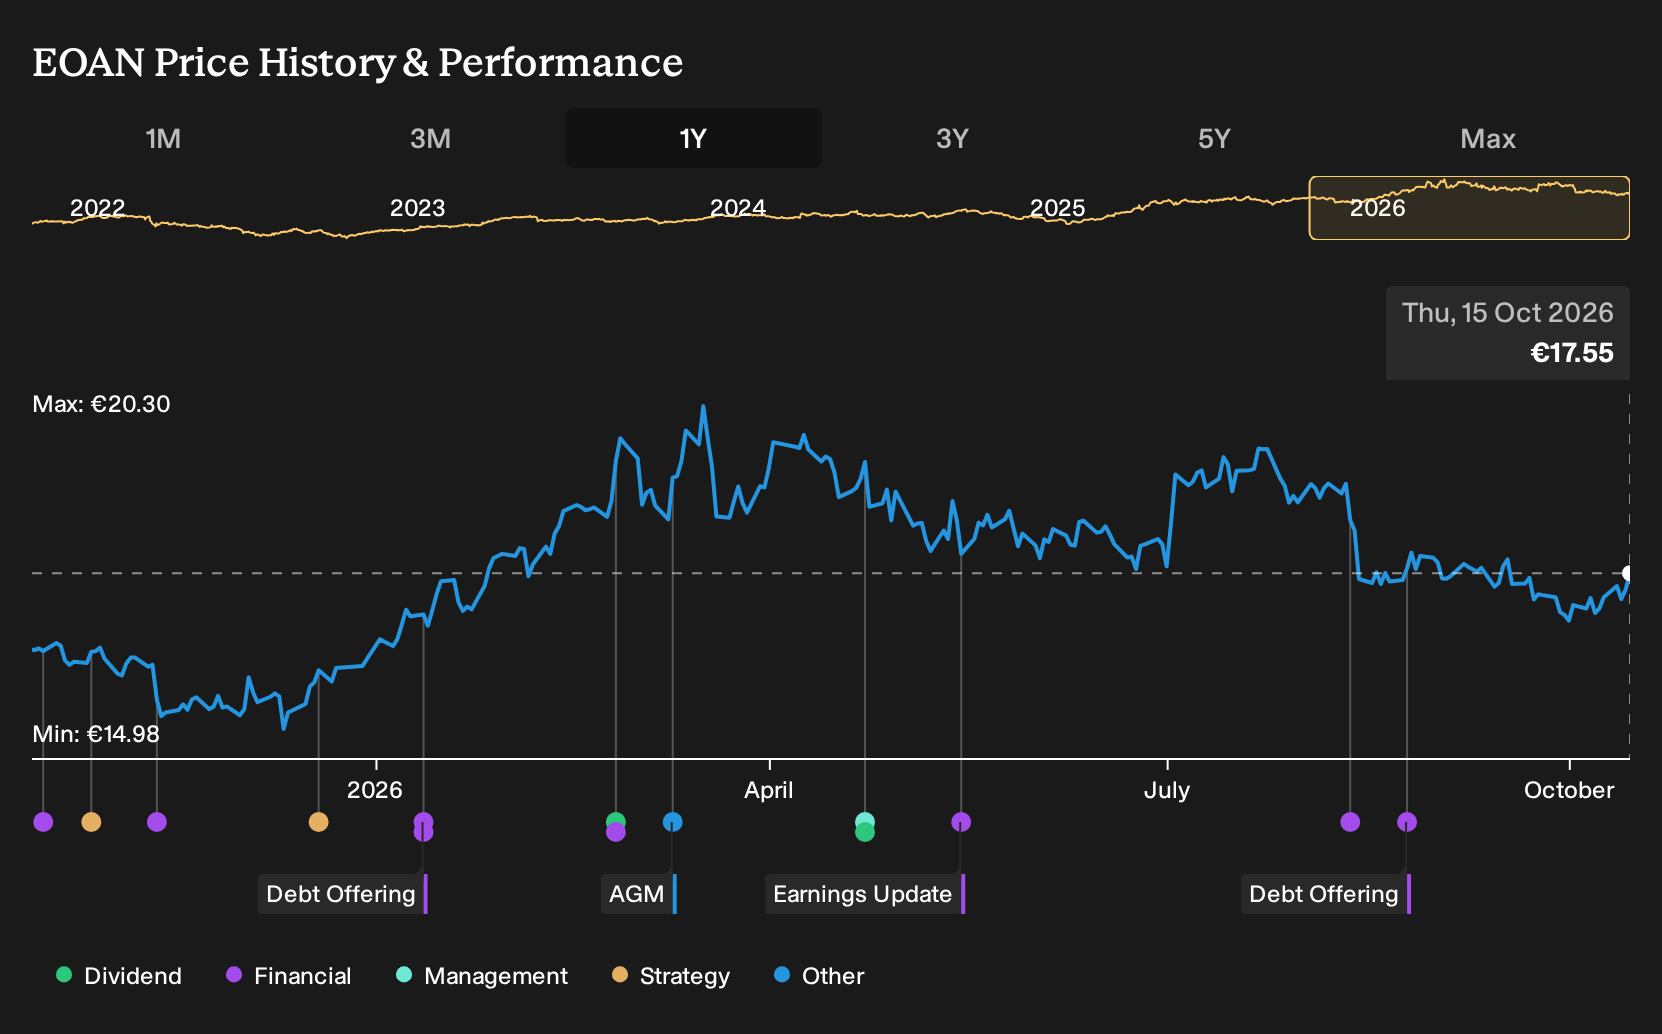
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster in a tight band between €18.65 and €20.98, so retail opinion on E.ON currently leans more aligned than split. Your bigger swing factor is RP5. Any ruling that cuts into grid returns could challenge those forecasts and makes it worth comparing several contrasting views.
Explore 2 other E.ON fair value estimates, including one that suggests it could be worth just €18.65.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your E.ON research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for E.ON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate E.ON's overall financial health at a glance.
Looking for more investment ideas beyond E.ON?
Once you have formed a view on E.ON, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles on the Simply Wall St Screener.
- If you want potential mispricing with quality in mind, start by scanning a curated set of companies flagged as 195 high quality undervalued stocks that pair strong fundamentals with more modest valuations.
- For investors who care most about stability and balance sheet strength, focus on businesses in the list of solid balance sheet and fundamentals (203 results) to see which issuers carry less financial strain.
- If you are hunting for underfollowed stories, filter for companies in the 617 high quality undiscovered gems that couple solid financials with lower levels of current market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com