


Analyst sentiment toward Allegion (ALLE) has turned more positive ahead of the upcoming October 22 earnings release, with expectations focused on higher revenue and a year-over-year improvement in quarterly profit.
At a share price of US$155.75, Allegion has seen short term momentum pick up, with a 1 day share price return of 2.13% and a 90 day share price return of 13.49%. This comes even though the year to date share price return has declined 3.21% and the 1 year total shareholder return has fallen 10.97%, compared with a much stronger 65.06% total shareholder return over three years that points to gains built over a longer holding period.Compare Allegion’s earnings setup with a handpicked group of companies showing similar momentum using the 33 high quality undervalued stocks as a starting point for further ideas.
The recent bounce in Allegion appears linked to improving earnings expectations as well as a changing mood around the stock. The next step is to see whether that shift aligns with what the current valuation implies.
Most Popular Narrative: 11% Undervalued
Against Allegion’s last close at $155.75, the most followed narrative points to a fair value of about $174.64, creating a valuation gap that rests on specific earnings and margin assumptions rather than sentiment alone.
Robust expansion in smart and connected security solutions, with low teens electronics growth in the Americas in Q2 2026 and a pipeline of new Allegion products such as Schlage XE360 with RealSync Wi Fi and the Sense Pro smart deadbolt with Matter over Thread, supports a higher mix of recurring and software linked revenue and can lift both future revenue and adjusted operating margin.
See why 12 investors see Allegion as 11% undervalued.
Result: Fair Value of $174.64 (UNDERVALUED)
Still, the bullish Allegion story depends on electronics growth remaining strong and on international restructuring delivering planned cost savings, rather than dragging on margins for longer.
Find out about the key risks to this Allegion narrative.
Another View: Allegion Through The Market’s Lens
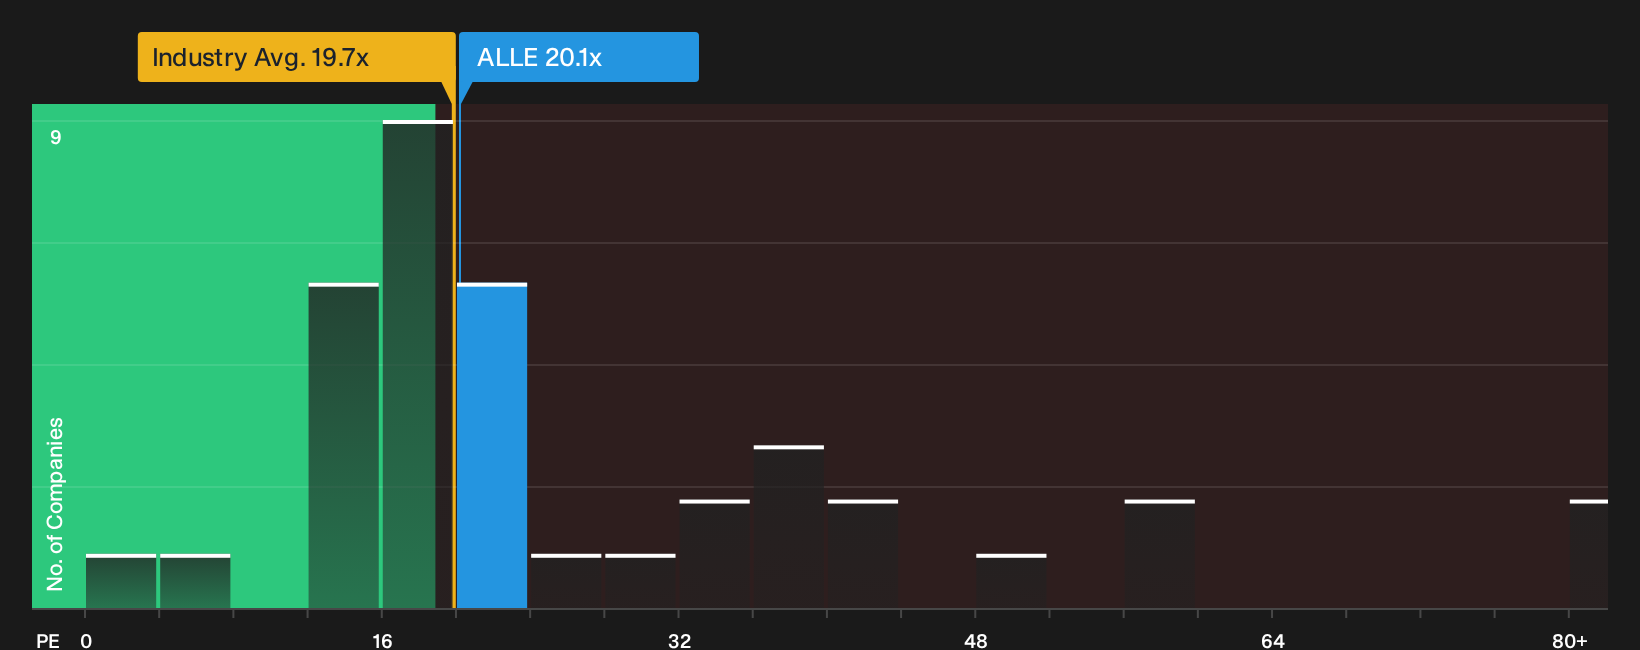
Allegion looks cheaper than many peers on headline numbers, with a P/E of 20.1x versus a peer average of 33.2x. However, it trades slightly above the Simply Wall St fair ratio of 20.6x and also above the US Building industry on 19.3x, which tightens the margin for error if growth underwhelms.
For investors comparing these signals, the question is whether a small gap to the fair ratio and a premium to the sector represent a reasonable price for Allegion’s earnings profile, or a setup where any earnings wobble could affect the multiple significantly.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages so far on Allegion, with valuation and sentiment pulling in different directions, make this a moment to move quickly and test the story against your own thresholds. To weigh both sides of the argument in one place, start with the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Allegion?
If Allegion has sharpened your focus on quality setups, do not stop here. Fresh ideas often appear where pricing, balance sheets, and income streams look different.
- Target stronger potential upside by scanning a curated pool of undervalued opportunities using the 33 high quality undervalued stocks.
- Prioritise resilience by zeroing in on companies with solid finances through the list of solid balance sheet and fundamentals (25 results).
- Build your income watchlist by reviewing dependable payout candidates via the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com