


Global markets are fixated on inflation and interest rate calls after Fed chair Kevin Warsh reaffirmed price stability as the priority, which keeps volatility alive and rewards clear leadership. Founder led Australian companies can be appealing because the people who built the business are still on the hook. This article walks through three founder led stocks from our screener that highlight how that kind of alignment can matter.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is deeply invested in long term performance. However, if you want the strongest names, these 7 top founder-led companies are at the top of the list.
Flight Centre Travel Group (ASX:FLT)
Flight Centre Travel Group is a founder rooted travel retailer and corporate travel manager, with the Flight Centre and Corporate Traveller brands anchoring that culture across leisure and business clients.
It generates about A$1.4b from leisure travel, A$1.2b from corporate services and A$248 million from global headquarters activities, and the stock is valued at roughly A$2.1b by the market.
For founder led investors, Flight Centre Travel Group is a useful test case for how long term owner operators handle heavy reinvestment in new loyalty and product engines without losing financial discipline.
"Despite the rapid customer growth in World360 Rewards, the program has already consumed about A$34 million in below the line spend in FY26 and is expected to incur up to roughly half that amount in FY27 within operating costs, which can weigh on reported EBIT and delay any earnings contribution from higher frequency or partner funded revenue."
What happens to margins if a single underpinning assumption here breaks in either direction will matter a lot for founder focused holders.
That margin question is exactly what the full narrative for Flight Centre Travel Group unpacks. It shows where reinvestment could be masking underlying strength and where founder alignment might accelerate the next phase.

Harvey Norman Holdings (ASX:HVN)
Harvey Norman Holdings is a founder influenced retail and property group built around furniture, bedding, electricals and computing chains. Gerry Harvey and family still shape how the franchise, property and digital systems fit together for long term legacy rather than short term fashion.
It earns A$951 million from New Zealand, A$787 million from Singapore and Malaysia, A$777 million from Ireland, A$260 million from Slovenia and Croatia, A$232 million from non franchised outlets, and the stock carries a market value of about A$5.1b.
For a founder led screen, Harvey Norman is notable because the same people who helped assemble that hybrid of retail, franchise fees and rental income still have strong influence over capital allocation, property ownership choices and how much risk the balance sheet is prepared to accept.
"That blue-chip character was challenged in 2025, when Harvey Norman reported net profit growth of 47% year-on-year."
What happens when one pressure point on that founder driven retail and property engine shifts will play a significant role in shaping future returns.
If that pressure point matters to you, the full narrative for Harvey Norman Holdings shows how Harvey Norman could turn that profit jolt into either a durable reset or a short lived spike.
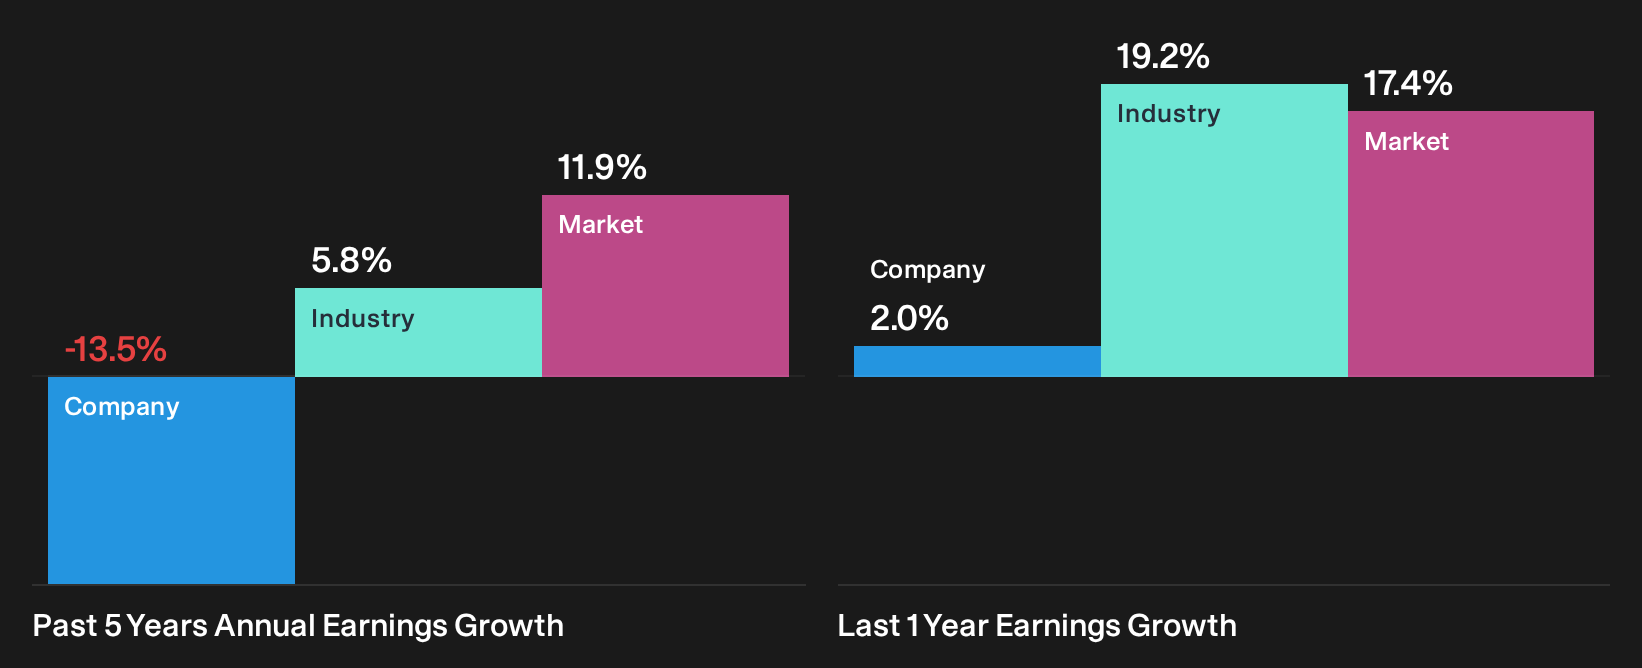
GenusPlus Group (ASX:GNP)
GenusPlus Group builds and maintains the hard wiring of Australia’s energy transition, from high voltage lines to grid connections. It also runs Services and Infrastructure arms that generate A$152 million and A$837 million, alongside A$369 million from Energy and Engineering, with the stock valued at about A$1.8b.
GenusPlus Group fits this founder led screen because its Energy and Engineering arm is directly tied to the long life grid projects founders often want their capital aligned with. At the same time, the group still spreads risk across a broader infrastructure and services platform.
"Rapid expansion of battery energy storage systems, solar and broader electrification work, coupled with GenusPlus’ track record and rounded Energy and Engineering offering from design through maintenance, underpins a deep pipeline of medium to large projects that can structurally lift segment margins and group EBITDA."
What happens if a single assumption about how quickly those projects convert into higher quality earnings shifts will matter a lot for founder focused holders.
If that shift is what you care about, the full narrative for GenusPlus Group shows where earnings quality could be accelerating, stalling, or quietly decoupling from headline project wins.

Seeking Alternatives Before Momentum Flies
Fresh opportunities move fast, and the best breakout stories rarely stay under the radar for long. Scan what others may miss while it matters, then get in early.
- Target steadier cash flows and potential income resilience by reviewing a curated group of 4 dividend fortresses before yields get caught dropping as prices react to renewed demand.
- Ride structural electrification trends by checking the hand picked 41 power grid technology and infrastructure stocks while these infrastructure plays are still flying under most investors’ screens, then act now.
- Position for possible metals momentum by scanning the focused 35 elite gold producer stocks before any fresh interest in producers tightens entry points and compresses obvious upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com