


Coca-Cola Europacific Partners (ENXTAM:CCEP) has committed $39.7 million to its Kewdale plant in Western Australia, adding a canning line that lifts capacity by over 40% and targets around the clock output in peak summer.
For investors watching Coca-Cola Europacific Partners, the recent Kewdale upgrade comes alongside strong share price momentum, with a 1-month share price return of 9.91% and a year-to-date share price return of 31.25% at a latest share price of €98.7.
Scan for other beverage players with similar momentum and capital investment stories by reviewing the hand picked 617 high quality undiscovered gems that share some of Coca-Cola Europacific Partners' quality traits.
Bulls see Coca-Cola Europacific Partners using Kewdale scale and global reach to justify a richer price. Bears point to an already strong run and execution risk on fresh capex. Which side does the valuation lean toward next?
Most Popular Narrative: 3.2% Overvalued
Coca-Cola Europacific Partners last closed at €98.7, compared with a narrative fair value of €95.68, which frames the current enthusiasm as slightly ahead of that benchmark while still rooted in detailed earnings and cash flow expectations.
The ongoing expansion into emerging markets, especially Indonesia and the broader Asia-Pacific region, positions CCEP to benefit from rising consumption fueled by a young, urbanizing, and rapidly growing middle class, supporting long-term top-line revenue growth as macroeconomic conditions improve.
See why 6 investors see Coca-Cola Europacific Partners as 3% overvalued.
Result: Fair Value of €95.68 (OVERVALUED)
Still, tighter sugar regulation and rising sustainability costs could squeeze Coca-Cola Europacific Partners' margins and weaken the pricing power that underpins the current fair value narrative.
Find out about the key risks to this Coca-Cola Europacific Partners narrative.
Another View: Cash Flow Points to Undervaluation
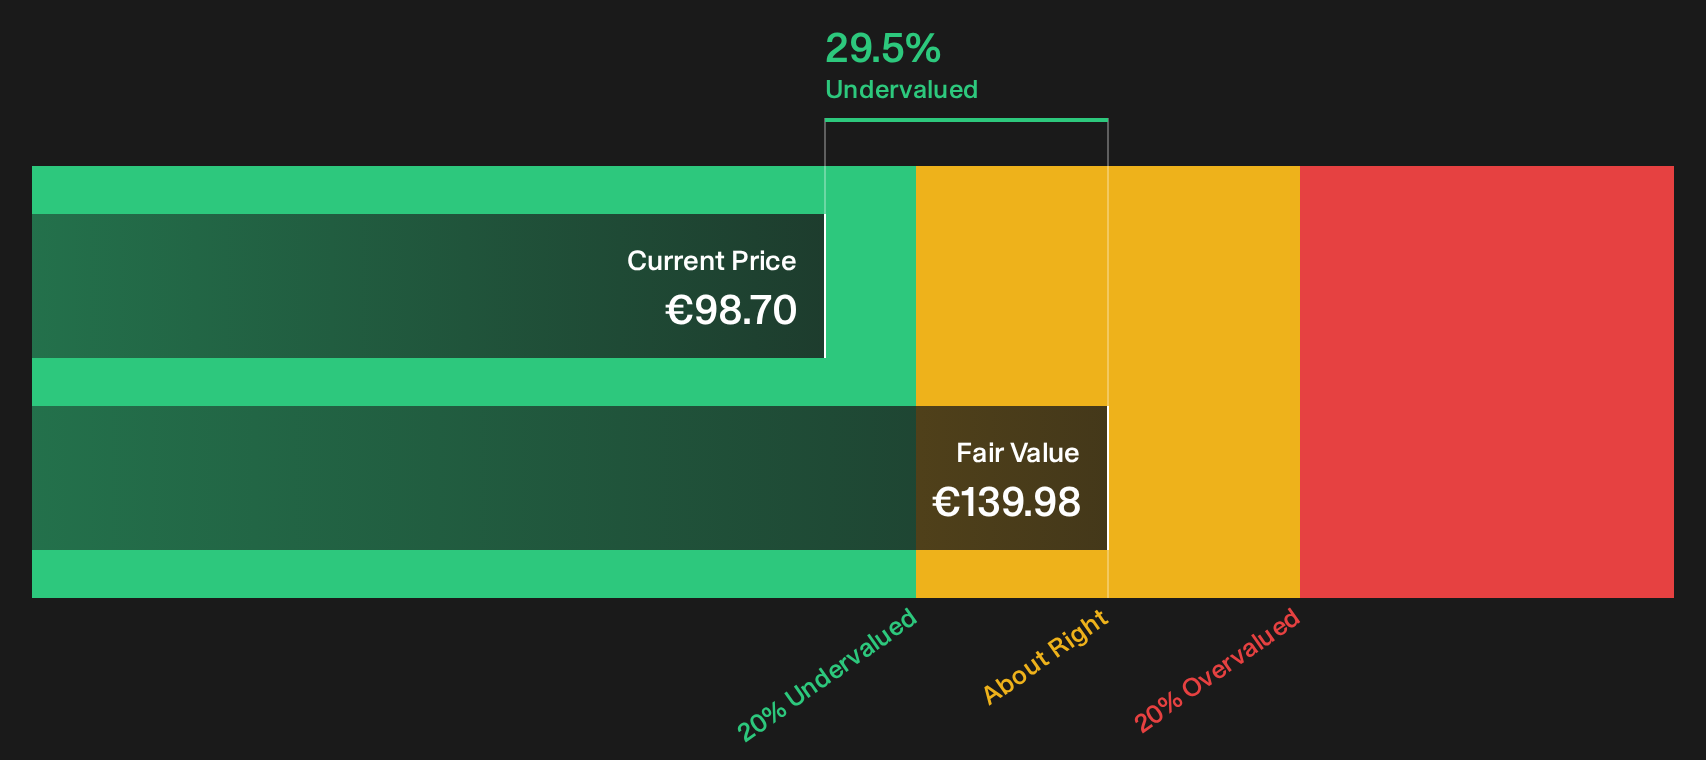
While the prevailing narrative pegs Coca-Cola Europacific Partners at about 3.2% above its €95.68 fair value, the SWS DCF model paints a different picture. On that cash flow view, CCEP at €98.7 trades roughly 29.5% below an estimated value of €139.98, which raises a simple question: Is the crowd leaning too heavily on near term sentiment and multiples, or is the long term cash flow story being misread?
To see how that cash flow estimate is built and where the key assumptions sit, take a close look at the Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Coca-Cola Europacific Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Confident that Coca-Cola Europacific Partners is priced right after all of this, or still on the fence given the mixed signals? Act quickly and stress test that view against the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Coca-Cola Europacific Partners?
If Coca-Cola Europacific Partners has sharpened your focus, do not stop here. Use the Simply Wall Street Screener to uncover fresh ideas before others spot them.
- Target higher quality opportunities by checking companies flagged as 195 high quality undervalued stocks that may offer stronger fundamentals than their current prices suggest.
- Build a steadier income stream by reviewing the 217 dividend fortresses that aim to pair yields of 5% or more with resilience.
- Limit downside shocks by focusing on the 228 resilient stocks with low risk scores that combine lower risk scores with more durable financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com