


Orchid Island Capital (ORC) just reported an estimated third quarter net loss per share of $0.90 and reaffirmed its monthly dividend of $0.10, putting its income focus and RMBS risk profile under the spotlight.
Recent trading tells a mixed story. Orchid Island Capital’s share price has risen over the past week but is still down 14.9% over 30 days and 24.4% over 90 days, while the 3 year total shareholder return of 37.6% contrasts with a 48.2% decline over 5 years. This suggests that momentum has been fading again after a shorter rebound phase.
Compare Orchid Island Capital’s income-focused profile with a curated 8 dividend fortresses designed to balance yield with more resilient business fundamentals.
Orchid Island Capital now trades well below the average analyst target, yet the stock recently bounced even as losses on RMBS and derivatives weighed on results. Is this a warranted discount or an overreaction that has skewed fair value?
Preferred P/E of 4.2x: Is it justified?
On simple earnings maths, Orchid Island Capital looks inexpensive. With a P/E of 4.2x at a last close of $5.18, the stock trades at a marked discount to both the wider US market and its own Mortgage REIT peer group. This points to the market pricing in meaningful risk around its RMBS exposure and dividend sustainability.
The P/E ratio compares what you pay per share with the earnings that share represents. For a mortgage REIT such as Orchid Island Capital, this gives a quick read on how investors are weighing current profitability against concerns about book value volatility, leverage and the ability to keep paying a high yield when earnings and cash flows do not fully cover the dividend.
Here the gap is wide. Management is being marked at 4.2x earnings while the US Mortgage REITs industry trades at 7.8x and the peer average sits at 6.8x. The estimated fair P/E of 12.1x is even higher. That is a level the market could move toward if investors become more comfortable with Orchid Island Capital’s earnings quality, RMBS risk profile and capital allocation choices after a period of heavy shareholder dilution and an uncovered 23.17% yield.
Explore the SWS fair ratio for Orchid Island Capital.
Result: Price-to-earnings of 4.2x (UNDERVALUED)
Still, Orchid Island Capital faces clear swing factors, including RMBS price volatility and the pressure of maintaining a high dividend alongside an uncovered yield.
Find out about the key risks to this Orchid Island Capital narrative.
Another view on Orchid Island Capital’s value
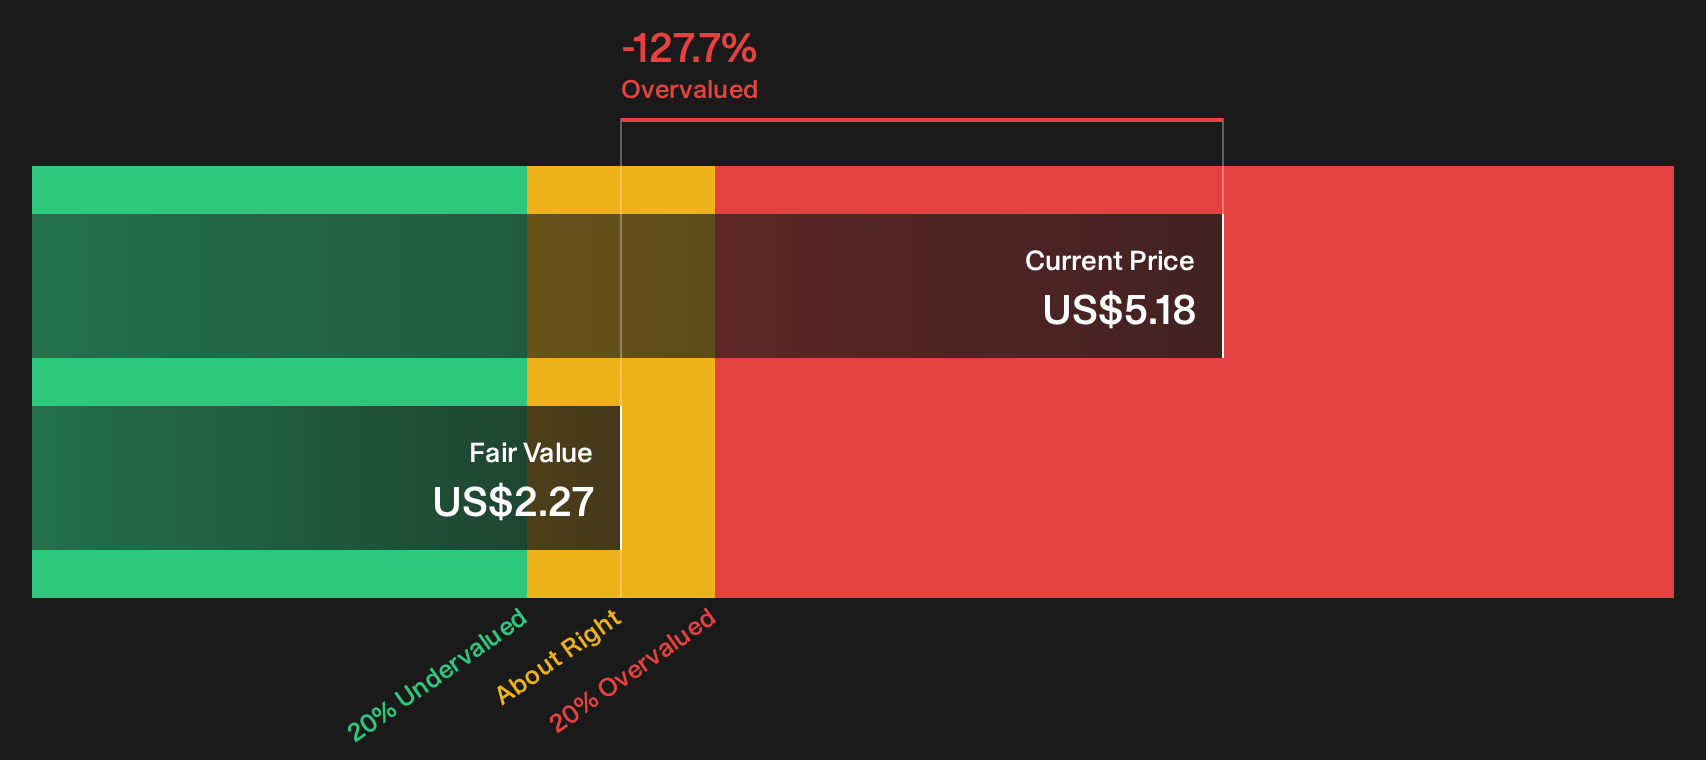
The earnings multiple paints Orchid Island Capital as cheap, yet the SWS DCF model tells a different story. On that cash flow based lens, the estimated value sits at $2.27 per share while the recent price is $5.18, which points to a stock trading well above this intrinsic estimate.
That gap matters. A low 4.2x P/E hints at a bargain, while a DCF value less than half the current share price suggests a margin of safety might be thinner than it first appears. It leaves investors weighing which lens they trust more when sizing any position.
For readers who want to see exactly how that cash flow view is built, the full calculation sits inside the SWS DCF model. It includes the assumptions that drive this $2.27 figure and shows how sensitive it is to changes in the outlook for Orchid Island Capital, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Orchid Island Capital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Orchid Island Capital's valuation and risk profile are clear, so step into the data yourself and decide what really matters for you. To weigh both the caution flags and potential upside in one place, review the 4 key rewards and 3 important warning signs.
Looking for more Orchid Island Capital sized ideas?
If Orchid Island Capital has you rethinking your watchlist, do not stop here. Broader idea hunting with focused tools can sharpen your overall portfolio decisions.
- Target stronger balance sheets and steadier fundamentals by running a focused search through the list of solid balance sheet and fundamentals (25 results).
- Hunt for better value candidates by filtering companies that currently look mispriced using the 33 high quality undervalued stocks.
- Prioritise income opportunities by screening for higher yielding payers that also show healthier fundamentals through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com