


- NiSource, through its GenCo segment, recently finalized a 20-year energy agreement with Microsoft for a northwest Indiana data center campus, with Microsoft fully funding roughly 1,100 MW of new generation, related transmission and 600 MW of contracted battery storage.
- The structure keeps NiSource’s existing NIPSCO customers insulated from data center costs while targeting about US$1.75b in total expected bill savings and upgrades to grid reliability.
- We will now look at how NiSource's long term Microsoft funded data center load could reshape the existing regulated investment narrative.
NiSource Investment Narrative Recap
To own NiSource, you need to be comfortable with a regulated utility that is leaning into very large power users while still carrying a heavy gas and electric capex load. The Microsoft deal underpins that thesis. It supports long duration electric demand and grid upgrades without shifting incremental data center costs onto existing NIPSCO customers.
In the near term, the key catalyst remains regulatory follow through on the broader US$28.6b capital plan and GenCo contracts. The biggest risk is still cost recovery and funding, given elevated capex, equity issuance and interest coverage flagged as tight. The Microsoft agreement helps the story, but it does not remove those financing and regulatory pressures.
The most relevant recent update is NiSource’s plan to discuss third quarter 2026 results and a business update on October 28. That call provides the next checkpoint on how the Microsoft contract fits into the larger 4 GW of signed data center capacity and the US$21b core utility capex plan.
Listen for concrete detail on how GenCo, including the 1,100 MW of Microsoft funded generation and 600 MW of contracted storage, interacts with leverage, equity needs and customer bill impacts. Any new information on storm related costs, Indiana gas modernization scrutiny and the timing of future large load agreements will help frame both the earnings trajectory and the risk around future rate decisions.
NiSource's current analyst narrative points to forecast revenue of US$8.4b and expected earnings of US$1.3b by 2029. That outlook is based on an assumed 6.9% yearly top line growth rate and an earnings increase of about US$394m from current earnings of US$906.0m.
Uncover why NiSource's fair value indicates an 18% potential upside to its current price that could narrow quickly.
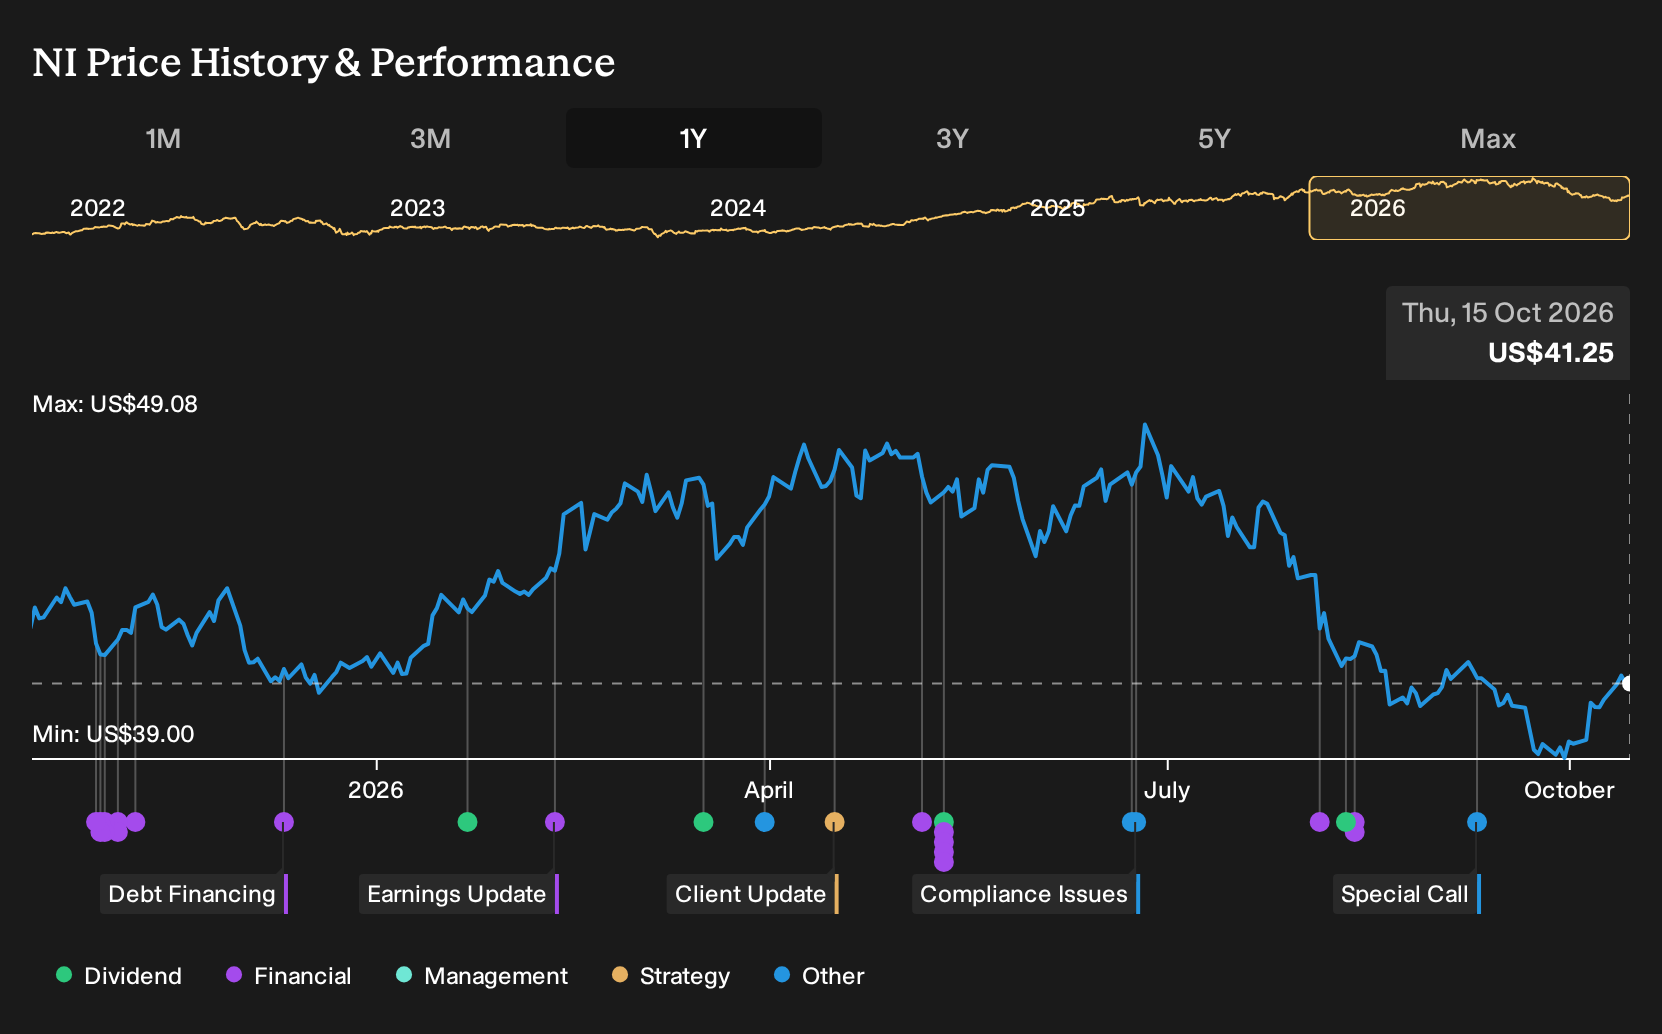
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between US$35.97 and US$48.73 per NiSource share, so the highest community estimate sits well above the lowest. Those retail perspectives do not yet reflect the Microsoft agreement or storm and regulatory noise, so you should weigh them against data center upside and gas transition risk.
Explore 2 other NiSource fair value estimates, including one that suggests as much as 18% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your NiSource research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for NiSource. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NiSource's overall financial health at a glance.
Looking for more investment ideas beyond NiSource?
Once you have a view on NiSource, broaden your watchlist by scanning for other companies that match the kind of balance sheet strength, income profile or valuation edge you want in your portfolio.
- For investors who care about strong fundamentals and resilient finances, start with this list of solid balance sheet and fundamentals (25 results) to see which businesses pass tougher balance sheet checks.
- If steady income is your priority, use the 8 dividend fortresses to find companies with higher yields that may complement a regulated utility like NiSource.
- To cast a wider net for mispriced opportunities, run through the 33 high quality undervalued stocks and compare those potential candidates with NiSource on risk, quality and valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com