


Domino's Pizza Enterprises (ASX:DMP) is back in focus after the global brand owner signalled it may hand underperforming international territories to new operators if sales do not recover, which is sharpening attention on the franchisee’s current challenges.
At around A$21.40 per share, Domino's Pizza Enterprises has seen a 30 day share price return of 13.41% and a 90 day share price return of 21.45%. However, the year to date share price return is slightly down 1.92%, while the 1 year total shareholder return of 45.66% sits against a 3 year total shareholder return that has declined 54.35% and a 5 year total shareholder return that has fallen 81.55%. This points to momentum rebuilding in the short term after a difficult multi year stretch as investors reassess the risks around underperforming territories and profitability.
Scan for other consumer stocks rebuilding momentum and facing similar profitability pressures with our curated list of 4 high quality undervalued stocks.
Bulls point to Domino's Pizza Enterprises’ short term share price rebound and recent net income growth. Bears focus on the loss, pressured territories and brand owner warnings. Which side do the current valuation signals lean toward?
Most Popular Narrative: 6% Overvalued
At A$21.40, Domino's Pizza Enterprises trades above the most followed fair value estimate of A$20.28, which leans the current story toward a mildly expensive valuation built on profit recovery and margin repair.
Streamlined cost structures achieved by reducing SG&A, IT, and marketing overheads will enable reinvestment in high-impact marketing and operational support, supporting both revenue growth and operating margin expansion over the medium to long term.
See why 41 investors see Domino's Pizza Enterprises as 6% overvalued.
Result: Fair Value of A$20.28 (OVERVALUED)
Still, rising competition from delivery aggregators and the unresolved Gall class action, with wider exposure yet unquantified, could easily challenge the Domino's Pizza Enterprises recovery story.
Find out about the key risks to this Domino's Pizza Enterprises narrative.
Another View: Domino's Pizza Enterprises On Sales Based Pricing
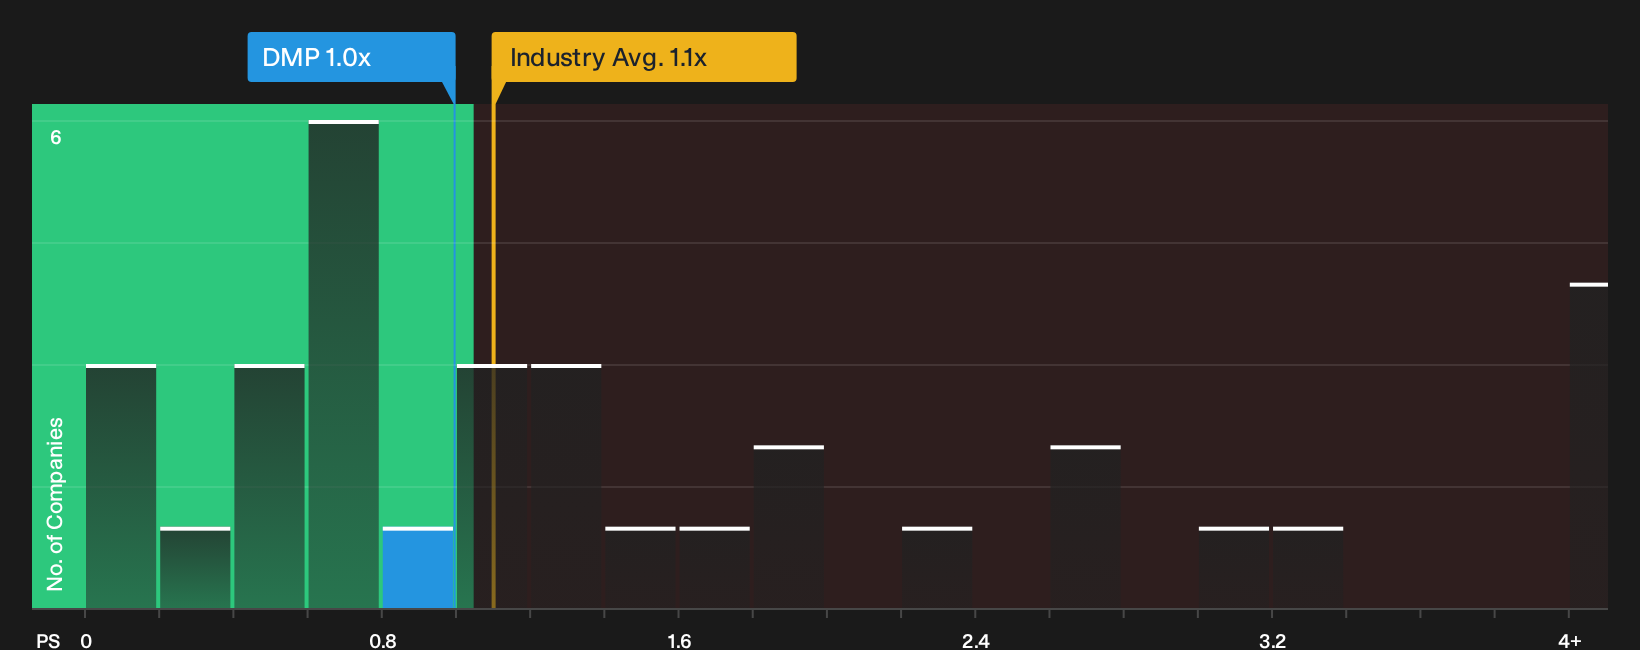
There is a twist when you swap from fair value models to simple sales based pricing. On a P/S of 1x, Domino's Pizza Enterprises trades below peers at 1.7x and slightly below the Australian Hospitality group at 1.1x, which points to relatively lower expectations being priced in.
The fair ratio is also 1x, so the current P/S lines up closely with where the market could drift over time. If sentiment or results change, does that narrow gap to peers become a cushion for downside risk or a ceiling on upside?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Domino's Pizza Enterprises rarely stay mixed for long. Consider reviewing the figures for yourself, then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Domino's Pizza Enterprises?
Do not stop with Domino's Pizza Enterprises. Broaden your watchlist now and compare other opportunities side by side so you are not guessing where the next idea comes from.
- Spot potential turnaround opportunities early by scanning companies that trade below what their quality might justify using the 4 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies that pay higher yields and still show resilience through the 4 dividend fortresses.
- Reduce portfolio stress by focusing on businesses with stronger finances and healthier balance sheets using the list of solid balance sheet and fundamentals (12 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com