


- Accor has appointed Deeppreet Bindra as Director for ibis and ibis Styles India to oversee portfolio growth, commercial performance, guest experience and team development across the country.
- The hire brings more than two decades of hospitality and service-sector experience at groups such as Oberoi and Marriott, which could influence how Accor manages its economy brands in both established and emerging Indian markets.
- We will now look at how Accor's broader investment narrative could be affected by Deeppreet Bindra leading ibis and ibis Styles India.
Scan how Accor's India push compares with other hospitality operators by reviewing list of solid balance sheet and fundamentals (203 results) that can support expansion without stretching their finances.
Accor Investment Narrative Recap
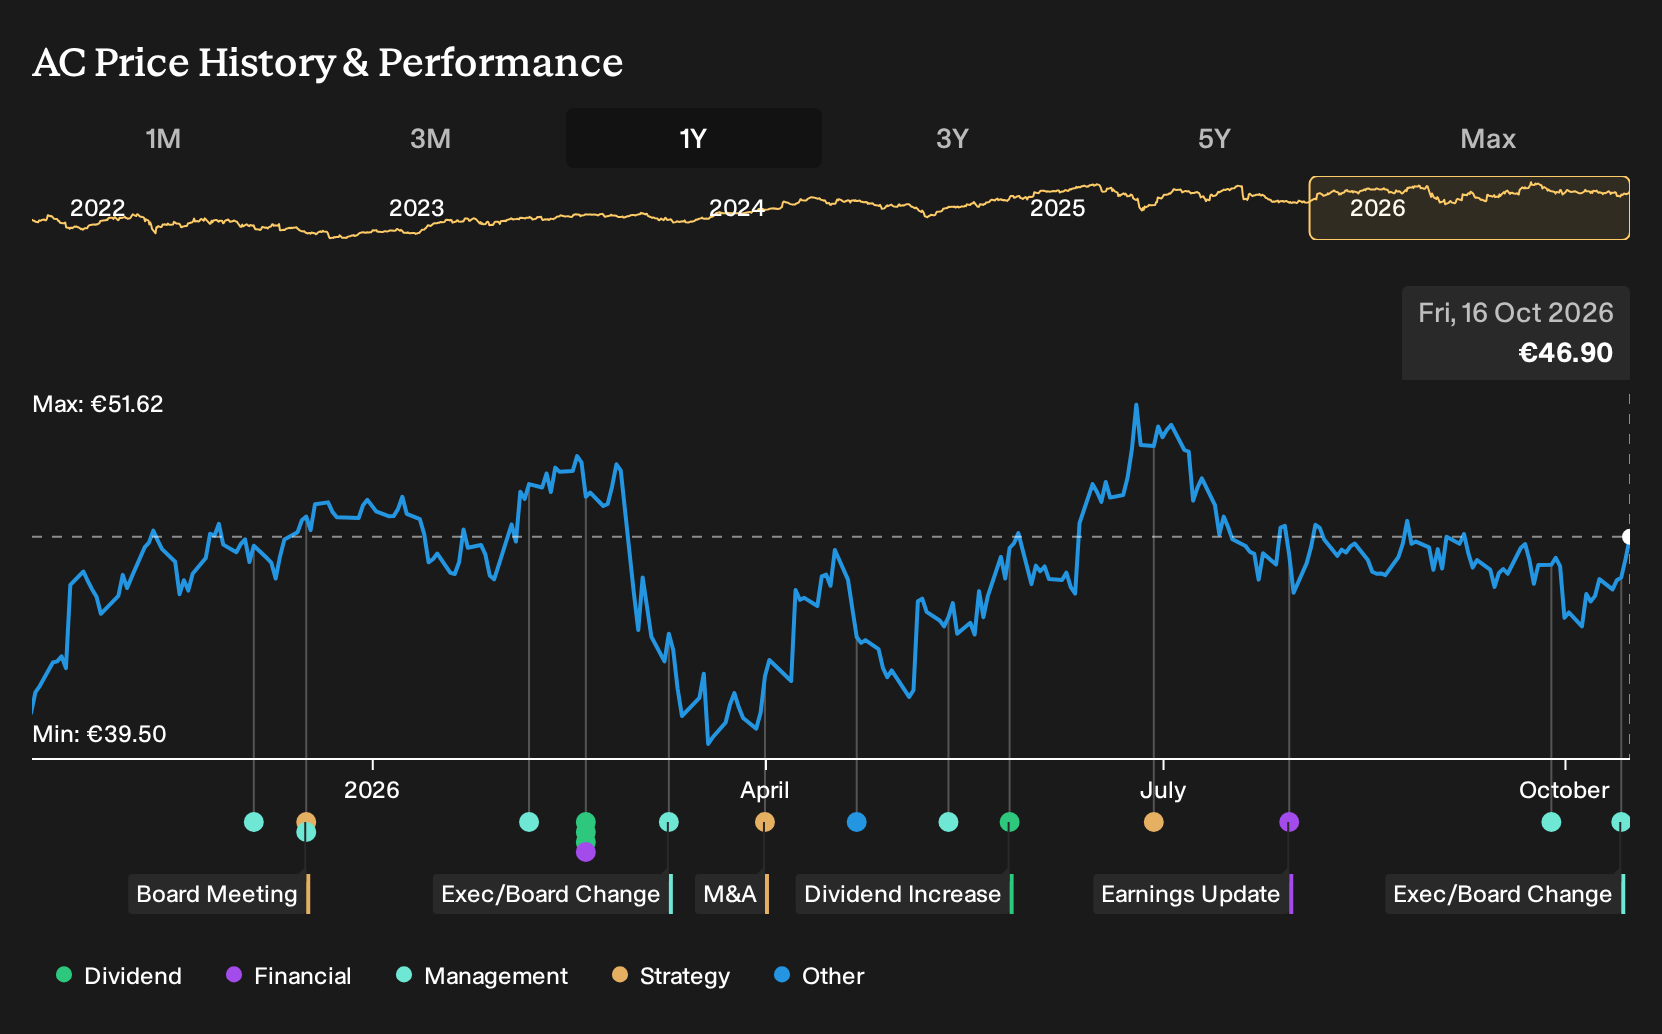
To own Accor, you need to be comfortable with a hotel group leaning into an asset light model, a growing pipeline and a mix of premium and economy brands. The short term swing factor remains how quickly management can translate signings and openings into cleaner earnings, especially after a year where profit margins dropped to 4.1% from 10.3%.
The biggest operational risk still feels tied to execution outside Europe and exposure to FX and leverage rather than one executive move. Deeppreet Bindra’s appointment looks additive but not transformational on its own, so the core near term story around debt, margin quality and franchise economics does not materially change.
With no other recent announcements flagged around ibis or India, this appointment is the main new data point. It fits into Accor’s broader push to grow fee based earnings via Management & Franchise. Revenue already comes from both Premium, Midscale & Economy and Luxury & Lifestyle segments across multiple regions.
For you as a shareholder, the link between this hire and catalysts runs through operating metrics. Execution on guest experience, occupancy and pricing in India can support the pipeline thesis and loyalty economics. Any missteps would feed into existing risks around emerging market exposure, operator performance and already compressed reported profitability.
What The Current Accor Forecasts Assume
Accor's narrative projects €6.6 billion revenue and €687.9 million earnings by 2029. This lines up with analyst expectations of 5.4% yearly revenue growth and an earnings increase of about €302.9 million from €385.0 million today.
Uncover why Accor's fair value indicates an 18% potential upside to its current price before that discount to Accor closes.
Exploring Other Perspectives
One alternate view is all about India as a catalyst for Accor. The most optimistic analysts already pencilled in revenue of €7.1 billion and earnings of €863.5 million by 2029, compared with more cautious forecasts of €6.6 billion and €687.9 million. Those estimates were set before this appointment, so your own read on India could shift that story.
Explore 2 other Accor fair value estimates, including one that suggests as much as 73% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Accor research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Accor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Accor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Accor?
If Accor is only one piece of your watchlist, it can help to scan a broader set of businesses that match clear financial filters. The Simply Wall St Screener lets you move from a single stock story to a shortlist of companies that fit the balance of quality, value and resilience you are aiming for.
- If you want potential upside with strict risk controls on size and fundamentals, start with 129 elite penny stocks with strong financials that already clear financial quality checks.
- For investors who would rather focus on quality at a sensible entry point, filter for 193 high quality undervalued stocks where cash flows and balance sheets support a more disciplined approach to price.
- When capital preservation matters as much as return potential, tilt your search toward 233 resilient stocks with low risk scores that score well on stability and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com