


Recent gains in Marathon Petroleum (MPC) have been driven by a cluster of analyst upgrades and upbeat sector commentary that focus on stronger refining margins, resilient crack spreads, and sour crude processing advantages.
That analyst cheer has landed on a stock that already had strong momentum, with Marathon Petroleum’s share price up 16.08% over the past month and 52.57% over 90 days. Its 1-year total shareholder return of 167.67% and 5-year total shareholder return of about 7x suggest long-term buyers have been well rewarded, as recent gains build on an extended run rather than appear in isolation.
Scan for other refiners and energy plays showing similar momentum and analyst interest by running the same filter that surfaced Marathon Petroleum, along with the 33 high quality undervalued stocks in the sector.
Bulls see Marathon Petroleum as a sour crude and cash flow powerhouse that the market still discounts. Bears point to falling revenue and net income growth, plus a share price above many targets. Which story do the numbers lean toward next?
Most Popular Narrative: 10% Overvalued
Marathon Petroleum last closed at $476.92, while the most followed valuation narrative anchors fair value at about $433.44. The current price already reflects a lot of optimism about refining and midstream cash generation under present conditions.
The numbers suggest that a fairly valued, bearish view on Marathon Petroleum already reflects strong refining margins, substantial cash returns, and continued MPLX growth. This limits the potential upside for the share price if conditions simply remain where they are. Ongoing tight global refining capacity, with millions of barrels per day of capacity offline and fuel inventories around or below 5 year ranges, supports the idea that current refining margins and Marathon Petroleum earnings already reflect an enhanced mid cycle environment through at least 2027.
See why 67 investors see Marathon Petroleum as 10% overvalued.
Result: Fair Value of $433.44 (OVERVALUED)
Still, policy moves such as a potential U.S. diesel export restriction or tighter rules on foreign flagged vessels could quickly compress Marathon Petroleum margins and challenge today’s narrative.
Find out about the key risks to this Marathon Petroleum narrative.
Another View: Cash Flows Paint A Different Picture
The analyst narrative tags Marathon Petroleum as about 10% overvalued versus a $433.44 fair value anchored on earnings multiples. Our DCF model points in the opposite direction. On projected cash flows, it flags the $476.92 share price as trading at roughly a 23% discount to an estimated value of $620.82.
If earnings based metrics lean toward caution while cash flow math signals room above the current quote, which yardstick do you trust when the cycle eventually cools: the headline P/E or the long range cash generation?
Look into how the SWS DCF model arrives at its fair value.
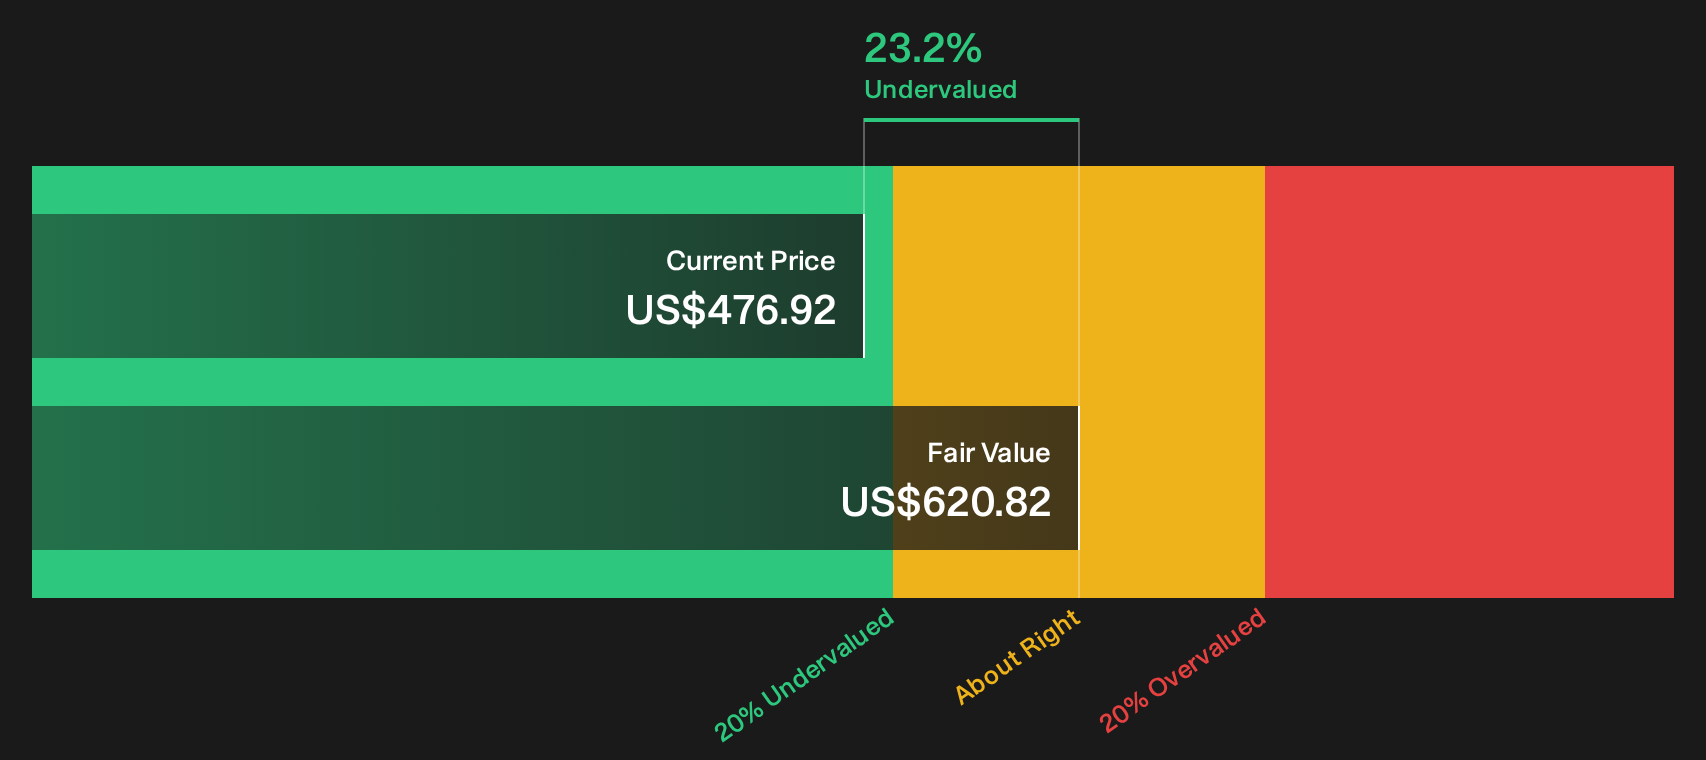
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Marathon Petroleum for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed narratives like this around Marathon Petroleum rarely stay balanced for long. Review the numbers, weigh the trade offs, and pressure test both the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond Marathon Petroleum?
If the split narratives around Marathon Petroleum have your attention, broaden your watchlist now before the next move in the sector passes you by.
- Target potential mispricings by scanning for companies that pair solid fundamentals with depressed valuations using the 33 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (25 results) so short term swings do not dictate your sleep.
- Get ahead of the crowd by hunting for 20 high quality undiscovered gems that already show quality metrics before they hit the mainstream radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com