


- Marsh & McLennan Companies reported Q3 2026 sales of US$6.86b and net income of US$808m, with adjusted EPS above analyst expectations. Results were supported by risk, insurance and consulting operations, as well as the Thrive efficiency program.
- The firm combined that earnings beat with active capital returns, repurchasing about US$500m of stock in Q3 and US$2.32b since late 2025, and raising its efficiency savings target to fund AI and technology investment.
- We will now look at how Marsh & McLennan Companies' earnings beat and higher efficiency savings target affect its broader investment narrative.
Compare Marsh & McLennan Companies’ Q3 beat and capital returns with peers by checking our curated list of 32 resilient stocks with low risk scores.
Marsh & McLennan Companies Investment Narrative Recap
Owning Marsh & McLennan Companies means believing that rising risk complexity, consulting demand and AI enabled efficiency can offset pressure from softer insurance and reinsurance pricing. The latest Q3 beat, with higher revenue and adjusted EPS, supports that view on execution. The raised Thrive savings target and AI reinvestment keep margin efficiency as the key short term catalyst, while reinsurance pricing and legal or conduct issues remain central threats to the story.
Q3 did not remove those risks, but it did show that cost discipline and demand for risk and consulting services are currently holding up despite those headwinds. In the near term, the main swing factor is whether Marsh & McLennan can keep extracting productivity gains fast enough to counter any drag from slower pricing or higher compliance costs.
The most relevant announcement here is the update on share repurchases. Marsh & McLennan bought back US$500m of stock in Q3 2026, bringing total repurchases under the current program to about US$2.32b and reducing the share count by roughly 2.73%. That sits alongside management’s broader plan to deploy around US$5.5b of capital across 2026.
For you as an investor, that capital return story links directly to the earnings catalyst. If the Thrive efficiency program and AI tools keep supporting cash generation, there is more room for buybacks and dividends to work alongside consulting and brokerage growth. The flip side is that any sustained pressure on pricing, litigation costs or debt servicing would make that capital plan harder to maintain without trade offs elsewhere in the business.
Marsh & McLennan Companies' current analyst narrative points to revenues of US$31.5b and earnings of US$5.4b by 2029, based on a projected 4.1% yearly revenue growth rate and an earnings increase of about US$1.4b from US$4.0b today.
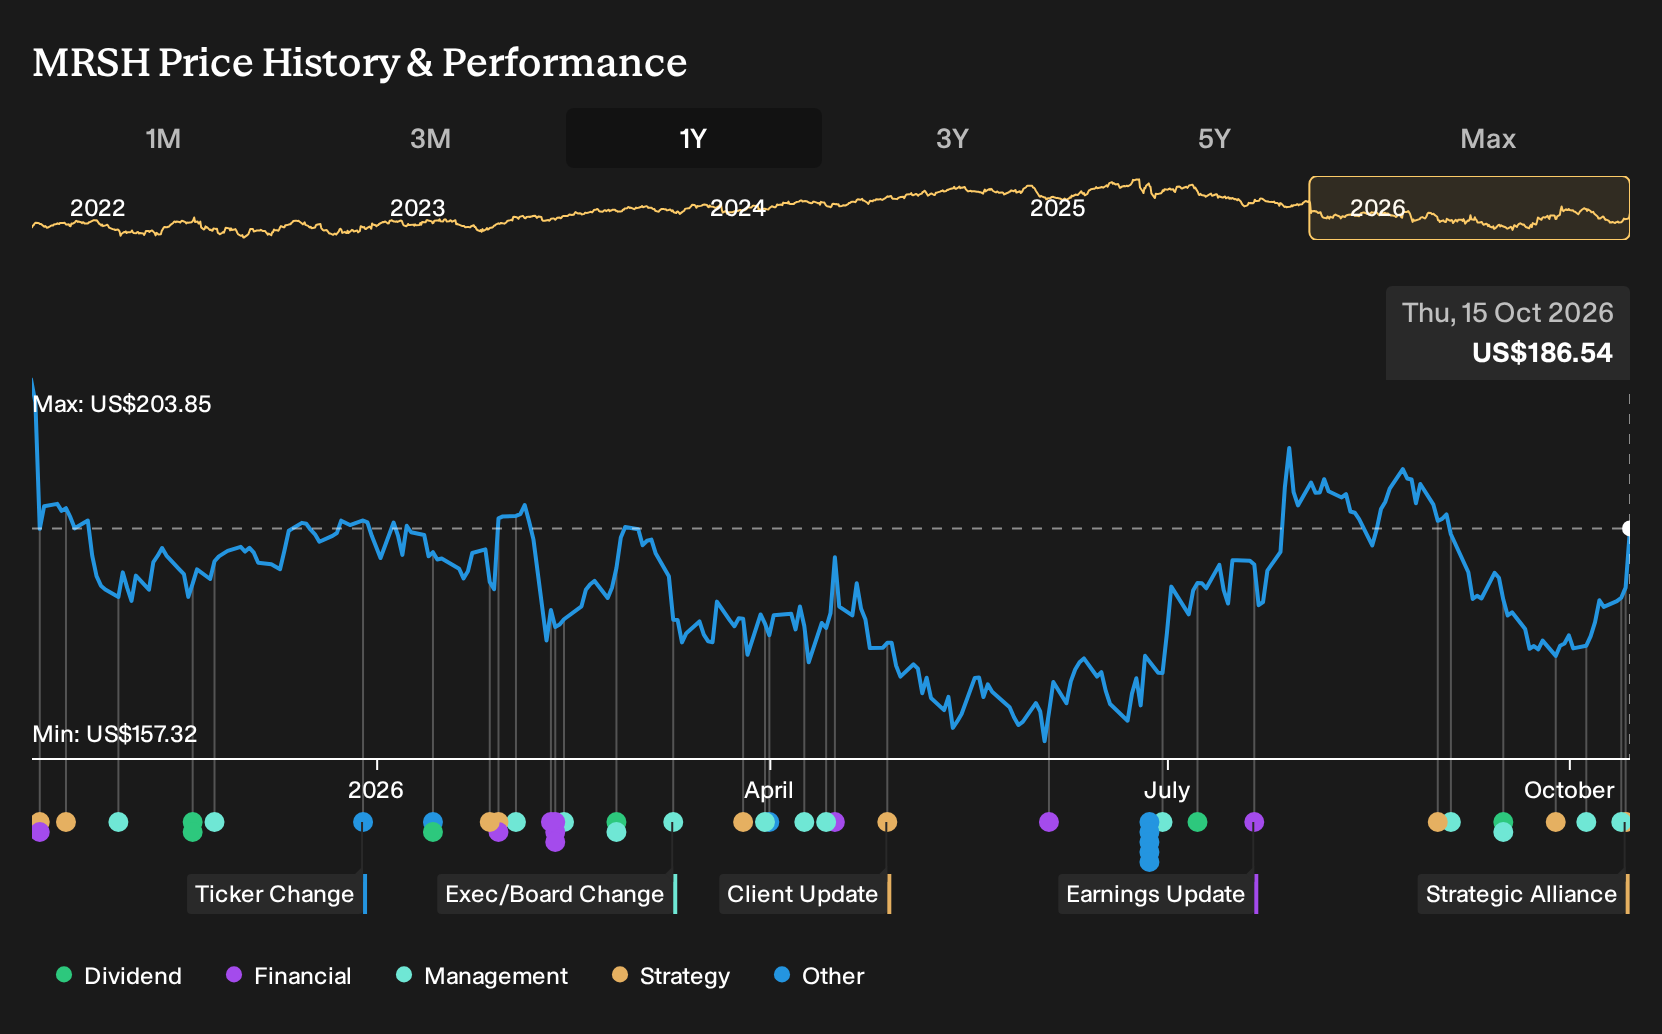
Uncover why Marsh & McLennan Companies' fair value indicates a 9% potential upside to its current price before that discount closes.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$203 to US$295, so you see both cautious and very optimistic takes on Marsh & McLennan Companies. When you set that against risks like softer reinsurance pricing and litigation exposure, plus AI and efficiency catalysts, it becomes clear that opinions differ widely and invite you to explore multiple viewpoints.
Explore 2 other Marsh & McLennan Companies fair value estimates, including one that suggests it could be worth just $202.90.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Marsh & McLennan Companies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marsh & McLennan Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marsh & McLennan Companies' overall financial health at a glance.
Looking For More Ideas Beyond Marsh & McLennan Companies?
If the Marsh & McLennan Companies story has sharpened your thinking about risk, cash flow and capital returns, you can broaden that lens by scanning a wider field of opportunities with the Simply Wall St screener.
- If you want resilience to be the anchor of your watchlist, you can start with a curated set of 32 resilient stocks with low risk scores that score well on stability and downside protection.
- For investors who care about both quality and entry price, consider focusing on companies in the 33 high quality undervalued stocks and see which ones line up with your own research framework.
- If you prefer strong balance sheets and solid fundamentals doing the heavy lifting, you might build a shortlist from the list of solid balance sheet and fundamentals (25 results) and stress test each candidate against your risk tolerance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com