


Even when a business is losing money, it's possible for shareholders to make money if they buy a good business at the right price. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
Given this risk, we thought we'd take a look at whether Valiant Gold (ASX:VAL) shareholders should be worried about its cash burn. For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
When Might Valiant Gold Run Out Of Money?
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. When Valiant Gold last reported its June 2026 balance sheet in September 2026, it had zero debt and cash worth AU$68m. Looking at the last year, the company burnt through AU$4.8m. So it had a very long cash runway of many years from June 2026. Even though this is but one measure of the company's cash burn, the thought of such a long cash runway warms our bellies in a comforting way. The image below shows how its cash balance has been changing over the last few years.
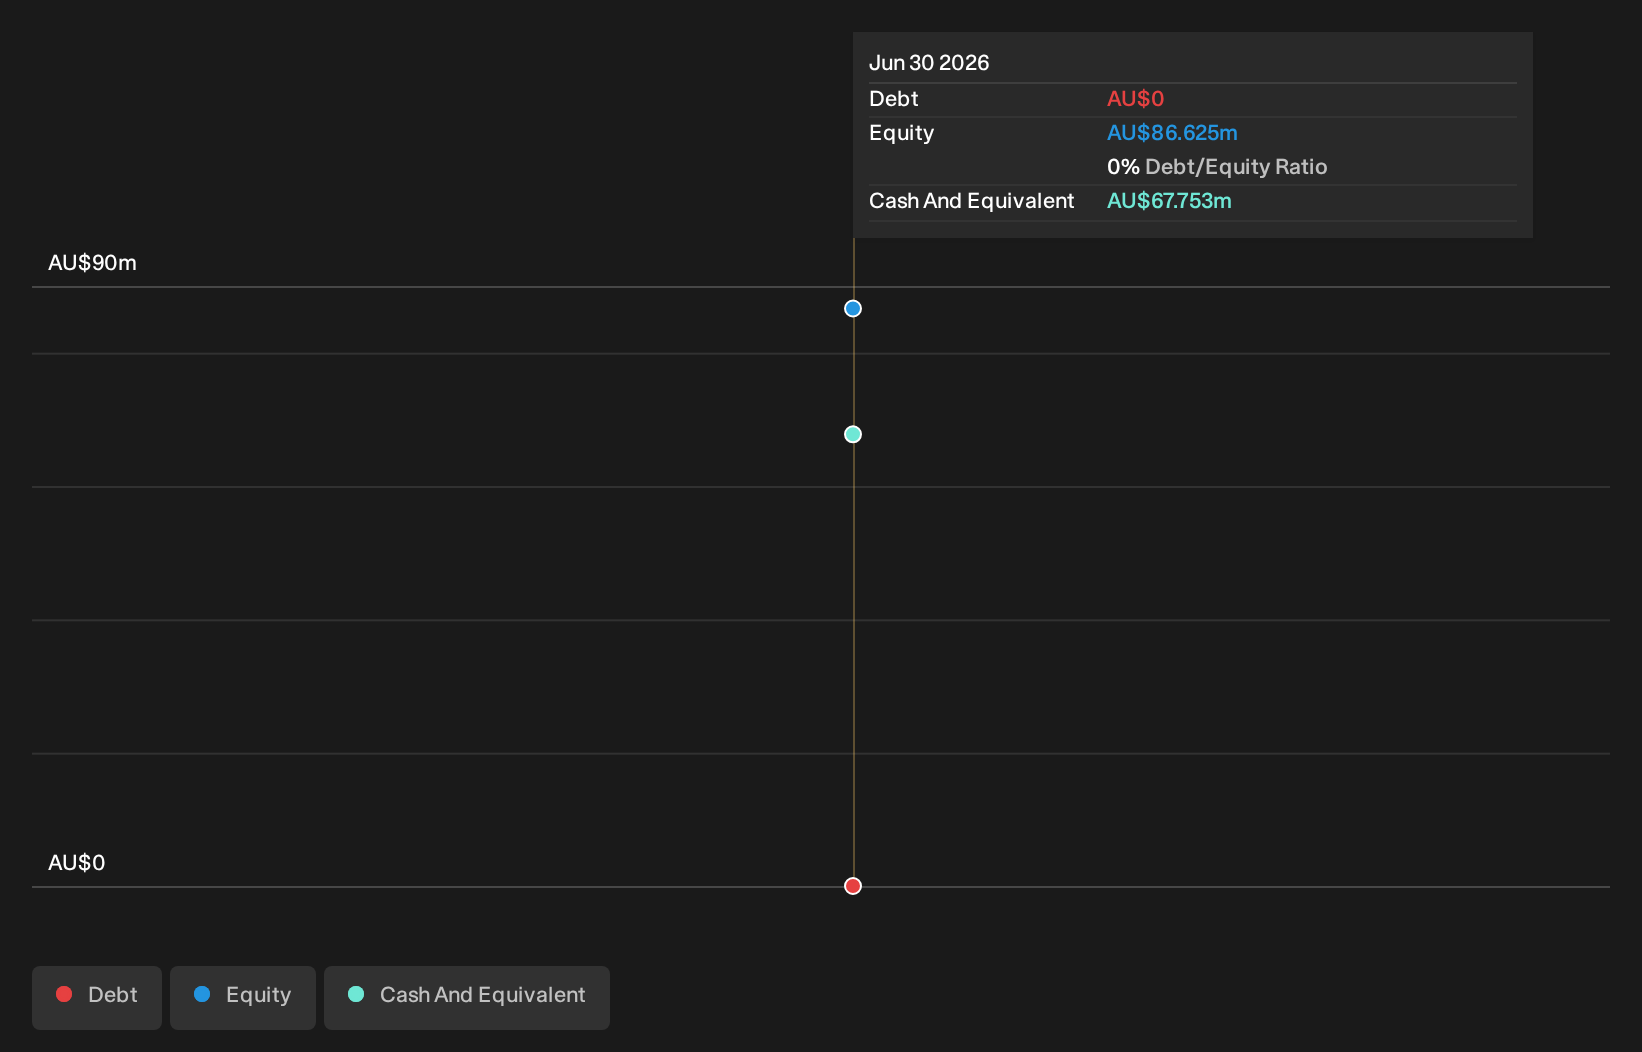
See our latest analysis for Valiant Gold
How Hard Would It Be For Valiant Gold To Raise More Cash For Growth?
Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Valiant Gold's cash burn of AU$4.8m is about 3.8% of its AU$124m market capitalisation. Given that is a rather small percentage, it would probably be really easy for the company to fund another year's growth by issuing some new shares to investors, or even by taking out a loan.
So, Should We Worry About Valiant Gold's Cash Burn?
Because Valiant Gold is an early stage company, we don't have a great deal of data on which to form an opinion of its cash burn. Certainly, we'd be more confident in the stock if it was generating operating revenue. Having said that, we can say that its cash runway was a real positive. Summing up, its cash burn doesn't bother us and we're excited to see what kind of growth it can achieve with its current cash hoard. On another note, we conducted an in-depth investigation of the company, and identified 3 warning signs for Valiant Gold (1 can't be ignored!) that you should be aware of before investing here.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.