


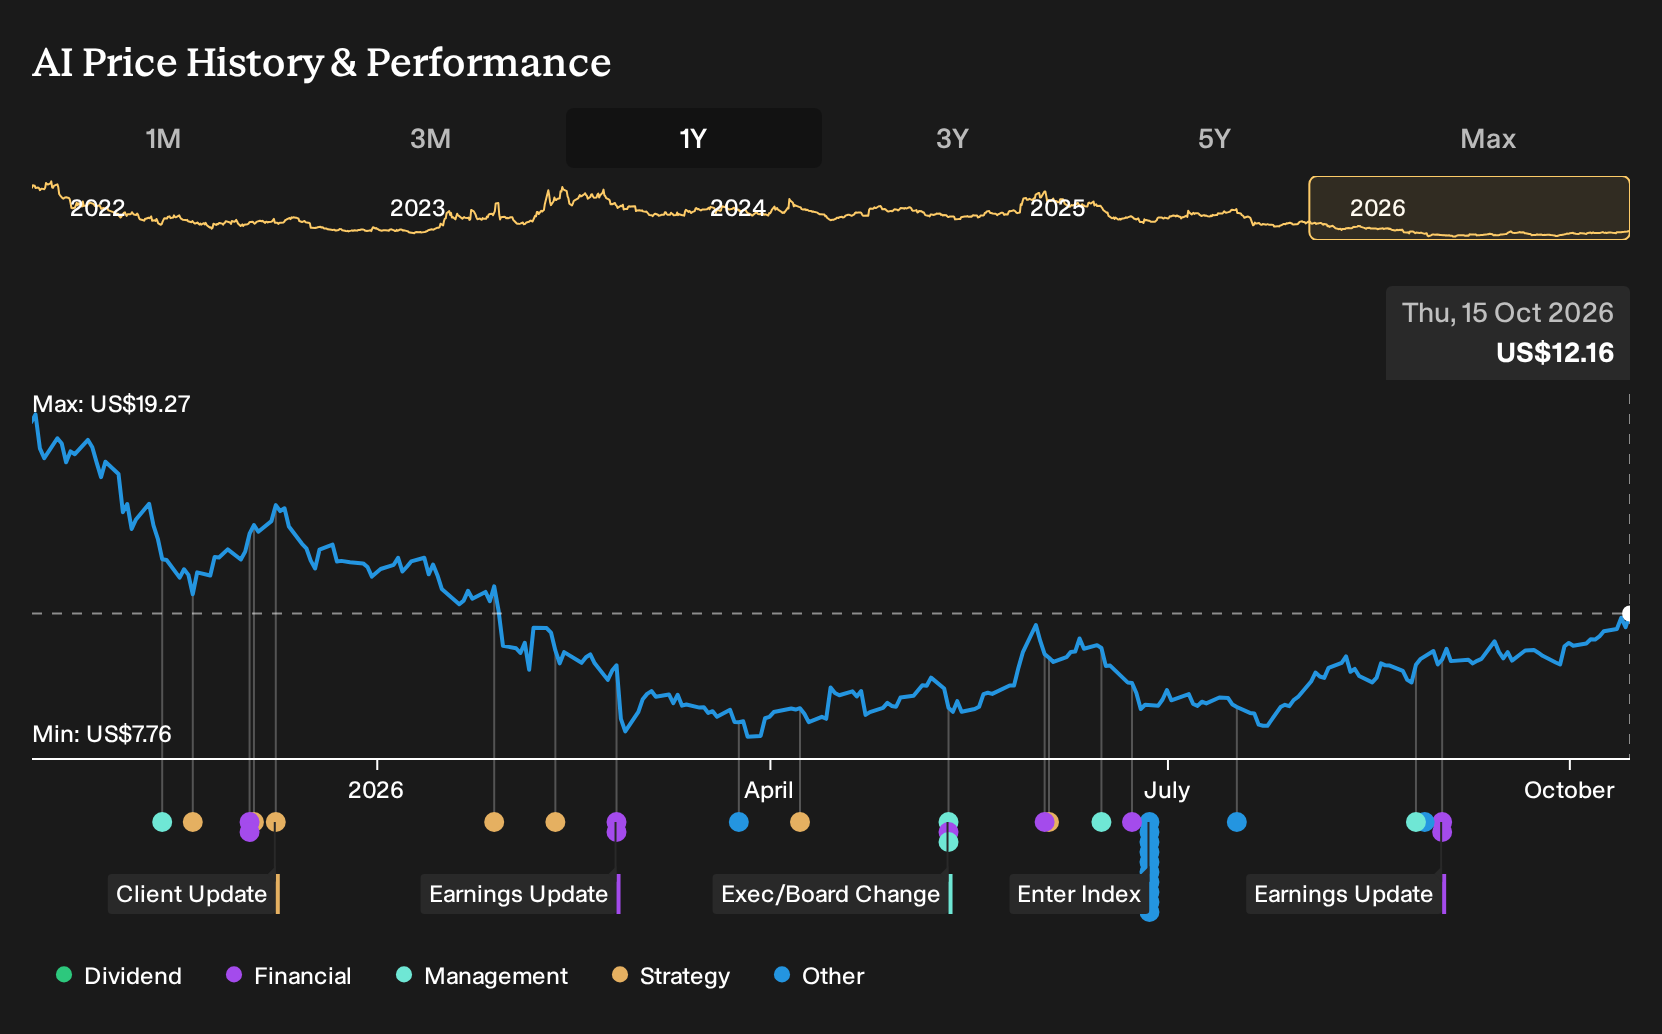
If you had simply glanced at C3.ai’s headlines, the story might have sounded oddly encouraging. Holding C3.ai over the past year would have meant a 32.7% loss, including dividends. That drop landed even as the latest quarter showed revenue lower but the loss per share slightly narrower, and investors briefly cheered. If you were deciding on 15 October 2025, what signals about shrinking revenue and deep losses were already in plain sight?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
C3.ai has already moved. Pinpoint other ways to investigate the theme among 38 AI small caps.
The Two C3.ai Stories Investors Had To Weigh
The shares cost US$19.27 at the start, and C3.ai sat between two very different stories about what might come next.
On the optimistic side, the bullish view put Fair Value at US$25, which is 30% above the start price. That narrative leaned on revenue growing 21.7% a year and profit margin climbing from a deep loss to 12.7% within about three years.
The more cautious case set Fair Value at US$14.67, which is 24% below the start price. That scenario assumed revenue would shrink 2.7% a year while still requiring a 12.4% profit margin and a 73.6x future P/E to work.
What The Evidence Around C3.ai Actually Tested
C3.ai’s later filings showed pressure where the bullish story needed relief. Revenue fell from US$70.3m in Q1 2026 to US$52.4m in Q1 2027, and the firm still reported a loss, with net margin moving from a 166.2% loss to a 177.2% loss. That combination cut against the optimistic path to profitability and supported the cautious case.
The hinge assumption was not hype about AI, but C3.ai’s ability to turn partnership talk into improving margins. For any other stock, it may be useful to track whether revenue trends and net margin actually move together in reported numbers before paying up for a profitability story.
What C3.ai’s Lower Price Already Assumes
C3.ai now trades at US$12.16. The selected Narrative places its Fair Value below that level and frames today’s quote as already baking in successful execution on cost cuts, federal and enterprise uptake, and a path to profitability despite recent revenue pressure.
The key risk to examine is whether buyers today assume recent agreements and internal AI tools reliably convert into recurring, profitable revenue, or whether the lower price already fully reflects the chance they do not.
"This points to a risk that rising AI budgets do not translate into sufficient contract volume to cover operating costs and could keep revenue growth and operating margins well below what is implied in current expectations."
The price and this Narrative do not agree. → Uncover what this Narrative says C3.ai is actually worth
Looking One Step Beyond C3.ai
C3.ai pushes the AI story right to the edge of applications. Your attention naturally goes to the headline software promises first.
Step back one layer and a different requirement appears. All that AI activity still needs reliable cloud plumbing underneath it.
Another giant focuses on that foundation. It sells the computing backbone, developer tools and business software that let clients run and refine intensive AI work.
You see the same buyers, but a different problem being solved. The open question is how much value gathers around that quieter, infrastructure heavy task.
That argument has a Narrative and a number behind it. → See the company one Narrative values 24% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com