


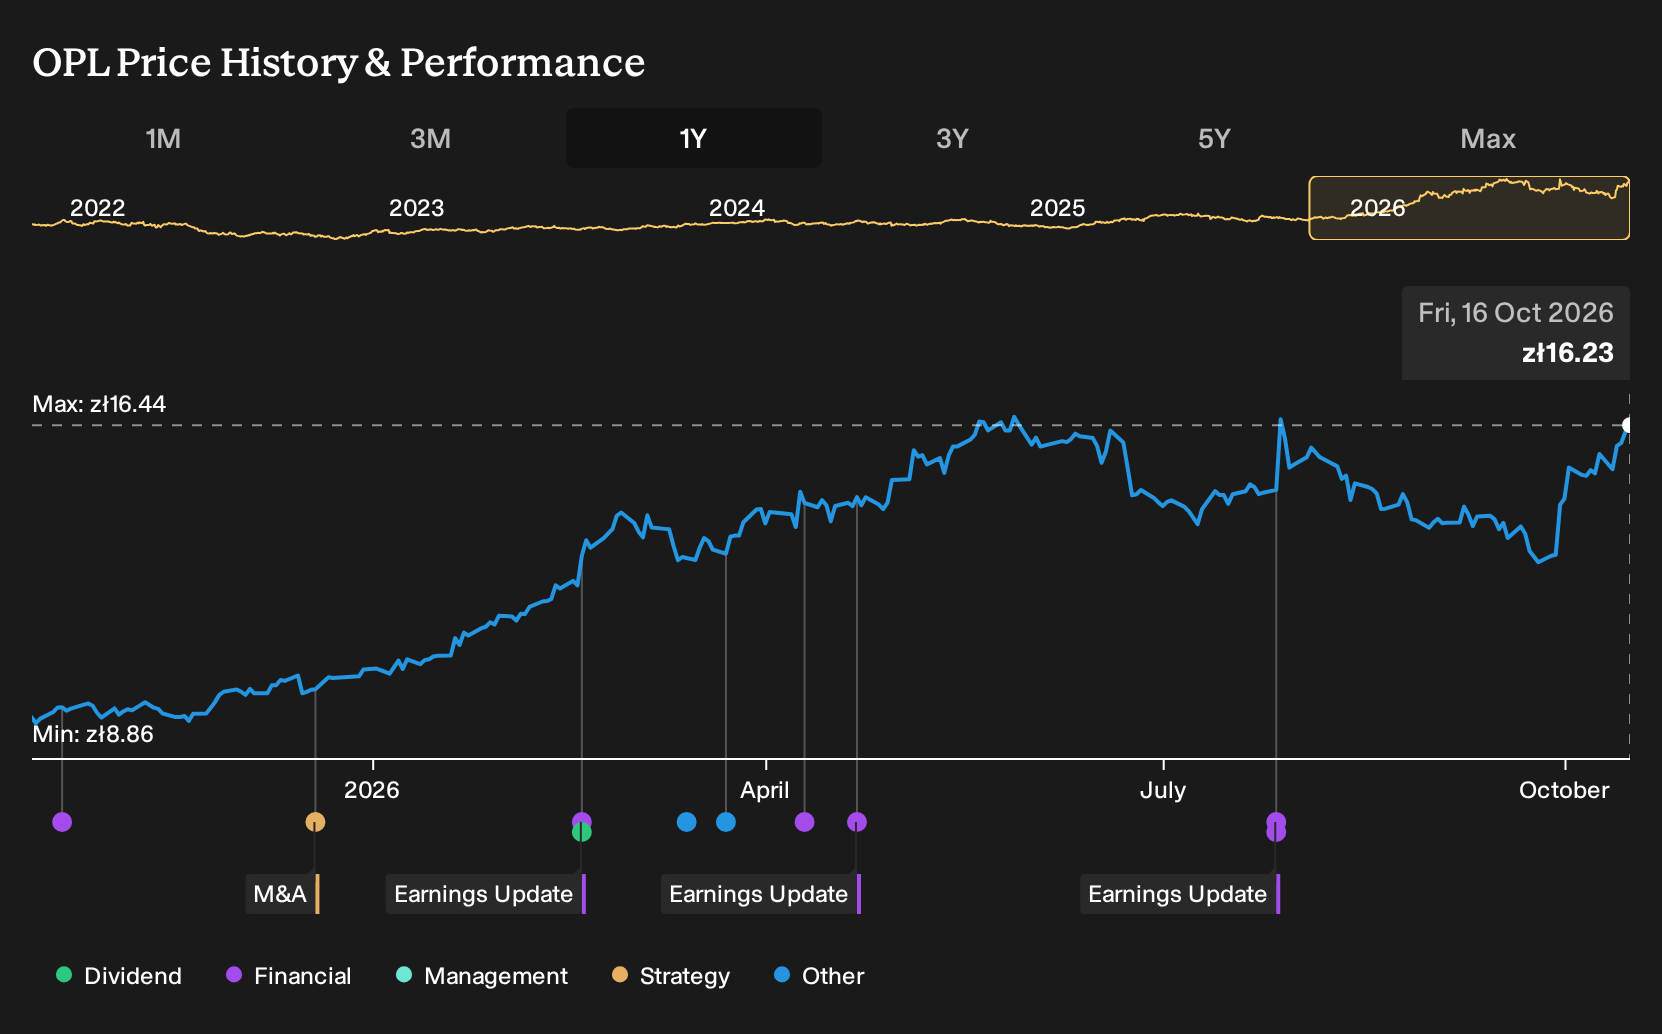
Orange Polska spent the year pushing fiber deeper into rural areas and widening 5G coverage, while its Q2 2026 report showed revenue of PLN 3,500m and net income of PLN 281m with a lower net margin. For Orange Polska shareholders, the return over the past year was 88.1%, including dividends. If you had been weighing a purchase back in October 2025, what exactly would you have needed to believe about these projects and their payoff?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Orange Polska has already moved. See which of 193 high quality undervalued stocks still trade below our estimates.
The Argument Orange Polska Investors Were Weighing Up
The shares cost PLN8.86 at the start of the period, and anyone looking at Orange Polska then had to choose between two very different but reasonable stories.
On the bullish side, a Fair Value of PLN10.8 rested on the idea that rapid fiber and 5G rollout, plus new ICT and cybersecurity services, would support recurring earnings as higher margin digital lines grew.
The bearish Narrative pointed to a Fair Value of PLN6.1 and focused on demographic headwinds, shrinking legacy voice and SMS income, and heavy capital spending that could keep free cash flow under pressure.
What The Orange Polska Results Actually Tested
The cleanest datapoint for Orange Polska investors was the Q2 2026 report. Revenue reached PLN 3,500m against PLN 3,158m a year earlier, which backed the bullish focus on a broader customer base and heavier network use. Net income nudged up from PLN 274m to PLN 281m, while the net margin slipped from 8.7% to 8.0%. The evidence cut both ways.
The single assumption this period really leaned on was whether fibre and 5G spending would thicken profitability. When you look at another telecom, test that same claim by pairing revenue with the reported net margin, not just the top line on its own.
What Orange Polska's Current Price Already Bakes In
Orange Polska now trades at PLN16.23, with this Narrative’s Fair Value set below that level. The argument is not that the business is broken. It is that recent execution, upgraded guidance and cash generation already carry a full price tag.
A buyer today is effectively assuming core telecom, IT and wholesale performance can support recurring EBITDAaL and organic cash flow once project driven and real estate supports fade. The selected Narrative asks how resilient that cash engine looks if large contracts, infrastructure deals and disposals become less frequent.
"Even though Orange Polska plans to reach at least PLN 1.2b in organic cash flow in 2026 helped by gains on real estate disposals and large deals, management acknowledges that real estate proceeds will diminish over the coming years and that repeating the current year’s EBITDA growth would need new sizable big contracts. As these one off supports fade, free cash flow and dividend capacity could fall short of what investors might infer from the latest cash flow guidance."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond Orange Polska
Orange Polska points you to one question. What happens where terrestrial towers still cannot reach?
Some telecom partners are turning to space based cellular coverage. The idea is simple. Let a standard smartphone connect directly to satellites when ground networks stop.
This other business is building that orbital layer and managing its spectrum. It aims to plug coverage gaps for mobile users and government customers.
If that model scales, tower based operators like Orange Polska would not be the only way your phone stays online far from the nearest mast.
One Narrative has already put a figure on it. → Uncover the company trading 62% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com