


Cardinal Health (CAH) is back in focus after management reaffirmed its multi year non GAAP EPS guidance and outlined a binding agreement to extend its CVS Health distribution deal through 2032.
Recent trading has leaned in Cardinal Health's favor, with a 7 day share price return of 6.94% and a 30 day share price move of 9.25% helping lift the stock to US$254.06. That short term momentum sits on top of an 11.18% 90 day share price gain and a 23.50% year to date share price return. Longer term investors have seen a 1 year total shareholder return of 63.97% and a 5 year total shareholder return of about 4.7x. This suggests recent optimism around earnings guidance and the extended CVS agreement is building rather than fading.
Scan how Cardinal Health compares to other defensive healthcare stocks showing strong recent momentum in our hand picked list of 32 resilient stocks with low risk scores.
After a move like this, the real tension for Cardinal Health investors is simple: lean into the momentum now, or wait and risk watching any pullback never quite arrive as the valuation case gets tested next.
Most Popular Narrative: 6% Undervalued
Cardinal Health's most followed narrative pegs fair value at $270.94, which sits modestly above the latest close at $254.06 and presents the current enthusiasm as a valuation gap story rather than just a momentum trade.
The expansion of specialty pharma distribution, multi specialty MSO platforms in areas like oncology, urology and gastroenterology, and a rapidly scaling Biopharma Solutions business that is ahead of its prior growth plan points to a larger mix of higher value services that can influence segment profit and overall earnings. Faster growth in higher margin service businesses such as Nuclear and Precision Health, OptiFreight logistics and at-Home Solutions, with revenue and profit guidance above prior long term targets, indicates a structural mix shift that can support operating margin and earnings growth.
See why 52 investors see Cardinal Health as 6% undervalued.
Result: Fair Value of $270.94 (UNDERVALUED)
Still, quality control issues such as the levothyroxine recalls and pressure on Global Medical Products and Distribution input costs could quickly challenge the current Cardinal Health narrative.
Find out about the key risks to this Cardinal Health narrative.
Another View: Cardinal Health On Earnings Multiples
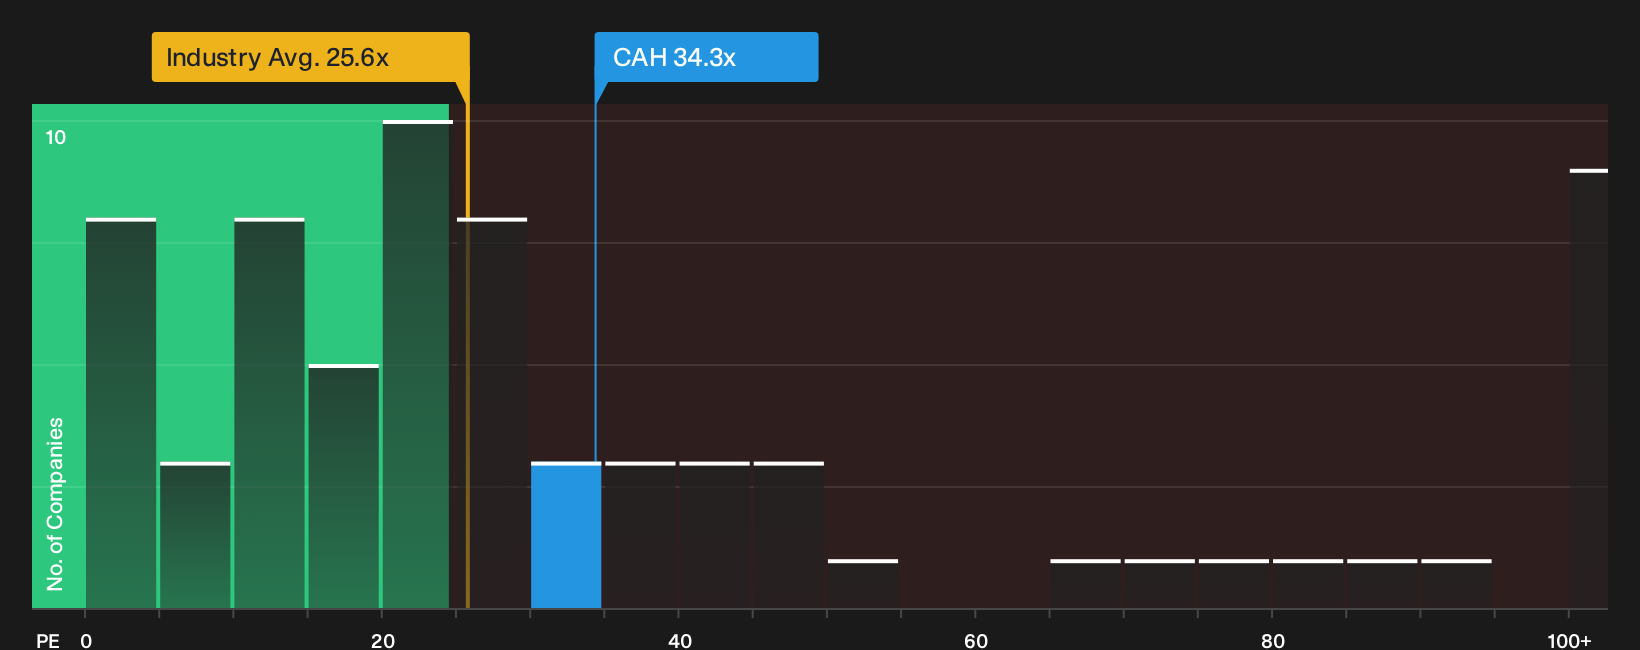
That fair value of $270.94 paints Cardinal Health as undervalued, yet the current P/E of 34.3x tells a different story. The ratio sits above both the peer average of 28.7x and a fair ratio of 31.5x, which points to valuation risk if expectations cool.
For investors who prefer to anchor decisions on earnings multiples and relative pricing, this kind of premium can feel either like justified enthusiasm or a thin margin of safety. The question is simple: Which side of that tradeoff are you really betting on when you buy into CAH at today’s level?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on Cardinal Health after this latest move are normal. Review the figures, assess the trade off between the good and the bad, and then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cardinal Health?
If Cardinal Health has you thinking more broadly about your portfolio, use this momentum to scout fresh opportunities that match your goals and risk comfort.
- Target quality at a discount by scanning a focused set of 33 high quality undervalued stocks that combine solid fundamentals with prices that trail intrinsic estimates.
- Build a steadier income stream by reviewing 7 dividend fortresses that pair higher yields with balance sheets that can support ongoing payouts.
- Strengthen your downside protection by filtering for a list of solid balance sheet and fundamentals (25 results) that can better handle stress without constant refinancing questions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com