


European Green Transition has renewed its five year maintenance contract with Drax Group (LSE:DRX), covering 94 turbines and extending contracted revenue visibility to 2031. That longer runway gives investors fresh context for assessing the utility's renewable focus.
Drax Group’s latest contract renewal comes after a mixed year in the market, with the share price at £7.85. The year-to-date share price return is down 7.1%, while the 1-year total shareholder return is 14.62% and the 3-year total shareholder return is 114.92%. Momentum has cooled recently, even though longer term holders have still seen strong gains overall.
Scan other renewables and utilities with similar contracted revenue visibility and long-term agreements using our hand-picked 41 power grid technology and infrastructure stocks as a comparison set to Drax Group.
Drax Group now offers a longer line of contracted cash flows, but the share price has cooled in recent months. Is that a chance to buy on a quieter tape, or a reason to wait for an even cheaper entry?
Most Popular Narrative: 14% Undervalued
Drax Group's most followed valuation narrative points to a fair value of £9.17, which sits above the latest £7.85 close and frames the current pullback as a discount to that estimate.
The recent agreement on a government-backed low-carbon dispatchable CfD for Drax Power Station (covering all units through 2031) significantly increases long-term revenue visibility and reduces earnings volatility, supporting stable EBITDA and predictable cash flows well into the next decade.
The accelerating energy transition, marked by ongoing global decarbonization mandates, retirement of coal and nuclear baseload plants, and rising electricity demand, directly expands the market need for reliable, flexible renewable generators like Drax; this positions the company to capture outsized market share and drive top-line growth.
See why 31 investors see Drax Group as 14% undervalued.
Result: Fair Value of £9.17 (UNDERVALUED)
Still, Drax Group faces pressure if biomass subsidies tighten or pellet markets stay oversupplied, which could squeeze segment margins and weaken the perception of undervaluation.
Find out about the key risks to this Drax Group narrative.
Another View On Drax Group’s Valuation
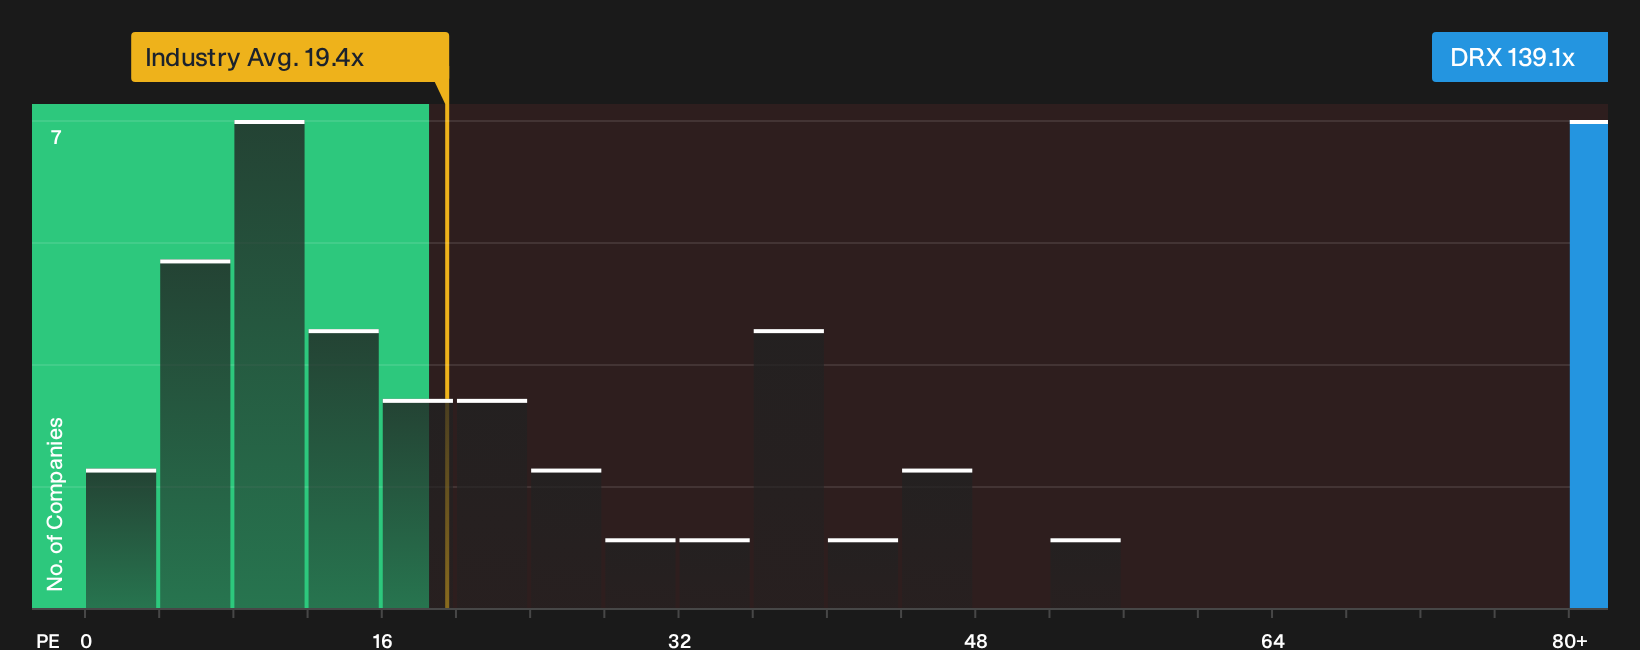
The first narrative leans on future earnings power and discounted cash flows to argue Drax Group looks undervalued around £7.85. A simple P/E check tells a very different story. The stock trades on about 139x earnings, compared with 19.4x for the European renewable energy industry and 15.3x for peers, while the fair ratio is 17x. That gap points to meaningful valuation risk if sentiment cools and the market pushes the multiple closer to the fair ratio instead of the DCF outcome.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Drax Group's valuation and risk profile make this a judgment call. Review the data promptly and carefully weigh the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Drax Group?
If Drax Group has sharpened your focus on valuations and risk, broaden your watchlist with fresh ideas that match different return and resilience goals.
- Target potential mispricing and hunt for quality opportunities trading at attractive valuations through our focused 7 high quality undervalued stocks.
- Prioritise resilience and aim for fewer unpleasant surprises by scanning companies with 4 resilient stocks with low risk scores.
- Spot lesser-known opportunities with solid fundamentals by reviewing 5 high quality undiscovered gems before they gain wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com