


Valeura Energy (TSX:VLE) has released new operating data, reporting third quarter 2026 oil production of 22.1 mbbls/d and quarterly oil sales of 2.013 million barrels.
Valeura Energy’s latest production update lands after a powerful run in the shares, with the stock posting a 30 day share price return of 11.81% and a year to date share price gain of 108.28%, while the 1 year total shareholder return of 162.87% signals strong momentum that has built over multiple years.
Scan beyond Valeura Energy and see how other oil and gas producers with strong momentum and operating updates compare using our hand picked 36 elite gold producer stocks
For Valeura Energy, the surge following its production and sales update could signal improving conviction in the underlying business, or it could reflect a sentiment swing chasing momentum. Which story do the current valuation markers suggest you are paying for?
Most Popular Narrative: 12% Undervalued
On the most followed narrative, Valeura Energy screens as undervalued, with a fair value of CA$19.10 against a last close of CA$16.85. This raises the question of what assumptions are doing the heavy lifting.
The Wassana Field redevelopment, expected to reach FID in early Q2 2025, could significantly increase the 2P reserves and double production upon completion, enhancing revenue and cash flow in the coming years. Operational efficiencies have lowered OpEx, coming in at $22.8 per barrel in Q4, and capitalized on cost-effectiveness in drilling activities. This efficiency is expected to improve net margins by reducing production costs further.
See why 14 investors see Valeura Energy as 12% undervalued.
Result: Fair Value of CA$19.10 (UNDERVALUED)
Still, delays or cost overruns at the Wassana redevelopment, or regulatory setbacks around Thai and Turkish projects, could quickly challenge the current valuation story for Valeura Energy.
Find out about the key risks to this Valeura Energy narrative.
Another View: What Valeura Energy’s Earnings Multiple Is Telling You
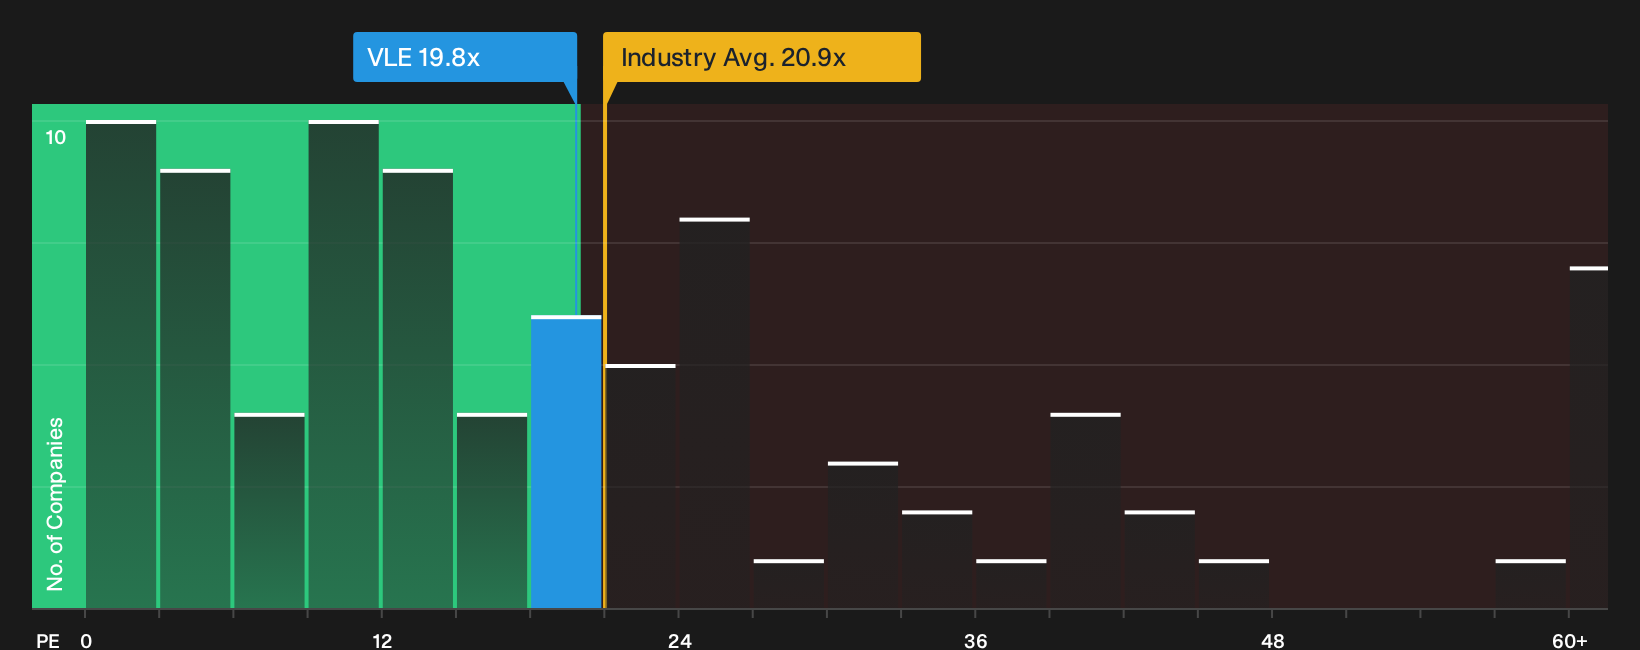
Price to earnings sends a different message to the CA$19.10 fair value story. Valeura Energy trades on a P/E of 19.8x, which is lower than the Canadian oil and gas group at 21.1x and below peers at 27.8x, yet well above a fair ratio of 8.8x that our model suggests the market could gravitate toward over time.
So even if the consensus target and SWS fair value point to upside, that gap between 19.8x and an 8.8x fair ratio hints at meaningful rerating risk if sentiment or earnings expectations reset. The key question is which side of that trade you are really comfortable owning.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The sentiment from Valeura Energy’s recent move is mixed enough that it pays to look under the hood yourself rather than just watch the chart. To weigh the balance of concerns against the upside arguments, start with the 1 key reward and 2 important warning signs
Looking for more investment ideas beyond Valeura Energy?
If Valeura Energy has sharpened your focus, do not stop here. Broader idea flow can make a real difference to how you position your portfolio.
- Push for mispriced quality by scanning a curated 5 high quality undervalued stocks that filters for fundamentals the market may be overlooking.
- Lock in potential income streams by reviewing a hand picked 3 dividend fortresses that concentrates on higher yielding payers with resilience in mind.
- Protect the downside first by checking a targeted 8 resilient stocks with low risk scores designed to surface businesses with sturdier risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com