


- Sarepta Therapeutics reported new preclinical results for SRP-1003, an investigational siRNA for myotonic dystrophy type 1, showing up to about 80% reduction of pathogenic DMPK RNA in both nuclear and cytoplasmic compartments using several independent measurement techniques.
- The data suggest SRP-1003 is engaging its target directly in the nucleus, where DM1 pathology originates. This could be important for how Sarepta Therapeutics positions its broader siRNA platform alongside the existing Duchenne muscular dystrophy portfolio.
- We will now look at how Sarepta Therapeutics broader investment narrative could be shaped by SRP-1003’s nuclear DMPK knockdown data.
Sarepta Therapeutics Investment Narrative Recap
To own Sarepta Therapeutics, an investor needs to believe the Duchenne muscular dystrophy franchise can keep throwing off cash while the siRNA and gene therapy pipeline gradually matures. The SRP-1003 nuclear knockdown data adds scientific depth to that story, but the near term operational focus still leans heavily on ELEVIDYS uptake and exon skipping durability.
The most important short term swing factor remains how efficiently ELEVIDYS moves patients from enrollment to infusion under tighter safety scrutiny. The biggest risk is that safety concerns, capacity bottlenecks or complex reimbursement processes slow infusions, which could strain cash generation just as Sarepta Therapeutics funds high cost R&D.
The SRP-1003 update sits alongside earlier progress in the siRNA program, including SRP-1001 in FSHD, where single ascending dose data showed over 90% correction on DUX4 regulated gene panels with a favorable safety profile. Together, these programs frame siRNA as a second pillar next to Duchenne, supported by Q2 2026 non GAAP operating income of US$86 million.
For catalysts, investors are watching the ongoing Phase 1/2 SRP-1003-101 trial and the expected multiple ascending dose data in late 2026 and early 2027, since successful execution could gradually diversify Sarepta Therapeutics beyond Duchenne. The key operational question is whether the current cash flow positive Duchenne base can comfortably support these trials while managing ELEVIDYS risk controls.
What The Sarepta Therapeutics Consensus Is Pricing In
Sarepta Therapeutics' narrative projects US$1.3b revenue and US$36.4 million earnings by 2029. This assumes revenue declines at about 13.0% per year and implies an earnings swing of roughly US$173 million from a loss of US$136.7 million today.
Uncover why Sarepta Therapeutics' fair value indicates a 27% potential upside to its current price, which could close faster than many investors expect.
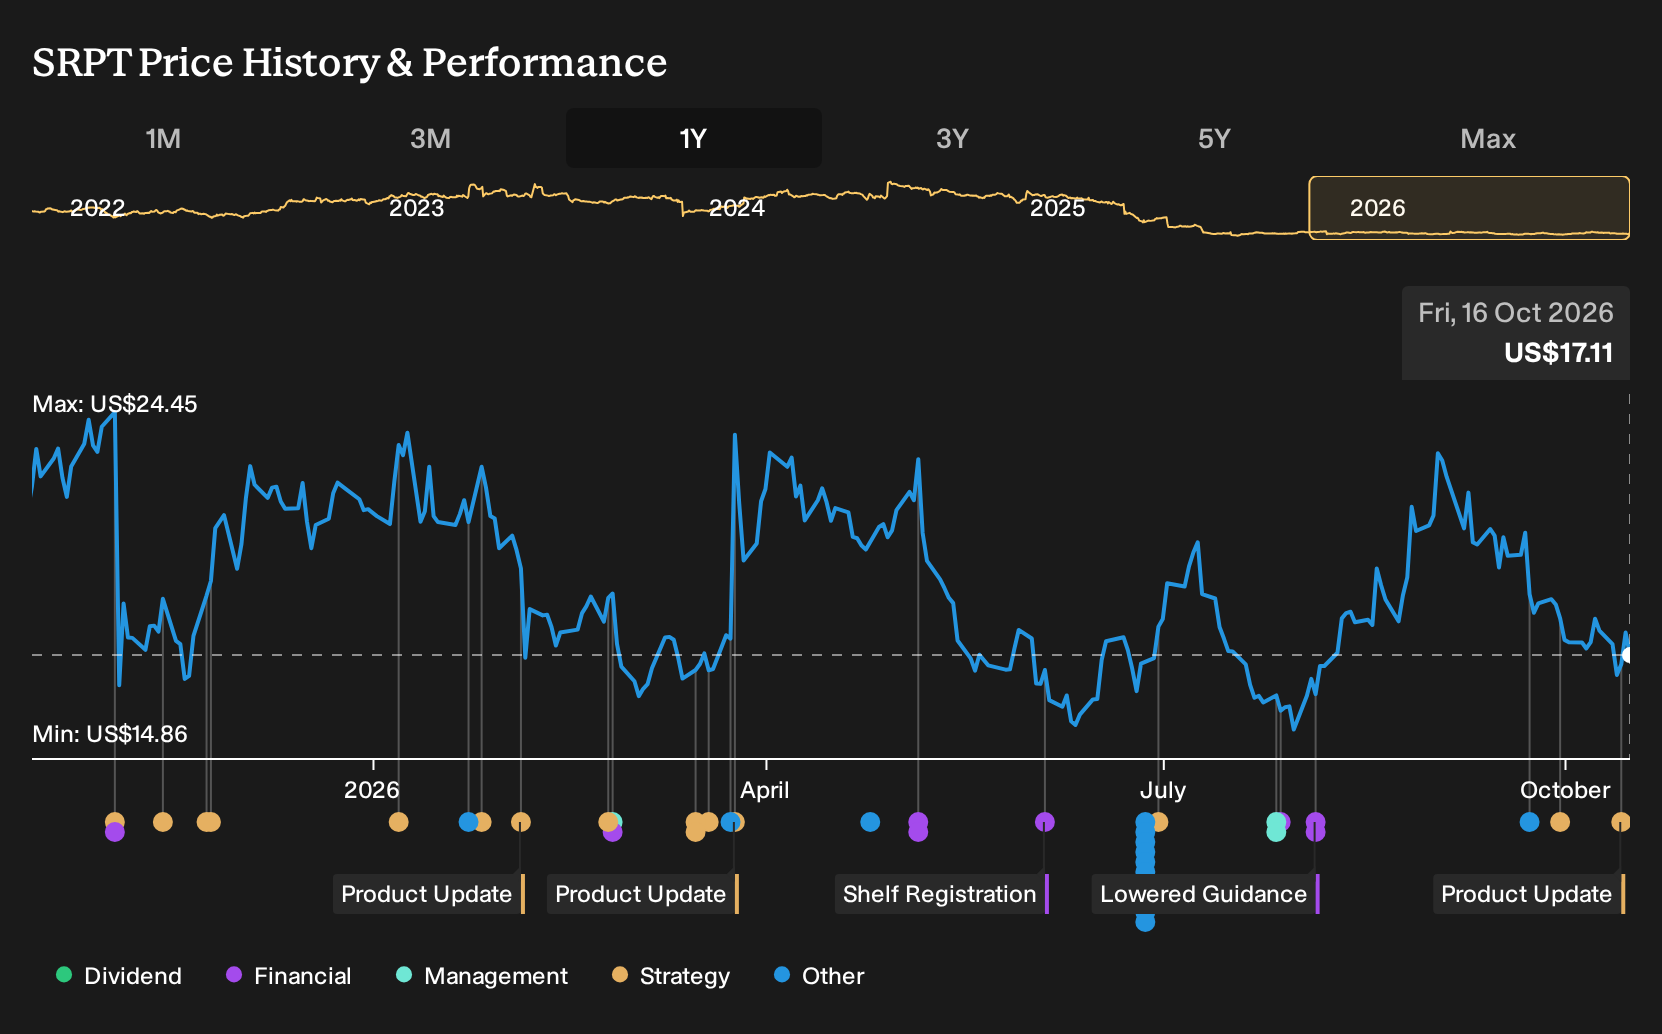
Exploring Other Perspectives
For Sarepta Therapeutics, the bullish twist in the story has been ELEVIDYS acting as a cash engine rather than a drag. The most optimistic analysts were already modeling about US$1.4b of revenue and US$159.6 million of earnings by 2029 before this SRP-1003 news, which could nudge those views even further if nuclear knockdown data reshapes expectations. You can treat this new information as a prompt to compare those upbeat assumptions with more cautious forecasts and decide which camp feels closer to your own view.
Explore 3 other Sarepta Therapeutics fair value estimates, including one that suggests as much as 992% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sarepta Therapeutics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sarepta Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sarepta Therapeutics' overall financial health at a glance.
Looking For More Sarepta Therapeutics Style Ideas?
If Sarepta Therapeutics has sharpened your interest in complex healthcare stories, it can help to widen the lens and compare it with other listed companies that share similar financial or risk profiles. The Simply Wall St Screener lets you move from a single ticker to a watchlist built around the traits you care about most, whether that is balance sheet strength, income potential, or overlooked quality.
- For investors who want potential value with quality fundamentals, start with a curated set of 33 high quality undervalued stocks that may warrant a closer look.
- If resilience matters more than excitement, focus on 32 resilient stocks with low risk scores that score well on stability metrics and downside protection filters.
- For those hunting beyond the usual watchlists, scan 20 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com