


- Pomerantz LLP is reviewing potential securities law violations at Cellebrite DI after annual recurring revenue and full year guidance came in below prior company commentary, alongside the sudden CEO replacement reported in August 2026.
- The combination of weaker recurring revenue trends and abrupt leadership change raises fresh questions about Cellebrite DI’s execution consistency and disclosure quality at a time when its subscription model is central to the business story.
- We will examine how Cellebrite DI’s investment narrative is pressured by the lowered guidance and what this means for its recurring revenue focus.
Balance the Cellebrite DI headline risk by scanning a curated group of 32 resilient stocks with low risk scores that may offer steadier execution and cleaner disclosure profiles.
Cellebrite DI Investment Narrative Recap
For a shareholder, the main belief in Cellebrite DI is that demand for digital investigation tools and a high share of subscription revenue can support a durable recurring cash engine. The miss on annual recurring revenue and the cut to full year guidance put that near-term thesis under pressure. The clearest short-term catalyst now is evidence that subscription momentum can stabilize despite slower US federal spending.
The biggest risk sits in execution. Softer ARR, a new CEO and management turnover magnify concerns around delivery on large government contracts and product investment. If procurement delays, privacy regulation or rapid security changes have a greater impact, investors may focus less on long-term opportunity and more on contract timing and cost discipline.
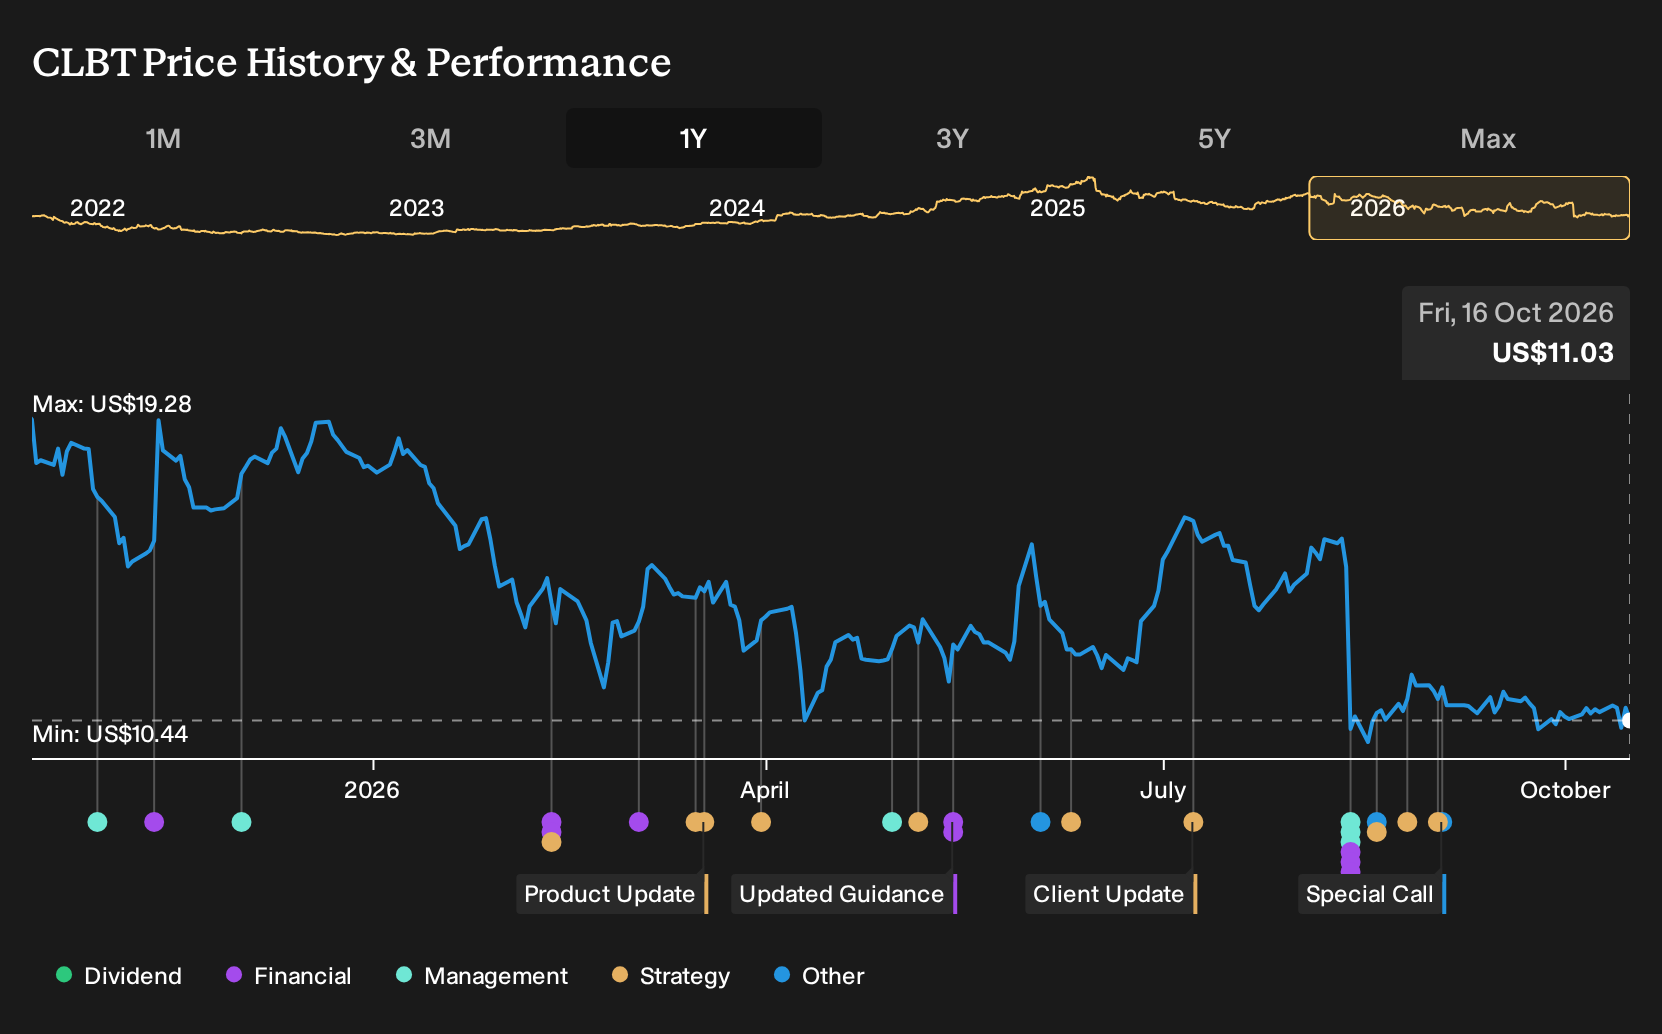
The August 13, 2026 update is the key event to focus on. Cellebrite DI reported ARR below prior commentary, reduced its outlook for the year, and announced the abrupt replacement of former CEO Tom Hogan. That disclosure coincided with a sharp share price drop and effectively reset expectations around growth visibility and leadership stability.
Viewed through the existing catalysts, that announcement directly challenges confidence in near-term ARR expansion, particularly where US federal contracts are involved. It also raises the bar for the new leadership team to demonstrate consistent execution on AI-driven products, international expansion and Corellium integration while managing risks from regulation, competition and a relatively high P/E multiple.
Cellebrite DI's current analyst narrative points to forecast revenue of $787.4 million and projected earnings of $122.0 million by 2029, implying forecast revenue growth of 15.3% per year and an earnings increase of about 2.1x from $58.2 million today.
Uncover why Cellebrite DI's fair value indicates a 39% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternative angle on Cellebrite DI focuses on the risk that tighter privacy rules cap the long term market. The lowest analysts were already cautious, even while assuming revenue of about $797.0 million and earnings of $129.2 million by 2029. Those estimates came before this August guidance reset, so opinions may change.
Explore 2 other Cellebrite DI fair value estimates, including one that suggests it could be worth just $14.31!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cellebrite DI research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cellebrite DI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cellebrite DI's overall financial health at a glance.
Looking For More Ideas Beyond Cellebrite DI?
If the Cellebrite DI story leaves you wanting a broader watchlist, the Simply Wall St Screener can help you line up other businesses with profiles that better match your risk and income preferences.
- For investors who are comfortable with higher risk in pursuit of potential upside, you can review a curated set of smaller companies by checking out 14 elite penny stocks with strong financials.
- If capital preservation and financial resilience matter most to you right now, you can start with a list of solid balance sheet and fundamentals (25 results) that have historically kept debt and liquidity in tighter check.
- For those who care about both quality and price, you can scan a 33 high quality undervalued stocks that currently combine stronger fundamentals with more modest valuation multiples.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com