


Opendoor Technologies (OPEN) is back in focus as investors weigh fresh profit concerns in a high interest rate housing market and examine the newly launched 2% down Opendoor Own co ownership program.
Recent trading tells a rougher story. At a latest share price of US$2.12, Opendoor Technologies has seen its 30 day share price return fall 18.34%, with the 90 day share price return down 53% and the 1 year total shareholder return declining 70.46%.
Spot potential alternatives to Opendoor Technologies' risk profile by scanning a curated group of housing and real estate peers screened as 32 resilient stocks with low risk scores.After a 70% one year hit and fresh profit worries tied to Opendoor Own, the question is blunt: Does it make more sense to step in now or wait for a cheaper shot at Opendoor Technologies before the numbers do the talking?
Most Popular Narrative: 51% Undervalued
On the most followed view, Opendoor Technologies screens as undervalued, with a fair value estimate of about $4.27 against a last close of $2.12, which leaves a wide gap that only closes if you buy into the growth and margin story set out in that narrative.
Opendoor is optimizing its contribution margin by setting spreads according to macro indicators, which could improve net margins by reducing risks and maintaining healthy unit economics.
Enhancements in pricing models and a refined customer experience could lead to higher conversion rates, potentially increasing revenue as more sellers convert their initial engagement into completed transactions.
See why 77 investors see Opendoor Technologies as 50% undervalued.
Result: Fair Value of $4.27 (UNDERVALUED)
Still, the whole Opendoor Technologies story can crack if housing demand stays soft, and high inventory days or heavy asset backed debt pressure margins harder than expected.
Find out about the key risks to this Opendoor Technologies narrative.
Another View On Opendoor Technologies' Value
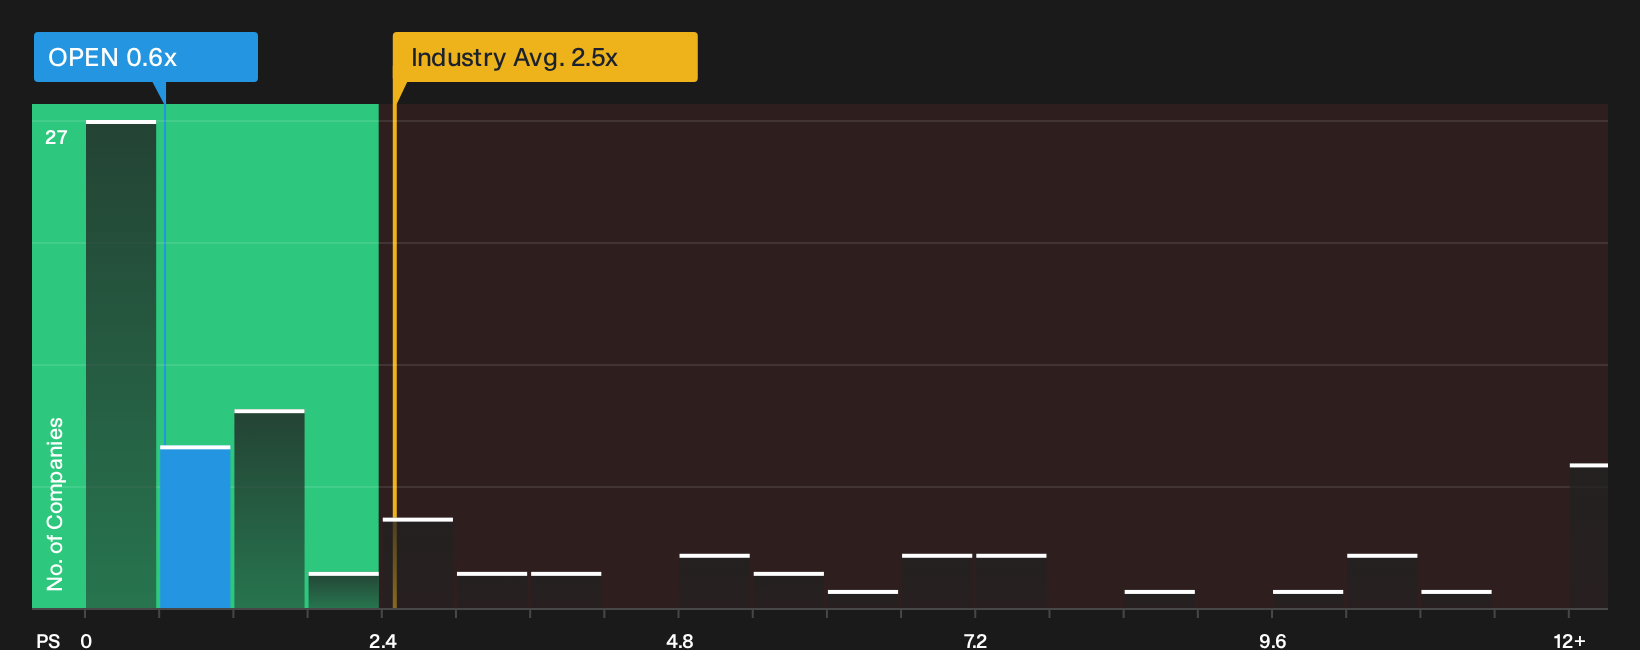
The earlier narrative leans on analyst targets and growth assumptions to argue Opendoor Technologies looks undervalued around $2.12. A different lens tells a cooler story. On a P/S ratio of 0.6x, the stock looks roughly in line with peers at 0.6x, yet far cheaper than the broader US Real Estate group at 2.5x, which suggests sector level risk and company specific issues may both be at play.
That same 0.6x valuation also matches the fair ratio estimate of 0.6x. This implies the market is already pricing Opendoor Technologies close to where regression models indicate its sales multiple could settle, even while the SWS DCF model points to a large discount to future cash flow value. Which lens do you trust more when a stock screens cheap on growth, but not especially cheap on its current sales line?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Opendoor Technologies is split, which is exactly when doing your own homework matters most. If you want a quick snapshot of both sides of the story before you decide where you stand, tap into the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Opendoor Technologies?
If Opendoor Technologies has caught your attention, do not stop here. Broaden your watchlist now, because the most interesting opportunities rarely sit in plain sight.
- Target resilient balance sheets and steadier cash flows by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for strong businesses that may be mispriced by the market with the 20 high quality undiscovered gems.
- Zero in on companies that combine income potential with staying power by using the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com