


- TGS, in joint venture with SLB, recently announced the Pelotas Sul Phase 2 multi client 3D seismic survey in Brazil, and SLB also secured a global agreement with TotalEnergies to deploy its DrillPlan well planning solutions.
- The combination of a large frontier basin seismic project and a broad digital rollout with TotalEnergies highlights how SLB is connecting software driven workflows to future exploration and development decisions.
- The focus now turns to how SLB's global DrillPlan rollout could interact with its existing investment narrative around digital expansion.
Scan how SLB's latest seismic and digital moves compare with peers by zeroing in on a hand picked group of offshore and energy service players in the 41 power grid technology and infrastructure stocks
SLB Investment Narrative Recap
To own SLB, you need to believe the mix shift toward digital, production-focused services and data center solutions can turn relatively modest top line growth into higher quality, more recurring cash flows. The main near-term swing factor still sits with execution on these higher-margin areas while earnings have been weaker recently and Q3 expectations look cautious.
The biggest business risk remains disruption to large international and long-cycle work, along with any shortfall in scaling data center and digital targets. The new Brazil seismic survey and DrillPlan rollout look incremental rather than transformational for the next few quarters, so they do not materially change that near-term setup.
The global DrillPlan agreement with TotalEnergies is the announcement to watch around SLB right now. It ties directly into the firm’s push to grow its Digital & Integration division, which generated US$2.82b of revenue in the latest full year, and to build a larger base of software-like and recurring-style income.
For you as a shareholder, the operational question is simple. Can SLB roll DrillPlan out smoothly across TotalEnergies’ portfolio, keep integrating it with subsurface data and then reuse that model with other operators? Any stumble in deployment, customer adoption or ongoing updates would feed directly into the key catalyst and digital growth story.
SLB's current analyst narrative points to revenues of US$43.0b and earnings of US$5.5b by 2029, based on assumed annual revenue growth of 5.7% and an earnings uplift of about US$2.4b from US$3.1b today.
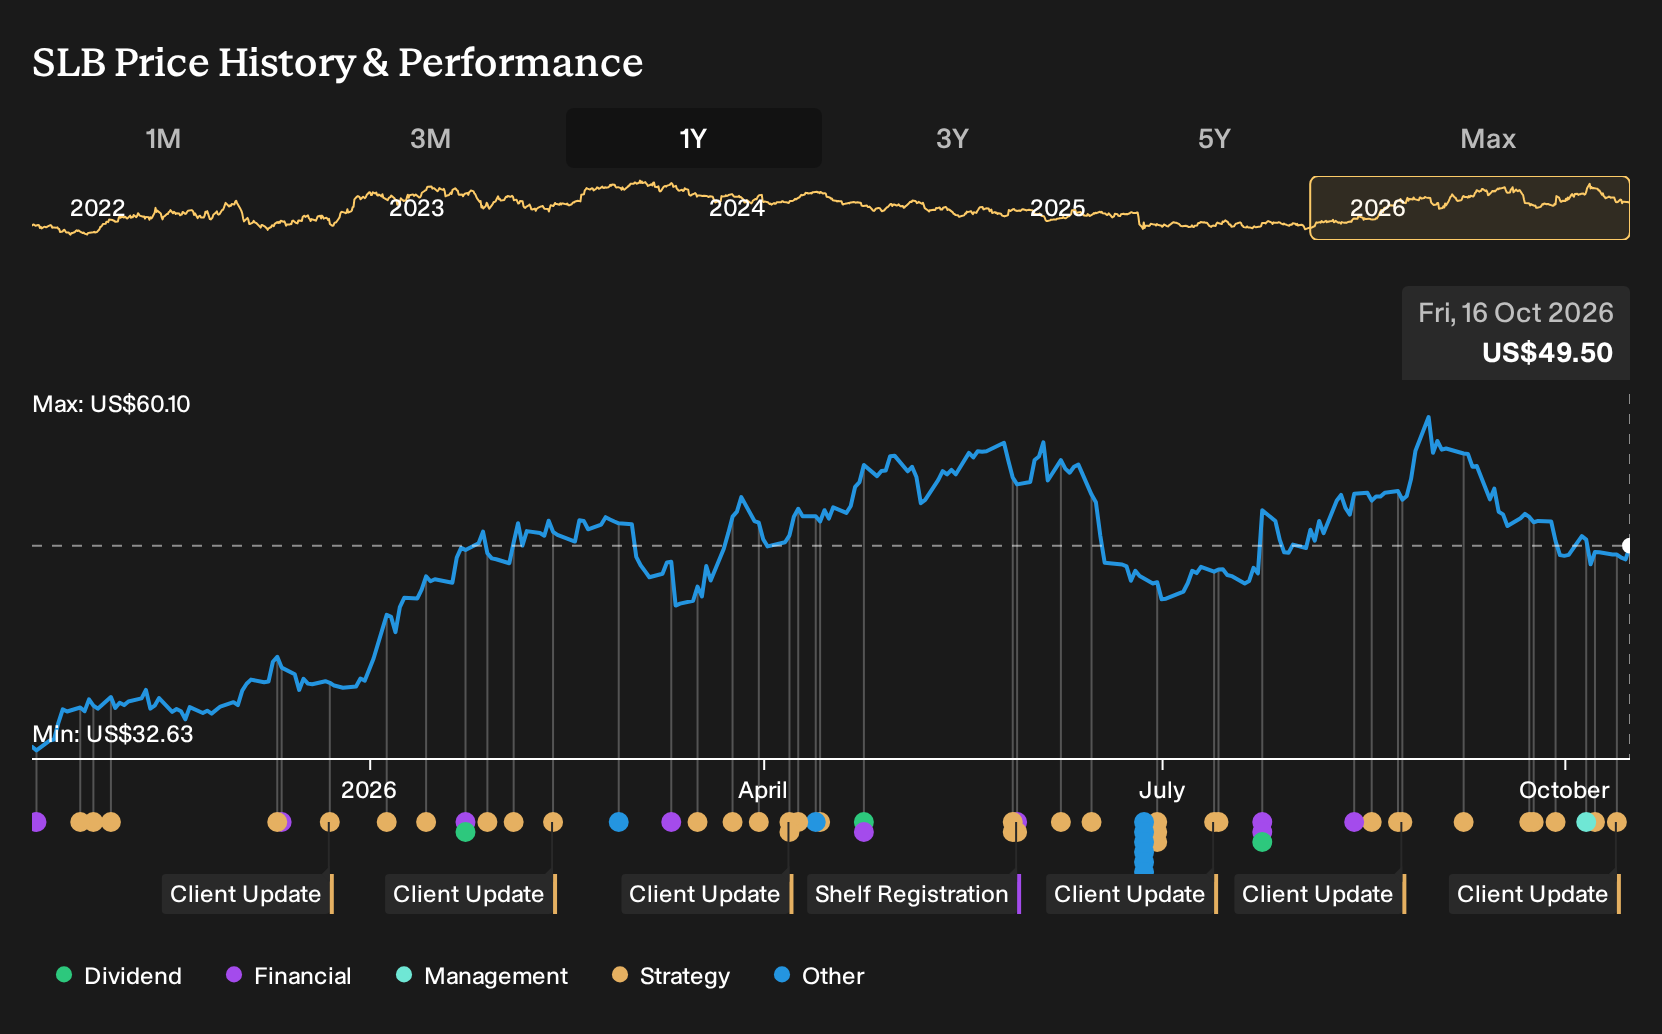
Explore why SLB's fair value reflects a 26% potential upside to its current price before other investors narrow that gap.
Exploring Other Perspectives
For a different angle on SLB, focus on the bullish view that large offshore work and AI rich data center projects could push earnings toward the US$6.4b that the highest analysts were expecting by 2029, compared with the US$5.5b consensus. Those forecasts were set before this Brazil seismic and DrillPlan news, so expectations may shift from here.
Explore 5 other SLB fair value estimates, including one that suggests as much as 71% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SLB research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SLB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SLB's overall financial health at a glance.
Looking for more SLB style investment ideas?
If the SLB story has you thinking about how to round out your watchlist, it can help to line it up against other opportunities with different risk and income profiles.
- For investors who want potential upside with less focus on size, scan a curated group of smaller, higher risk tickers in the 14 elite penny stocks with strong financials.
- If quality and valuation sit at the top of your checklist, filter for businesses combining stronger fundamentals with attractive pricing through the 33 high quality undervalued stocks.
- When balance sheet strength and resilience matter most to you, narrow the field to companies screened for sturdier finances in the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com