


- BlueNord reported preliminary September 2026 output of 43.9 mboepd net, with 25.2 mboepd from the Tyra hub and 18.7 mboepd from the Dan, Gorm and Halfdan hubs, and said planned pigging on the Harald Tyra pipeline was completed while quarterly production stayed within 25 to 30 mboepd guidance.
- The update highlights that Tyra hub production recovered quickly from temporary operational events, and this suggests current operating processes may be containing short term disruptions and helping BlueNord keep output aligned with its stated quarterly targets.
- We will now assess how BlueNord's investment narrative could be influenced by stable quarterly output despite Tyra related operational interruptions.
Scan how BlueNord's steady production profile compares with oil and gas peers by reviewing our hand-picked list of solid balance sheet and fundamentals (203 results) that may better handle operational bumps like these.
BlueNord Investment Narrative Recap
To own BlueNord, you need to be comfortable with a gas weighted producer where the Tyra hub and Danish base assets underpin the story. The key short term belief is that operations can stay broadly on plan while Tyra moves through its ramp phase and the business funds its heavy obligations and dividends without stretching the balance sheet.
The September production update looks operationally reassuring. Output held inside guidance despite pigging work on the Harald Tyra pipeline and a few short term issues. That kind of delivery supports the near term production catalyst. It does not remove the main risk, which is that any longer or deeper interruption at Tyra could still hurt cash flow and debt servicing capacity.
With no fresh corporate disclosures beyond the September production statement, the most relevant reference point is still the existing framework around Tyra, hedged gas exposure and the plan to return 50% to 70% of operating cash flow to shareholders. The latest numbers sit inside that framework because they show the Danish hubs producing in line with the current operational script.
For a holder, the link is simple. Stable production at Tyra and the base assets supports the cash generation that BlueNord needs for interest payments, dividends and any refinancing. The risk side is that dividend coverage and debt service are already flagged as tight, so any future operational issue of a different scale than September would matter far more than this relatively contained month.
BlueNord's narrative projects US$1.2 billion in revenue and US$135.8 million in earnings by 2028. This assumes 13.3% yearly revenue growth and an earnings swing of about US$163.5 million, from a loss of US$27.7 million today to the 2028 consensus level.
Explore how BlueNord's fair value indicates a 7% potential downside to its current price, suggesting that this premium may not be sustained.
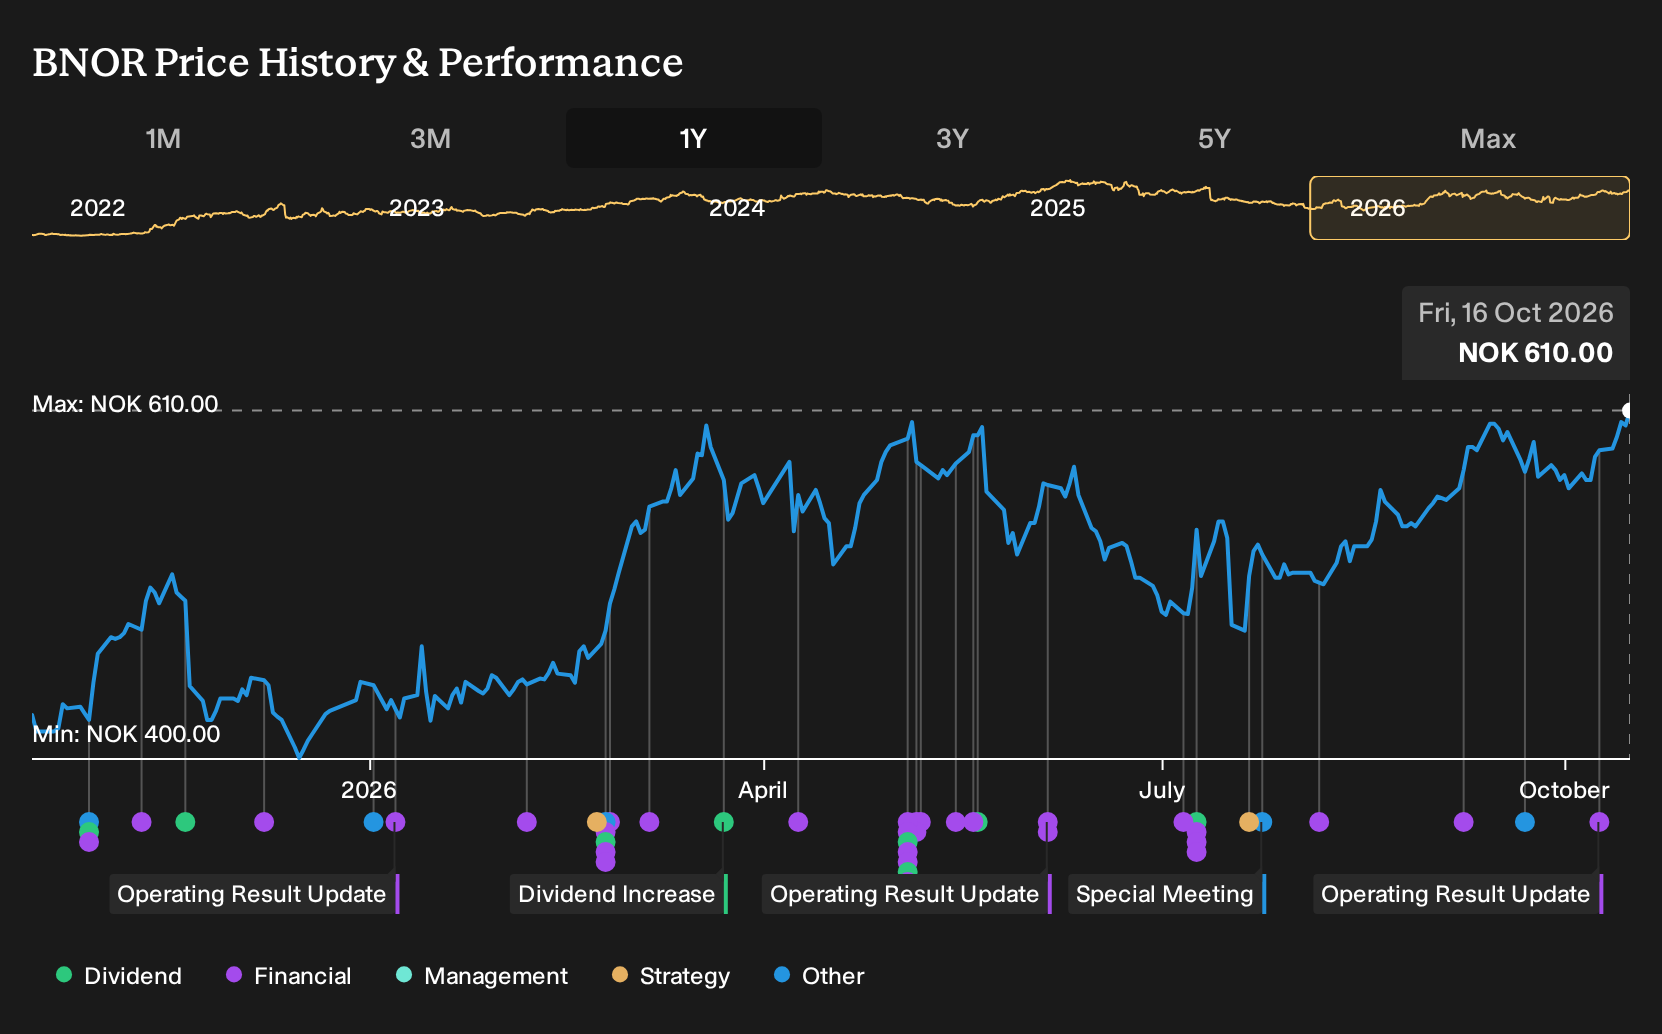
Exploring Other Perspectives
Some of the most optimistic analysts frame the key swing factor very differently. You might worry about Tyra interruptions. They focus instead on the possibility of smoother uptime that keeps volumes higher for longer. Before this update, the bullish camp was already pencilling in about US$1.3b of revenue and US$224.5 million of earnings by 2028. Those views were set before the September production news, so you may want to compare this latest stability signal with both the upbeat and more cautious forecasts and decide which story feels closer to your own read on BlueNord.
Explore 2 other BlueNord fair value estimates, including one that suggests as much as 160% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on thorough research.
- A great starting point for your BlueNord research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BlueNord. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BlueNord's overall financial health at a glance.
Looking For More Investment Ideas Beyond BlueNord?
If BlueNord is just one position in your watchlist, it can help to set it alongside other candidates that match different risk and income profiles.
- If you want potential torque in a smaller position size, scan a curated group of 131 elite penny stocks with strong financials that pair higher volatility with stronger balance sheets than many micro caps.
- If value is your anchor, review our 191 high quality undervalued stocks that blend solid fundamentals with pricing that screens as conservative on our models.
- If capital preservation comes first, consider a 233 resilient stocks with low risk scores that filters for sturdier finances and fewer red flags on core risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com