


Why Restaurant Brands International Limited Partnership is on investors’ radar
Restaurant Brands International Limited Partnership (TSX:QSP.UN) has drawn fresh attention after recent trading left the units with an indicated intrinsic discount of about 34%, based on the latest available internal valuation input.
Recent trading has been brisk rather than explosive for Restaurant Brands International Limited Partnership, with a 1-day share price return of 4.29% at CA$105.67 and a 7-day share price return of 2.14%. This has contributed to a 14.16% year to date share price gain, while the 3 year and 5 year total shareholder returns of 30.06% and 65.96% point to momentum that has been building over a longer horizon despite the current implied valuation discount.
Scan other potential opportunities with similar momentum and valuation gaps by reviewing the hand picked 5 high quality undervalued stocks that sit alongside Restaurant Brands International Limited Partnership in the market today.
Restaurant Brands International Limited Partnership runs some of the best known quick service banners on the planet. After this latest move and a roughly one third implied discount, the question is whether that quality actually comes at a bargain today.
Price-to-Earnings of 13.8x: Is it justified?
On a simple snapshot, Restaurant Brands International Limited Partnership trades on a P/E of 13.8x, which prices its CA$105.67 units above its direct peer group but below the broader North American Hospitality pack.
The P/E ratio compares the current unit price with earnings per unit and gives a quick read on how much investors are willing to pay for each dollar of profit. For a franchised quick service group with multiple banners and an asset light model, this kind of earnings based yardstick is often a primary reference point because cash profitability and fee based income sit at the center of the story.
Here the picture is mixed. Against its immediate peers, the 13.8x multiple is expensive compared to a peer average of 11.2x. This suggests the market is assigning a premium to Restaurant Brands International Limited Partnership relative to similar hospitality operators. Against the wider North American Hospitality industry, that same 13.8x P/E looks cheap next to the 17.8x industry average. This shows investors are not paying up as much for these earnings as they are across the sector.
So the current P/E signals that the units carry a premium tag versus close comparables but a discount against the bigger hospitality universe. For anyone tracking valuation shifts, that split view is worth watching as earnings quality, growth patterns, and balance sheet choices evolve around the franchise model.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 13.8x (ABOUT RIGHT)
Still, Restaurant Brands International Limited Partnership faces pressure if franchisees struggle with higher input costs or if consumer demand softens and puts its quick service volumes under strain.
Find out about the key risks to this Restaurant Brands International Limited Partnership narrative.
Another view on Restaurant Brands International Limited Partnership’s value
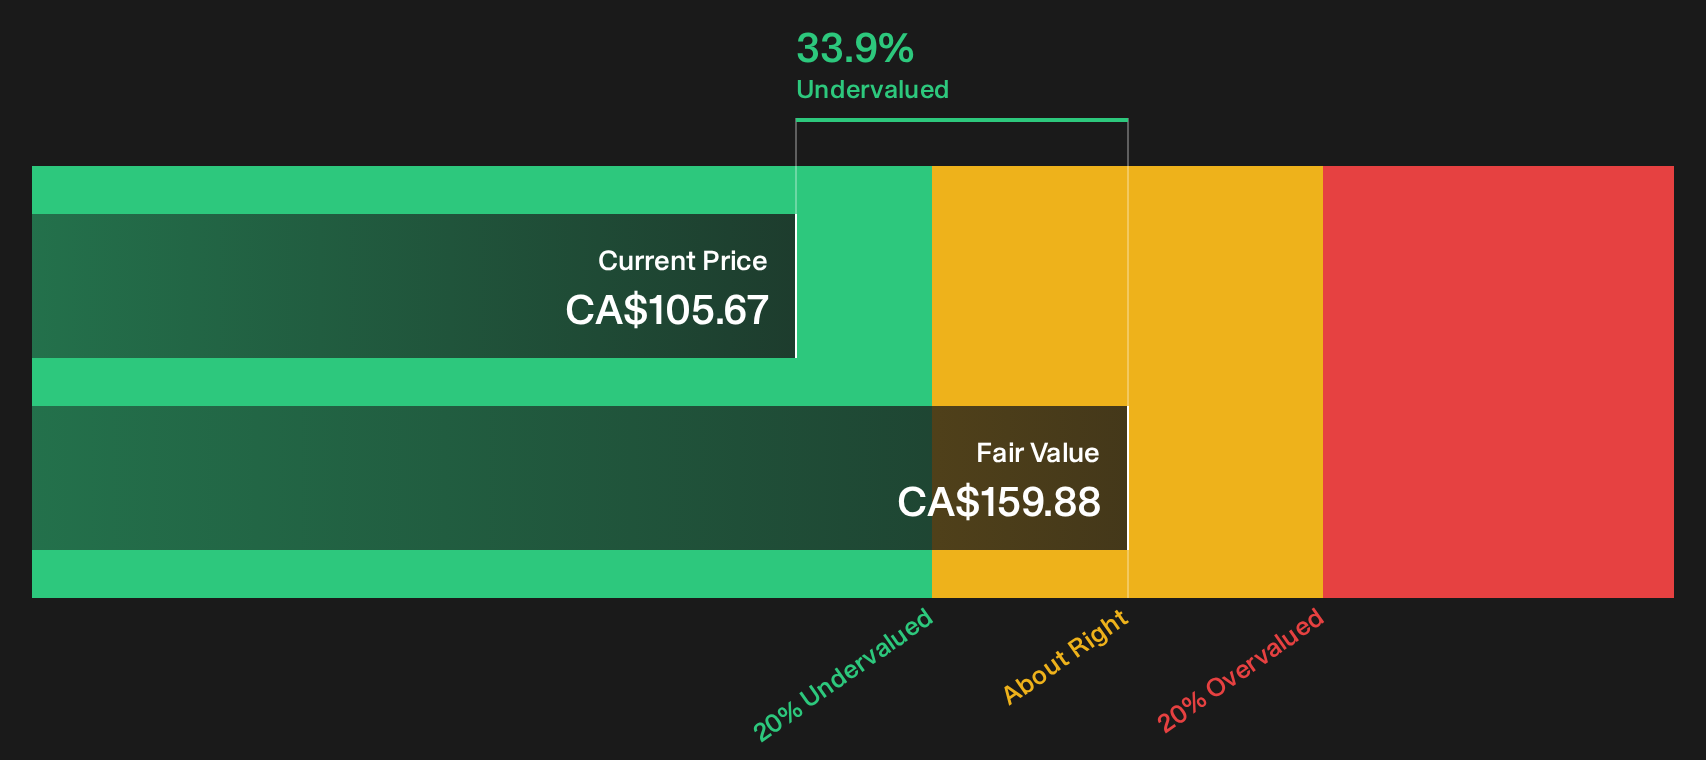
The story changes once you switch from the 13.8x P/E snapshot to the SWS DCF model. On that measure, Restaurant Brands International Limited Partnership at CA$105.67 sits about 33.9% below an estimated future cash flow value of CA$159.88, which points to a very different read on pricing.
That kind of gap suggests the units might be priced for more cautious assumptions than the DCF implies, especially given QSP.UN’s 18.8% net margin and 51.5% recent earnings growth. The question for investors is which lens feels more realistic when evaluating how this franchise system converts its cash flows over time.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Restaurant Brands International Limited Partnership for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Restaurant Brands International Limited Partnership so far. If you want to move before sentiment shifts again, weigh both sides of the story and run your own checks with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Restaurant Brands International Limited Partnership?
If Restaurant Brands International Limited Partnership has your attention, consider broadening your search with a few targeted stock ideas so you are not relying on a single opportunity.
- Target potential mispricings by scanning the 5 high quality undervalued stocks, which currently combine compressed valuations with more resilient fundamentals.
- Strengthen your income stream by checking out the 3 dividend fortresses, which may offer higher yields alongside more established cash generation.
- Reduce portfolio stress by focusing on the 8 resilient stocks with low risk scores, which score better on balance sheet strength and downside factors.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com