


Rithm Capital has delivered a 27.8% gain over the past three years, yet its recent pullback has many investors asking whether the current share price still lines up with what the business earns. With the stock now around US$8.66, the question is how much of its earnings power is already reflected in that tag.
- A 27.8% return over three years puts real weight on the issue of whether Rithm Capital’s earnings can support where the stock trades today.
- Genesis Capital’s US$375m multifamily-only securitization may support expectations that Rithm Capital can keep monetizing its lending platform and recycle capital efficiently.
- The analysts covering Rithm Capital have run their own numbers. See what analysts think Rithm Capital's shares could be worth.
The issue now is whether Rithm Capital’s current price is justified by its earnings when measured against the Fair Ratio benchmark.
If you want more context around Rithm Capital’s earnings driven story, it can help to compare it with other income focused opportunities screened for yield strength, such as 8 dividend fortresses.
Is Rithm Capital Still Cheap on Earnings?
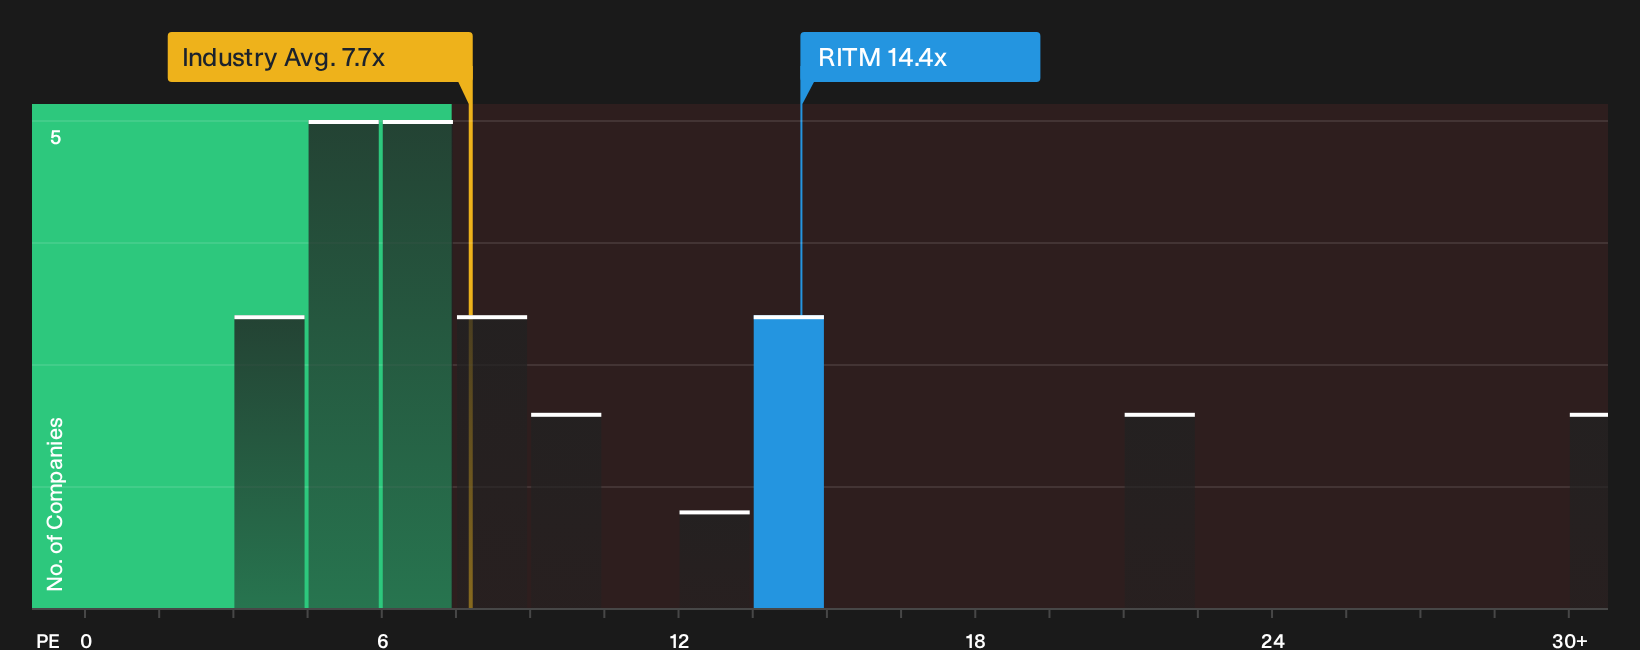
P/E is a useful yardstick for Rithm Capital because earnings are a key focus for income oriented investors watching how the business turns equity into profit. At around 14.4x, the stock trades below the Mortgage REITs sector average of about 7.7x in absolute terms but also sits well under a peer group that averages roughly 37.5x, so the market is assigning it a middle ground earnings tag within a wide range of valuations across the space.
Because the recent Genesis multifamily securitization has put a spotlight on Rithm Capital’s lending engine, the current P/E looks modest relative to the multiple you would expect for this profile based on its earnings quality, book value and risk inputs. This points to the shares screening as undervalued on this framework. The Fair Ratio benchmark suggests investors are not paying a demanding price for each dollar of earnings at today’s level, which leaves the question of how durable those earnings are over time as the key judgement call. Explore the numbers behind Rithm Capital's P/E valuation.
The Rithm Capital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Rithm Capital valuation puzzle leaves off. They spell out which paths for earnings, margins and growth would need to play out for the stock to be worth materially more or materially less than it is today on the market. Each scenario is framed as a thesis about Rithm Capital's fair value that can be revisited over time, so you can see how the idea holds up as new information arrives on the Community page.
One of the top community narratives on Rithm Capital: 34% undervalued
"The main factor that has to go right is successful execution on scaling third party AUM, mortgage servicing, and technology driven cost savings…"
Discover why this Narrative puts Rithm Capital at 34% undervalued.
One more angle on Rithm Capital that could change how you see this stock
Everything so far has focused on what Rithm Capital looks like today, yet professional coverage also sketches where the business might be a few years out. That extra lens can sharpen how you view the current tag. Explore where analysts expect Rithm Capital to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com