


Hotter inflation data that lifted Treasury yields has hit Bandwidth (BAND), putting fresh pressure on this high-multiple stock and prompting investors to recheck its valuation, growth story, and cash flow profile.
Over the past year, Bandwidth has swung between sharp rallies and steep pullbacks, with the share price still showing a 204.78% year to date gain despite a 39.65% decline over 90 days. The 1-year total shareholder return of 184.38% suggests that earlier momentum may be slowing as investors reassess valuation and risk following the inflation shock.
Compare how investors are pricing Bandwidth's story against other high-multiple opportunities by scanning our hand-picked 33 high quality undervalued stocks, which still show solid fundamentals and disciplined balance sheets.
The swing from a 204% year to date surge to a 40% pullback leaves Bandwidth looking either reset or still stretched. Does that recent drop now tilt the risk reward in buyers’ favor as the valuation math comes into focus?
Most Popular Narrative: 36% Undervalued
Against the last close at $43.34, the most followed narrative points to a fair value of $67.25, which makes Bandwidth look materially mispriced and puts its AI communications thesis front and center.
The ongoing migration of large enterprises from on-premises telephony to cloud-based communications solutions (UCaaS/CCaaS), often in regulated verticals, positions Bandwidth as a preferred provider for mission-critical, compliant, and reliable communications infrastructure, supporting sustained revenue growth and larger, higher-margin multi-year deals.
Increasing demand for secure, integrated communication APIs as digital transformation and remote work persist globally is expanding the total addressable market, with Bandwidth winning complex migration contracts and channel partnerships that are delivering record deal volume and supporting top-line expansion.
See why 11 investors see Bandwidth as 36% undervalued.
Result: Fair Value of $67.25 (UNDERVALUED)
Still, the Bandwidth narrative leans on concentrated enterprise relationships and significant Maestro and AI exposure, so slower adoption or contract changes could quickly challenge today’s optimism.
Find out about the key risks to this Bandwidth narrative.
Another View on Bandwidth's Valuation
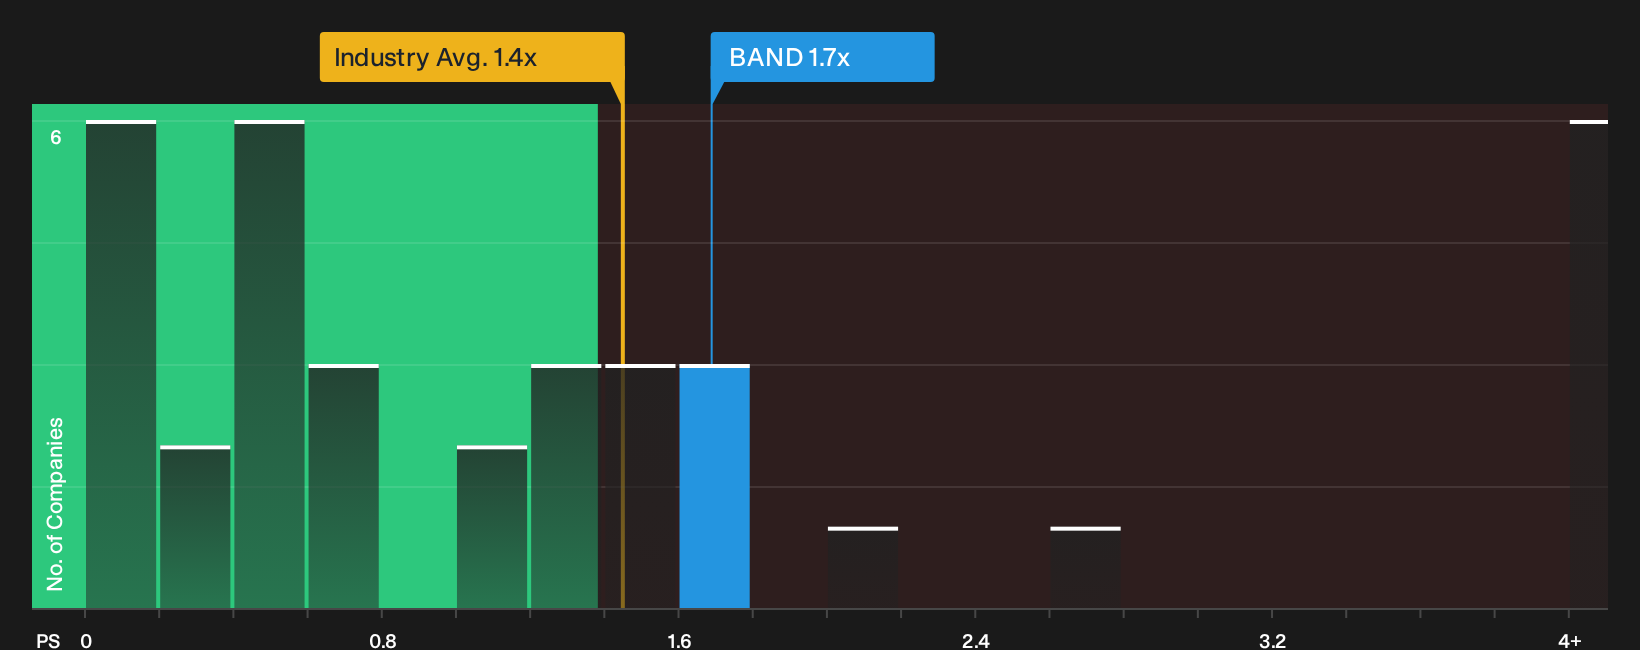
The popular narrative argues that Bandwidth is materially undervalued, yet the price tag tells a different story when compared with sales. The stock trades on a P/S of 1.7x versus 1.4x for the wider US Telecom industry and a fair ratio of 1.1x, which implies investors may be paying up for execution risk rather than getting a clear bargain. Which lens do you trust more when real money is on the line?
For a closer look at what the current multiple implies for upside and downside, check the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Bandwidth feels familiar, treat it as a prompt to move quickly and review the numbers yourself. Consider both the potential upside and the risks outlined in the 3 key rewards and 3 important warning signs.
Looking for more Bandwidth-sized ideas?
If Bandwidth has you rethinking what is possible in your portfolio, do not stop here. Use the Simply Wall Street Screener to uncover other opportunities before the crowd does.
- Hunt for mispriced potential by scanning companies that combine strong fundamentals with appealing valuations through the 20 high quality undiscovered gems.
- Prioritise resilience and steadier sleep at night by reviewing the 32 resilient stocks with low risk scores that score well on financial strength and volatility.
- Anchor your research in balance sheet quality by working through the list of solid balance sheet and fundamentals (25 results) that pair durable finances with sound fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com