


- Mortgage rates near three-year highs have coincided with a 6% drop in FHA purchase applications in early October 2026, pushing more would-be first-time buyers toward renting single-family homes managed by Invitation Homes.
- The widening gap between renting and owning costs is reinforcing Invitation Homes' focus on high occupancy and resident renewals as key drivers of operating cash flow resilience.
- We will now look at how Invitation Homes' investment narrative interacts with rising mortgage-driven rental demand and what that means.
Scan how rising mortgage costs are feeding into single family rentals like Invitation Homes, then run the same filter across our hand picked list of solid balance sheet and fundamentals (25 results) for comparison.
Invitation Homes Investment Narrative Recap
To own Invitation Homes, you need to believe that the rent versus own gap stays wide enough for single family rentals to remain attractive, and that high occupancy and renewals can offset softer earnings expectations. The latest mortgage spike supports near term demand, but it does not change that analysts currently see earnings declining over the next few years.
The near term swing factor is execution on expansion and capital recycling while keeping net operating income margins steady as taxes and insurance move around. The biggest risk remains rising supply from build to rent competitors that could pressure new lease rates and extend vacancies if demand cools from today’s mortgage driven boost.
Without fresh company announcements tied directly to this mortgage move, the most relevant context is the existing focus on growth channels like development, builder partnerships and the roughly US$350 million construction lending program. These pipelines matter more when more renters are being pushed out of the purchase market and into professionally managed homes.
For you as an investor, the question is whether Invitation Homes can convert that extra inquiry volume into durable cash flow while keeping leverage and interest costs under control. Capital recycling at sale prices around US$450,000 per home, where recent buybacks implied values nearer US$270,000, remains an important catalyst because it can support earnings per share even if headline profit trends look softer.
What The Current Analyst Numbers Assume For Invitation Homes
Analysts are effectively saying that for Invitation Homes, higher mortgage costs are feeding more renters into the funnel while the financial model still builds in softer profitability over time. That tension between steady rental demand and shrinking margins is what you need to weigh when you look at the stock next to your other solid balance sheet ideas.
On the top line, the current consensus bakes in revenue growth of 4.0% a year over the next three years. That pace underpins a 2029 revenue figure of about US$3.2b, which is the anchor for most of the published targets. The idea is that modestly growing rent collections from a larger pool of homes, plus contributions from development and construction lending, can keep total income rising even if each dollar of revenue converts into less profit than today.
Earnings tell a different story. The analysis pegs Invitation Homes' earnings today at US$658.8m and expects that to move to US$449.4m by 2029. That is a drop of roughly US$209m in absolute profit. Margin compression from 23.1% to 14.0% explains most of that gap. In plain terms, the business is modeled to collect more revenue but keep less of it after expenses such as property taxes, insurance and overhead.
Those same forecasts imply that by 2029 the stock would trade on a P/E ratio of 48.8x, up from 24.1x today, if the analyst targets prove accurate. That is above the current 41.9x P/E cited for the wider US residential REITs group. For you as an investor, that means the consensus view combines lower earnings, a higher multiple and the expectation that rental demand and asset values still support that richer valuation.
Invitation Homes' narrative projects US$3.2b revenue and US$449.4m earnings by 2029. This leans on revenue growing 4.0% per year and an earnings decline of about US$209m from US$658.8m today.
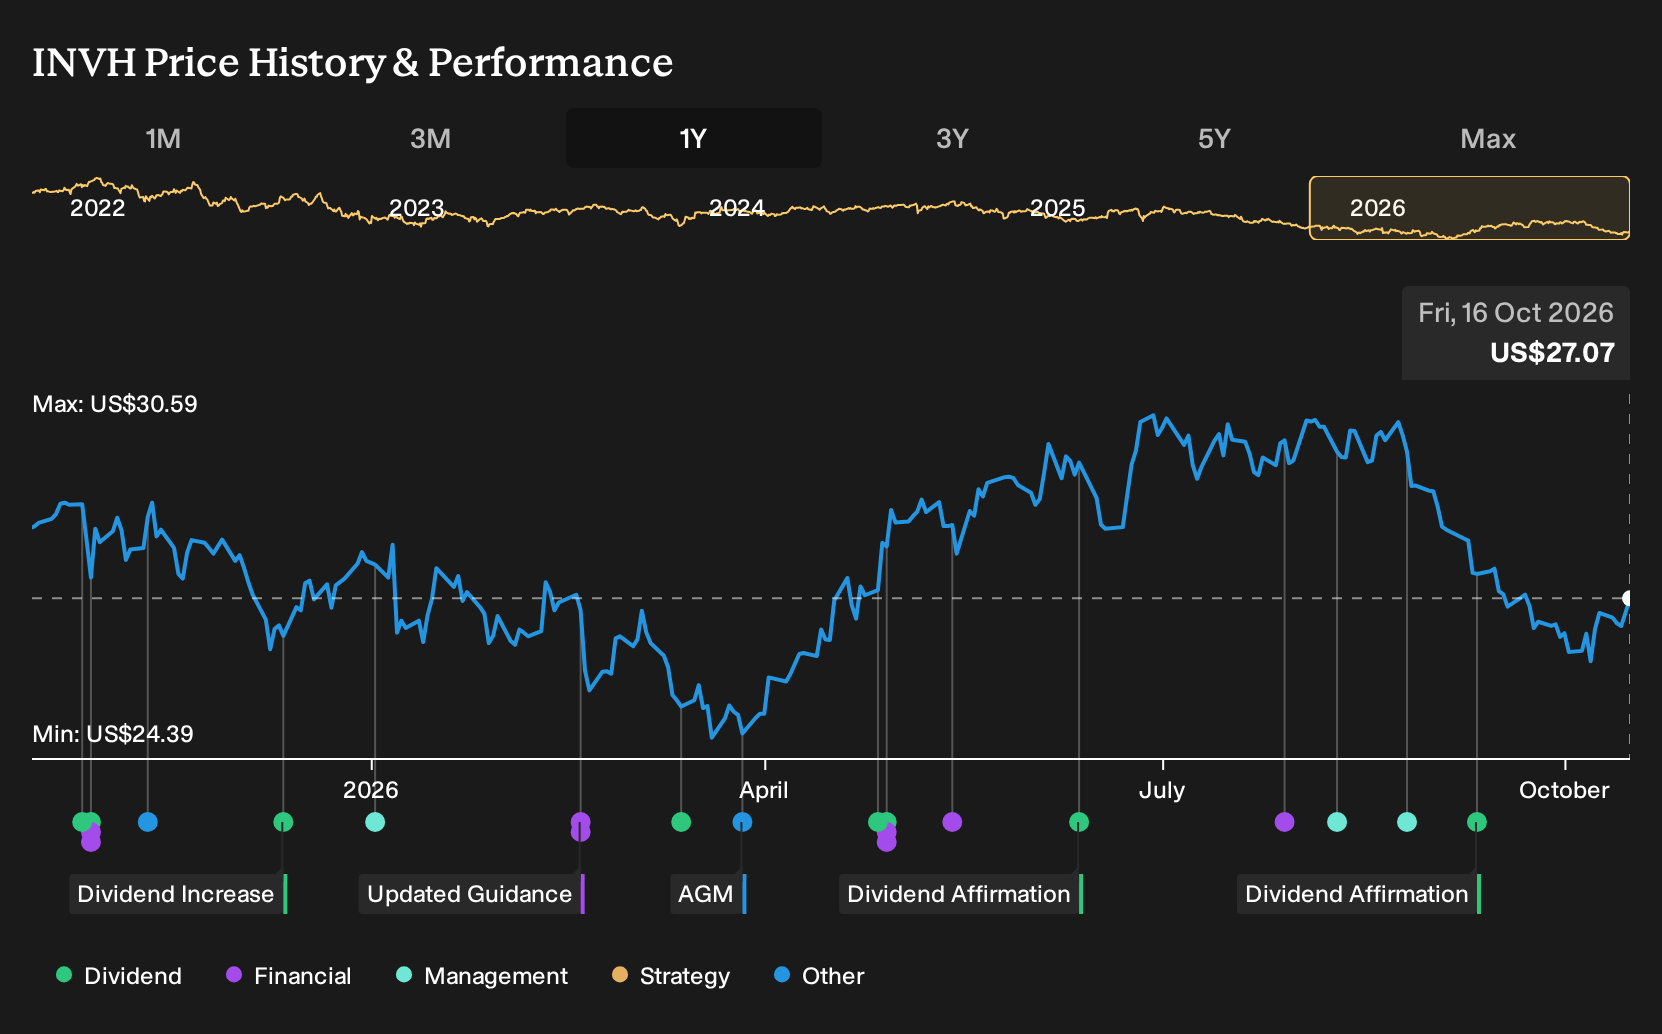
Uncover why Invitation Homes' fair value indicates a 24% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between about US$33.5 and US$40.5, so retail views on Invitation Homes currently sit in a fairly narrow band. That contrasts with risks around new build to rent supply and rising taxes and insurance, which could pull future opinions much further apart.
Explore another Invitation Homes fair value estimate, including one that suggests up to 50% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Invitation Homes research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Invitation Homes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Invitation Homes' overall financial health at a glance.
Looking for more investment ideas beyond Invitation Homes?
Once you have a view on Invitation Homes, a smart next step is to widen the lens and see how other companies with different profiles stack up on quality, balance sheet strength and income potential using the Simply Wall St Screener.
- If you want income as well as resilience, consider high yield opportunities that still clear key quality checks by scanning a curated set of 8 dividend fortresses.
- For readers who care most about resilient finances and lower balance sheet risk, compare Invitation Homes with our carefully filtered 32 resilient stocks with low risk scores.
- When you are hunting for new opportunities that fewer investors are watching, broaden your watchlist by running the screener across 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com