


- United Parcel Service has opened a new air hub at Clark International Airport in the Philippines, a 30,000 square meter facility that is 15 times larger than its predecessor, processes up to 15,000 packages per hour, and supports 170 weekly flight segments across more than 1,100 trade lanes.
- The Clark hub strengthens UPS’s ability to support higher value healthcare and time sensitive shipments within Asia and between Asia Pacific, Europe, and the U.S. This development aligns with its push toward premium volumes and more complex logistics services.
- We will now look at how this larger Clark air hub might influence United Parcel Service’s premium mix, cost efficiency, and earnings narrative.
United Parcel Service Investment Narrative Recap
To own United Parcel Service, you need to be comfortable with a story built on higher quality volumes, heavy use of automation and disciplined cost control, rather than rapid top line expansion. The near term hinge is execution on mix shift toward SMB, B2B and healthcare while large network changes, including building closures, do not erode service quality.
The biggest immediate risk is that the aggressive consolidation and high dividend commitments clash with any slowdown in earnings or cash generation. Holiday focused premium products and the Clark hub are helpful for the narrative around higher margin shipments, but they do not yet change those core execution and balance sheet questions.
The recent holiday shipping update feels most relevant here. UPS is leaning on RFID tracking, Protected Delivery PIN verification and tighter pickup visibility as concrete ways to make premium capacity more attractive, especially for high value e commerce and healthcare related parcels during peak season.
For investors, these services connect directly to the catalysts around premium mix and automation. Better tracking and secure drop off should support higher yielding flows, while partnerships like Happy Returns keep reverse logistics inside the UPS ecosystem. The potential reward still depends on this operational toolkit offsetting labor, debt and dividend coverage pressures.
United Parcel Service's narrative projects US$99.4b revenue and US$7.2b earnings by 2029. This implies 3.4% yearly revenue growth and an earnings increase of about US$2.6b from US$4.6b today.
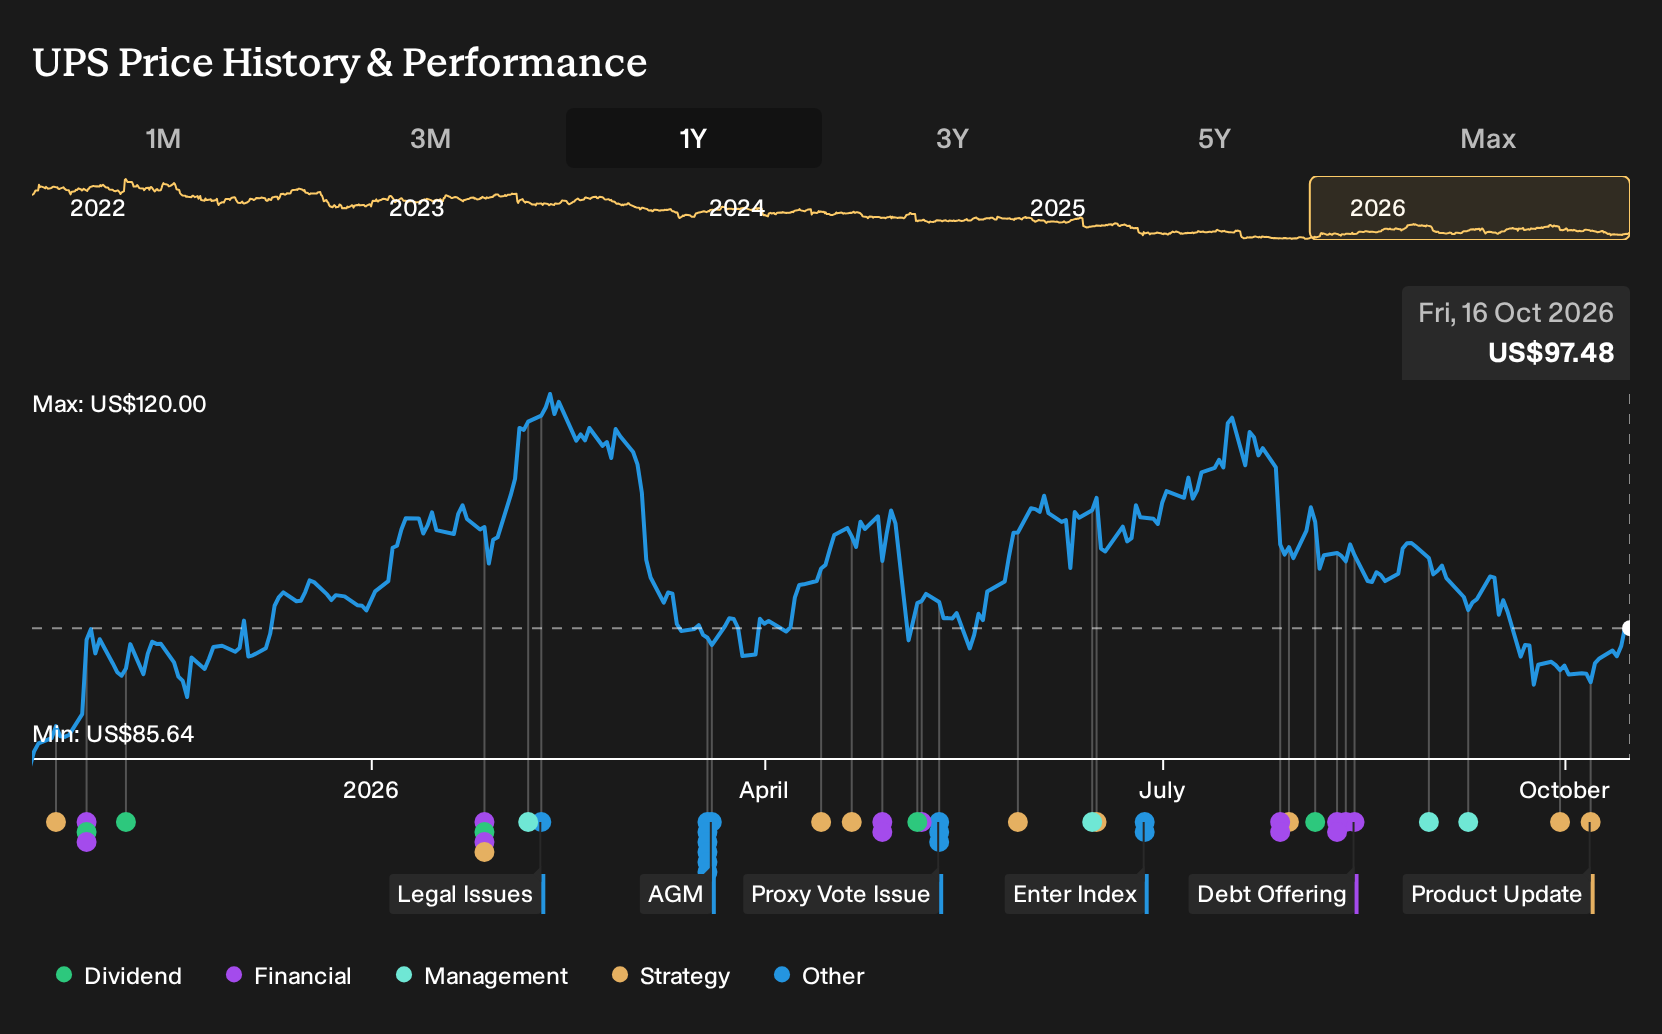
Uncover why United Parcel Service's fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on UPS’s healthcare and automation push as a potential earnings engine, with their pre news models pointing to revenue of about US$105.5b and earnings of US$8.6b by 2029. You can treat the Clark hub and new RFID security tools as fresh data points that might reshape those views.
Explore 9 other United Parcel Service fair value estimates, including one that suggests as much as 68% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own research and judgment.
- A great starting point for your United Parcel Service research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Parcel Service. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate United Parcel Service's overall financial health at a glance.
Looking For More Ideas Beyond United Parcel Service?
If the United Parcel Service story has sharpened your thinking about risk, cash flow quality and balance sheet strength, it can be useful to widen the search and compare it with other listed businesses that share similar traits.
- For readers who want potential value paired with robust fundamentals, start with companies flagged in our 33 high quality undervalued stocks and see which ones line up with your own quality thresholds.
- If reliable dividends are near the top of your checklist, focus on income focused companies screened as 8 dividend fortresses and see how their payouts and balance sheets stack up against your risk tolerance.
- When capital preservation is just as important as upside, narrow your watchlist to businesses highlighted as 32 resilient stocks with low risk scores so you can compare their resilience with what you see at UPS.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com