


Anthropic’s push to secure roughly $60b of chip financing has turned AI credit into front-page capital markets news, and it puts lenders to high-growth borrowers under a brighter spotlight. When debt packages of this size start clearing at coupons above 10%, the funding game changes quickly. This article walks through three positively exposed listed lenders that could feel the ripple effects of that shift.
The three stocks covered below are just a sample of what this theme can look like in public markets, and the full screen pulled out 23 more listed lenders with equally compelling tech and AI credit stories that are not covered here. To identify and analyze your own highest conviction plays in this space, head straight to the Listed Lenders to High-Growth Technology and AI Borrowers screener.
Blue Owl Capital (OWL)
Blue Owl Capital plugs directly into the screener’s theme through its private credit and specialty lending platform. This gives investors a way into the financing side of high-growth tech and AI, rather than owning the chip makers or cloud platforms themselves.
Blue Owl Capital runs an alternative asset management platform built around permanent capital vehicles, generating about US$3.0b from asset management services and focused on U.S. clients. It has a roughly US$14.0b market cap that anchors its role as a sizeable listed lender to growth borrowers.
"Significant ongoing growth in permanent capital vehicles, particularly through expansion in private credit, real assets, and evergreen and interval fund strategies, is still providing a larger base of recurring management fee revenue for Blue Owl Capital and keeps the potential for higher fee related earnings and durable margin expansion alive."
What really moves the needle from here is how one less visible funding shift plays out in the background of those fee streams.
That quiet shift is where things get interesting, so read the full narrative for Blue Owl Capital to see how those funding currents could be accelerating or masking the next chapter for Blue Owl Capital.

SUI Group Holdings (SUIG)
SUI Group Holdings gives you a pure-play way into bespoke financing for high-growth borrowers, plugging directly into the screener’s focus on lenders that help fund technology, start-up and expansion plans with tailored debt and equity packages.
SUI Group Holdings Limited is a principal investment firm that backs public and private companies with tailored debt and equity financing for start-up, acquisition and growth needs, closely aligned with tech-oriented and higher-yield lending. It generated about $3 million from Financial Services - Closed End Funds and has a roughly $103 million market cap.
For investors watching how AI-related credit is repriced after Anthropic’s massive chip financing push, SUI Group gives you a smaller, higher-octane way into the same conversation about yield, risk and capital access for growth borrowers.
"Although SUI Group is tying its core business to a high throughput blockchain that is being positioned for agentic AI driven commerce, the company is heavily exposed to ongoing mark to market swings in SUI."
What matters next is how one pressure point in that model shapes the trade off between eye-catching growth potential and the cost of absorbing volatility.
If that trade off is what you are weighing, read the full narrative for SUI Group Holdings to see how SUI Group aims to turn volatility into accelerating upside potential.
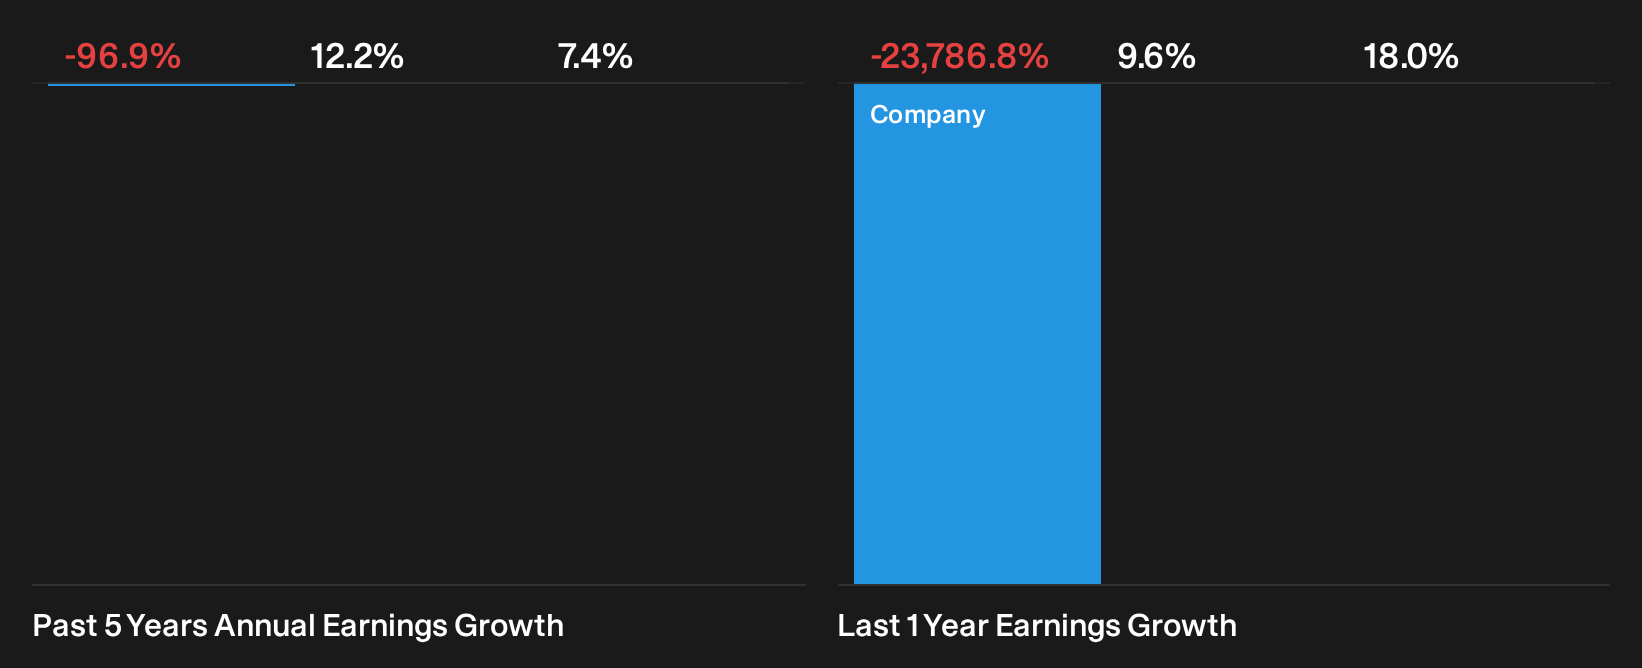
Moelis (MC)
Moelis gives you a different angle on the theme by sitting on the advisory and capital markets side of tech and AI financings rather than lending off its own balance sheet. This makes its build out in fee rich areas even more important.
Moelis & Company is a global investment banking advisory firm focused on mergers and acquisitions, restructurings and capital markets work, closely linked to growth and technology financings. All of its roughly US$1.6b in revenue comes from investment banking advisory, and it has a market cap of about US$4.5b.
"The accelerated expansion and investment into the private capital advisory business, now supported by seven dedicated managing directors and a growing focus on GP led, LP led and co investment solutions, positions Moelis to convert its strong mandate pipeline into higher advisory fees and, in turn, support revenue growth and earnings."
What matters for Moelis now is how one quiet shift in where those high value tech and AI related mandates land ends up feeding through to margins.
That quiet shift in fee rich mandates is exactly what the full narrative for Moelis unpacks, including how Moelis could turn advisory momentum into accelerating earnings power.

Seeking Alternatives Before The Crowd?
Fresh themes often move first, and slow money can get caught chasing momentum once prices are already elevated. Scan curated ideas that are under the radar for now and consider them before they attract widespread attention.
- Target steadier portfolio anchors while income investors focus on the same tickers by running the 8 dividend fortresses before yields change or spreads compress.
- Look for potential future compounders hiding in plain sight and run the 20 high quality undiscovered gems while these businesses are still priced like afterthoughts.
- Position for possible infrastructure opportunities and scan the 55 AI infrastructure stocks while these enablers of AI demand may still be mispriced by the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com