


- NXP Semiconductors recently presented at the Open Source Summit + Embedded Linux Conference Europe 2026 in Prague, highlighting its role in open source based embedded systems for automotive, industrial and IoT applications.
- Upward revisions to NXP Semiconductors earnings estimates point to changing expectations for demand, margins and design win conversion across its core end markets, with analyst upgrades cited as a secondary confirmation of that altered operating outlook.
- This article reviews how NXP Semiconductors investment narrative is influenced by rising earnings estimates and a recent favorable rating upgrade.
Compare how NXP Semiconductors' earnings momentum stacks up against other chip and hardware plays by scanning our hand picked 55 AI infrastructure stocks.
NXP Semiconductors Investment Narrative Recap
To own NXP Semiconductors, you need to be comfortable with a portfolio anchored in automotive, industrial and IoT chips, where design wins and content per car matter more than headline unit demand. The key near term swing factor is how quickly automotive and industrial customers rebuild inventories toward NXP Semiconductors targets, which could influence order patterns and earnings visibility.
The biggest operational risk right now sits in a potential automotive correction in China and investor preference for data center heavy chip suppliers. Upward earnings revisions can improve confidence, but they do not remove concerns about high debt, possible M&A around edge AI, or the wide guidance ranges that previously unsettled the market.
The Zacks Rank upgrade linked to rising earnings estimates is the clearest recent signal tied to these catalysts. Analysts lifting their numbers usually reflects more confidence in how auto, industrial and IoT demand is feeding through to NXP Semiconductors order book and margins, as well as progress on newer processing portfolios and physical AI opportunities.
That said, this kind of rating move does not change the operational work required. NXP Semiconductors still has to manage Chinese auto exposure, execute on its asset light manufacturing build out, and be disciplined around any Ambarella style acquisition. For you, the question is whether the improving earnings outlook offsets those execution and balance sheet risks.
NXP Semiconductors Earnings and Valuation Set Up
NXP Semiconductors is being modeled on a fairly tight set of numbers. Analysts are plugging in 10.2% annual revenue growth for the next few years, a lift in profit margins from 22.6% today to 26.5% in three years, and a bigger earnings base off that trajectory.
On those assumptions, forecasts point to earnings moving from US$3.0b today to US$4.7b by 2029, with some researchers penciling in as much as US$5.3b. That implies roughly a 1.6x step up in profit dollars over the period, which is a meaningful swing for any chip supplier tied closely to auto and industrial cycles.
To get there, models link the forecast profit pool to a revenue line of about US$17.6b in 2029. The math then applies a P/E of 23.5x to those projected earnings, compared with a multiple of 19.3x today and a higher ratio cited for the broader US semiconductor peer set.
The narrative around NXP Semiconductors projects US$17.6b revenue and US$4.7b earnings by 2029. This rests on 10.2% yearly revenue growth and roughly a US$1.7b earnings increase from US$3.0b today.
Those figures feed directly into the current fair value debate. The consensus target price of US$311.10 sits 26.7% above the recent share price of US$227.99. Meanwhile, the spread between the high target of US$400.00 and the low mark of US$190.00 shows how differently analysts are treating the same data.
For you, the key question is not just whether NXP Semiconductors can reach US$17.6b of revenue and US$4.7b of earnings by 2029. The decision is whether a P/E of 23.5x on those projected profits feels reasonable for a chip vendor whose fate is closely tied to auto content, industrial demand and a still developing edge AI push.
Uncover why NXP Semiconductors' fair value indicates a 36% potential upside to its current price, which could narrow quickly.
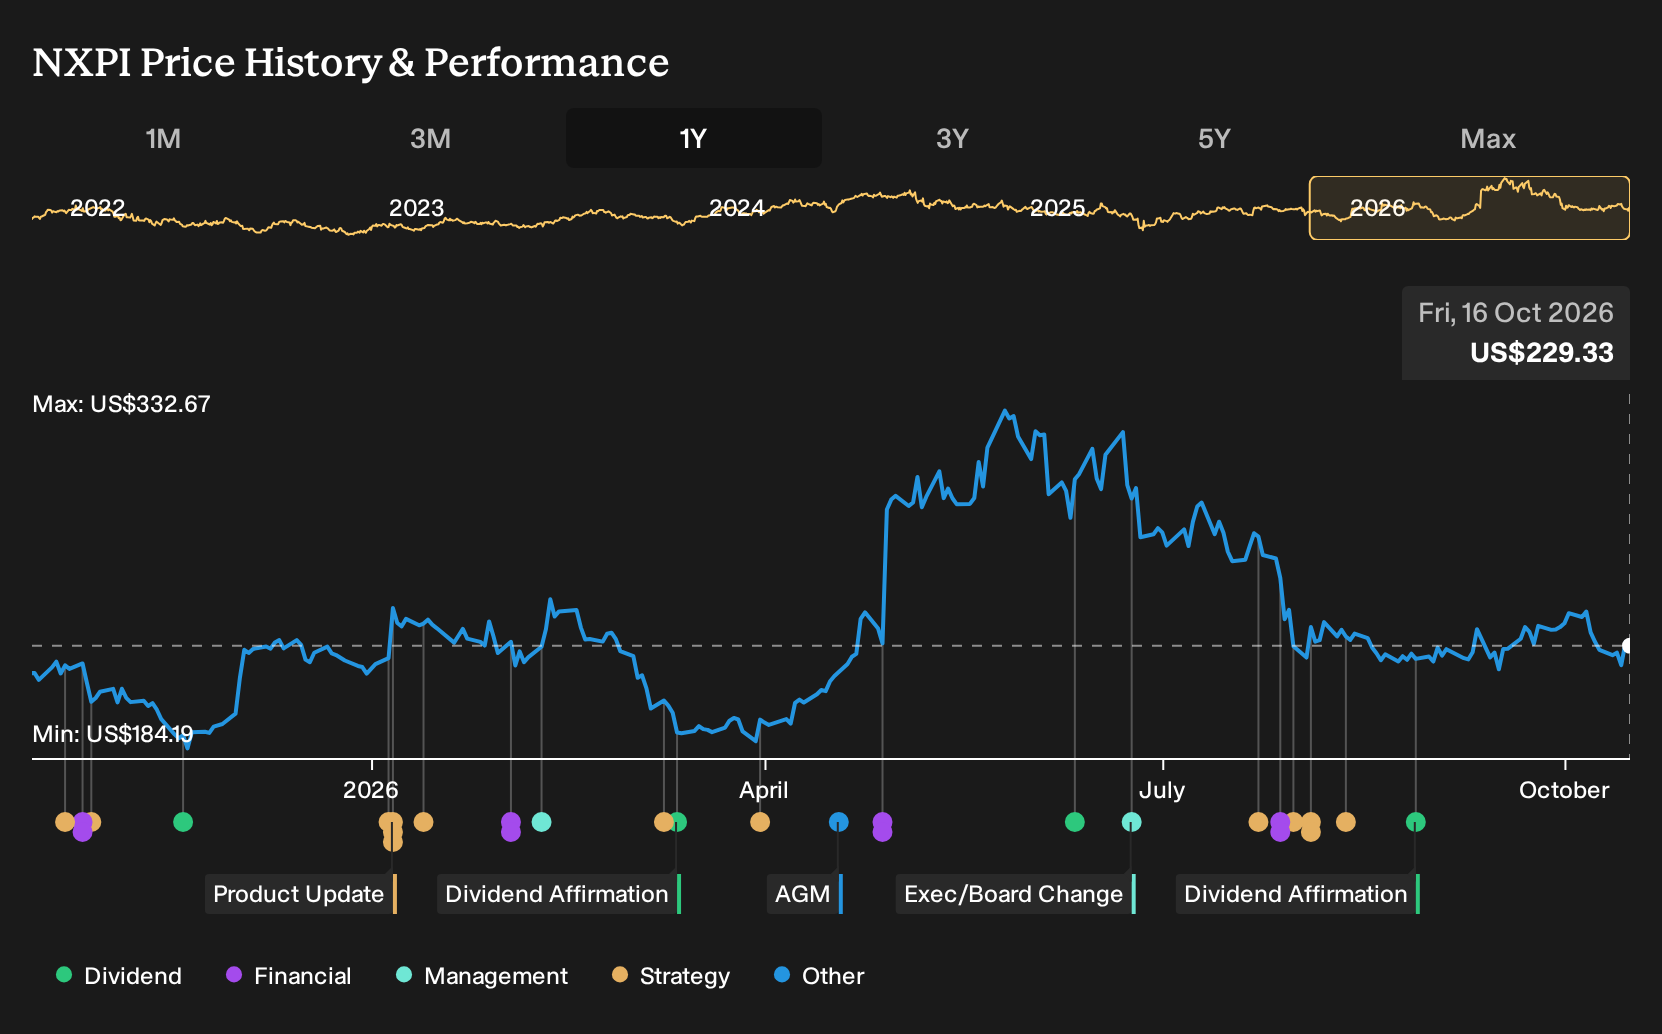
Exploring Other Perspectives
You are seeing two very different stories about NXP Semiconductors. The most optimistic analysts focus on edge AI as the swing factor, with pre event models already penciling in US$19.4b of revenue and US$5.3b of earnings by 2029. Others work off much lower figures. Use this conference news to compare the scenarios and consider which path appears more realistic, recognizing that both narratives may change over time.
Explore 5 other NXP Semiconductors fair value estimates, including one that suggests potential upside of as much as 72% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NXP Semiconductors research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NXP Semiconductors. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NXP Semiconductors' overall financial health at a glance.
Looking For More Investment Ideas Beyond NXP Semiconductors?
If NXP Semiconductors has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you line up other candidates that fit different risk and income profiles.
- If capital preservation comes first for you, start with a basket of steadier businesses by reviewing 32 resilient stocks with low risk scores that may better match a cautious approach.
- If strong finances matter most, filter for companies with healthier funding and sturdier operations through the list of solid balance sheet and fundamentals (25 results) that keeps resilience front and center.
- If you are hunting for mispriced opportunities, broaden your opportunity set by scanning a 33 high quality undervalued stocks that combines quality metrics with pricing that some investors may be overlooking.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com