


SHIFT (TSE:3697) drew fresh attention after a packed October 15 update that combined its Q4 2026 earnings, new earnings outlook, and a step-up in both current and future dividend plans.
SHIFT’s latest update landed after a sharp swing in sentiment, with the 1-day share price return of 16.52% and 30-day share price return of 23.66% pointing to rapidly building momentum, even as the 1-year total shareholder return declined 5.97% and the 3-year total shareholder return fell 39.65%. This leaves recent gains set against a much weaker longer-term record.
Compare this sharp SHIFT move with a curated set of other momentum opportunities on our 73 high quality undiscovered gems, which pair strong fundamentals with recent price strength.
SHIFT now pairs a growing testing business with a fresh dividend story and a sharp rebound in the share price. The real tension is whether that mix is already fully reflected in today’s valuation.
Preferred P/E Multiple of 36.4x: Is it justified?
On a P/E of 36.4x, SHIFT trades at a visibly richer valuation than much of the Japanese IT sector, even after the recent move to ¥1,058. That places the stock in a bracket where investors are clearly paying up for expected growth and profitability rather than current margins.
The P/E ratio compares the current share price to earnings per share and, for a software testing specialist like SHIFT, often acts as a shorthand for how confident the market is about future earnings power. With earnings expected to grow significantly over the next 3 years and forecast annual profit expansion of 36.5% against the broader JP market at 9.5%, the current multiple suggests investors are already baking in a meaningful improvement in profitability and returns.
Relative to peers, the gap is wide. SHIFT’s 36.4x P/E is described as expensive versus the Japanese IT industry average of 16.1x and the peer group average of 19.6x. Yet when set against an estimated fair P/E of 40.7x for this business, the current ratio sits below the level the market could move towards if earnings and returns track expectations, which frames today’s valuation as demanding but not extreme.
Explore the SWS fair ratio for SHIFT.
Result: Price-to-Earnings of 36.4x (ABOUT RIGHT)
Still, SHIFT’s story could be knocked off course if the high expectations embedded in that 36.4x P/E encounter slower profit growth or any sharp sentiment reversal.
Find out about the key risks to this SHIFT narrative.
Another View: SHIFT Through The DCF Lens
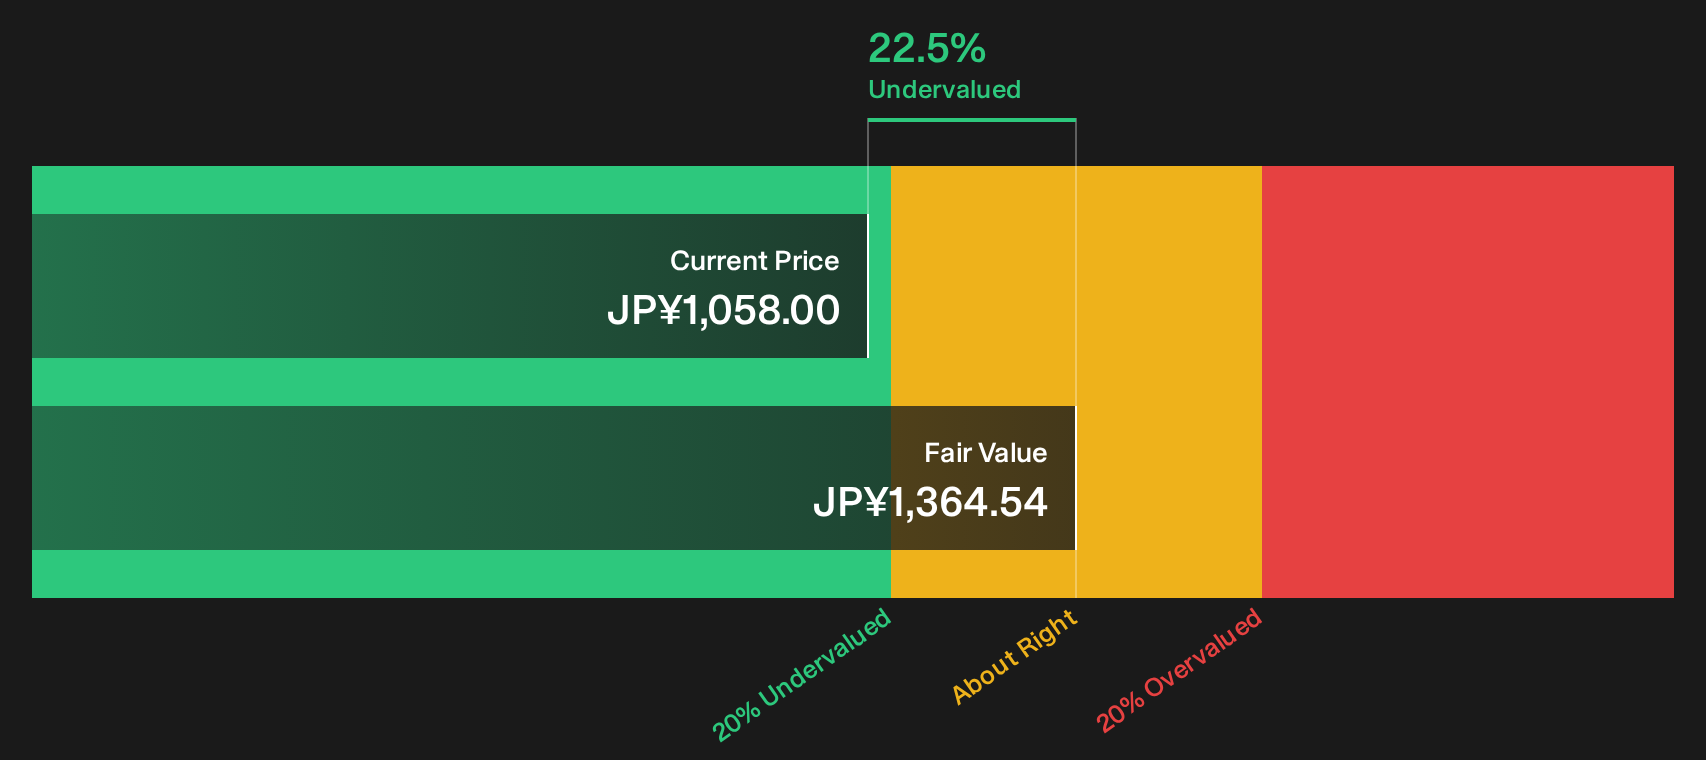
The earlier P/E work paints SHIFT as reasonably priced for its earnings power. A different tool, the SWS DCF model, values future cash flows at ¥1,364.54 per share versus a market price of ¥1,058, which points to SHIFT trading at a discount on this framework.
That gap between price and DCF value can signal either a potential opportunity if those cash flows materialise, or a warning that the model is too optimistic. The key question for you is which side of that tradeoff feels more realistic for SHIFT right now.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out SHIFT for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of optimism and caution around SHIFT feels finely balanced, do not wait for a perfect signal before checking the detail for yourself. To see both sides of that ledger in one place, review the 2 key rewards and 2 important warning signs.
Looking for more SHIFT investment ideas?
Do not stop at SHIFT alone. Broaden your watchlist with a few targeted filters that can surface fresh opportunities before they show up on everyone else’s radar.
- Spot potential turnarounds early by scanning 1 elite penny stocks with strong financials that already show improving fundamentals and tighter financial discipline.
- Zero in on quality at a compelling price by reviewing the 14 high quality undervalued stocks that combine solid balance sheets with attractive earnings metrics.
- Build a cash flow focused watchlist by checking the 29 dividend fortresses that pair higher yields with robust coverage and consistent payout records.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com