


- ADMA Biologics reported that a peer reviewed article has now validated its optimized IVIG manufacturing process, showing effective removal of procoagulant impurities, maintained immunoglobulin quality and no thromboembolic events in the evaluated postmarketing period.
- The study also reports higher IgG yield from the optimized process, which could matter for ADMA Biologics' cost efficiency, capacity utilization and product positioning in a competitive immunoglobulin market.
- This development may influence how investors view ADMA Biologics' investment narrative, particularly in light of the peer reviewed validation of its optimized IVIG safety profile.
ADMA Biologics Investment Narrative Recap
To own ADMA Biologics, you need to believe the immunoglobulin franchise, especially ASCENIV, can keep supporting high margin production while the broader IVIG market stays competitive. The recent peer reviewed validation of the optimized IVIG process mainly reinforces the operational story rather than changing it. The near term focus still sits on execution after revised 2026 guidance and on how management handles pricing and contract pressure.
The biggest operational risk remains concentration in a few therapies in a crowded IG space, alongside ongoing legal actions tied to ASCENIV. In that context, this new safety and yield data looks supportive but not transformative. It strengthens confidence around manufacturing and gross margin durability, yet it does not replace the need for consistent ASCENIV demand, careful discounting and tight working capital control.
The May 2026 FDA label expansion for ASCENIV into children aged 2 and older ties directly into this latest manufacturing update. Stronger safety and impurity removal data align well with a broader primary immunodeficiency population, since prescribers and payers will likely scrutinize thromboembolic risk and product quality as use extends into younger and medically complex patients.
For investors, that expansion is a practical near term catalyst. It increases the addressable treated group while the optimized process is already embedded at commercial scale and supporting reported gross margins in the high 60s to low 70s. The operational question is whether ADMA Biologics can continue shifting mix toward higher margin ASCENIV, maintain its competitive footing against discounted standard IG, and advance SG-001 to reduce reliance on the current product set.
ADMA Biologics' current earnings of $169.0 million are set against analyst projections that call for revenue expanding at 15.2% a year and earnings of $317.5 million by 2029. This implies an earnings increase of about $148.5 million and ties to forecast revenue of $783.1 million in the same year.
Uncover why ADMA Biologics' fair value indicates a 59% potential upside to its current price that could narrow quickly.
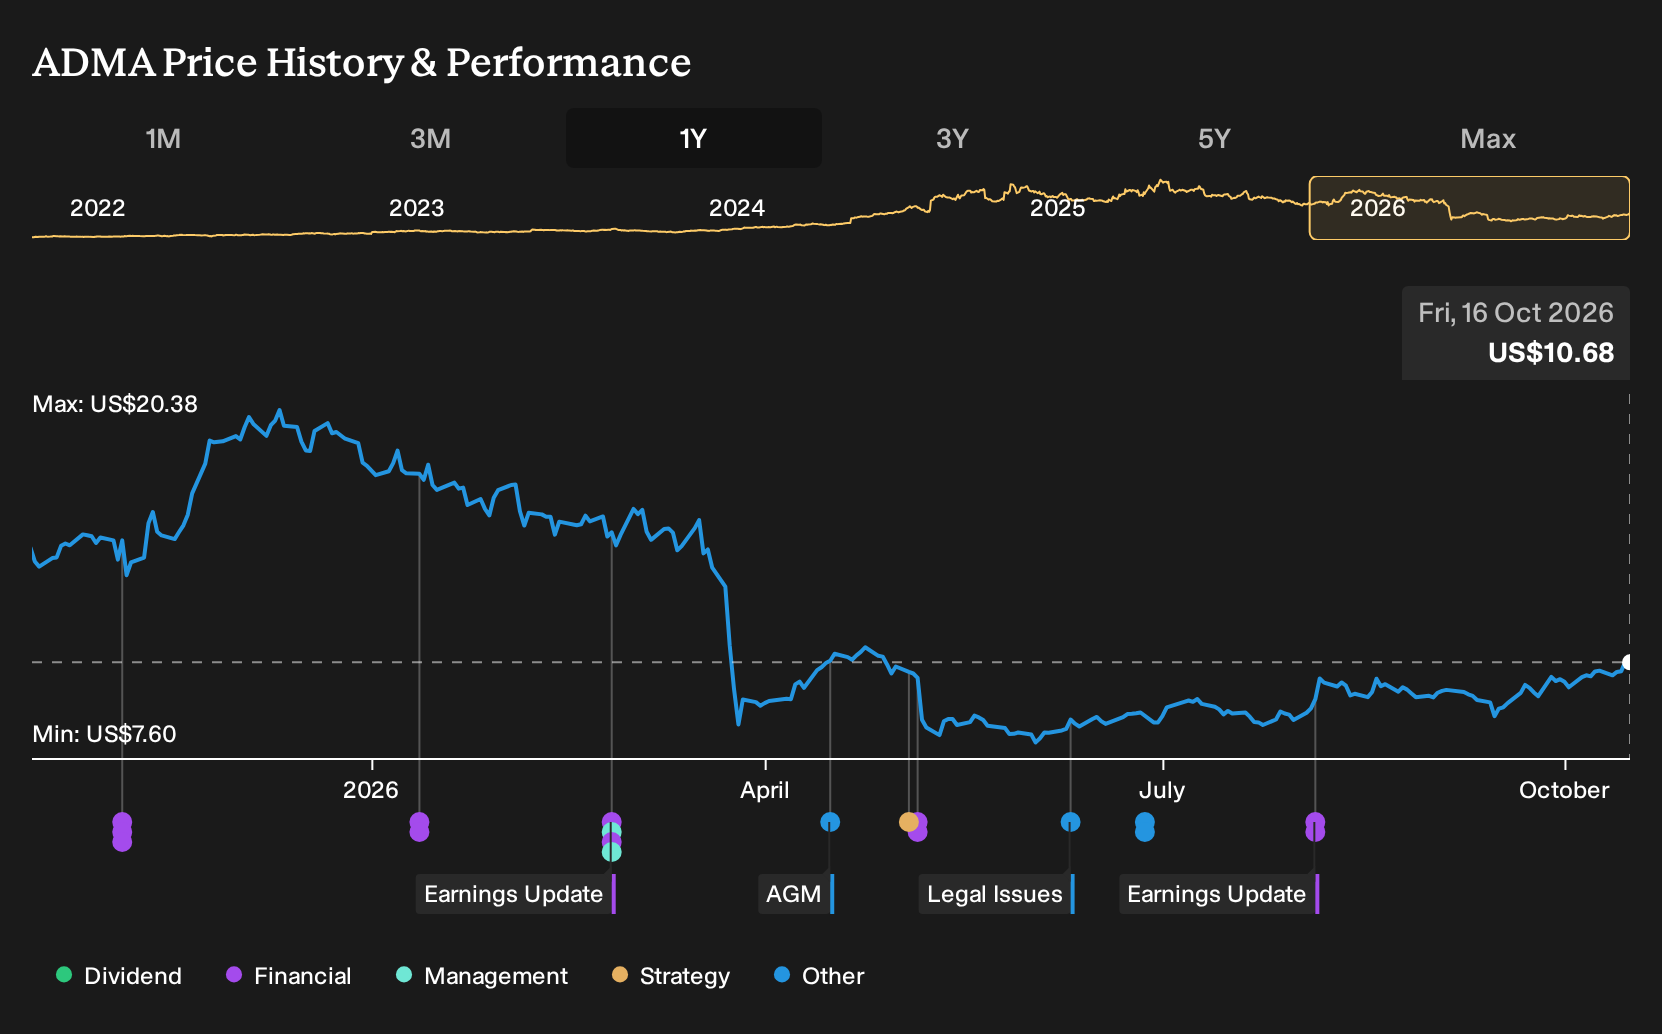
Exploring Other Perspectives
Some of the most optimistic analysts frame the real swing factor very differently. They focus on ADMA Biologics’ earnings potential if ASCENIV keeps gaining share, with bullish models already penciling in about US$899.5 million of revenue and US$365.3 million of earnings by 2029. Those projections were set before this IVIG safety publication, so you may see forecasts shift as views update.
Explore 7 other ADMA Biologics fair value estimates, including one that suggests as much as 242% potential increase from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your ADMA Biologics research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ADMA Biologics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review ADMA Biologics' overall financial position at a glance.
Looking for more ADMA Biologics sized ideas?
If the ADMA Biologics story has sharpened your thinking about risk, reward and balance sheet strength, it can be useful to compare it with other companies that clear similar quality bars. The Simply Wall St Screener can help you quickly filter for different combinations of fundamentals so you are not relying on a single stock to carry your thesis.
- For investors who care most about financial resilience and staying power, start with a 32 resilient stocks with low risk scores that have historically scored well on stability and downside protection.
- If you are hunting for quality at a reasonable price, use the screener focused on 33 high quality undervalued stocks that combine stronger balance sheets with attractive fundamentals.
- Those looking to spot earlier stage opportunities with room to mature can review a curated 14 elite penny stocks with strong financials that already show meaningful financial strength relative to typical micro caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com