


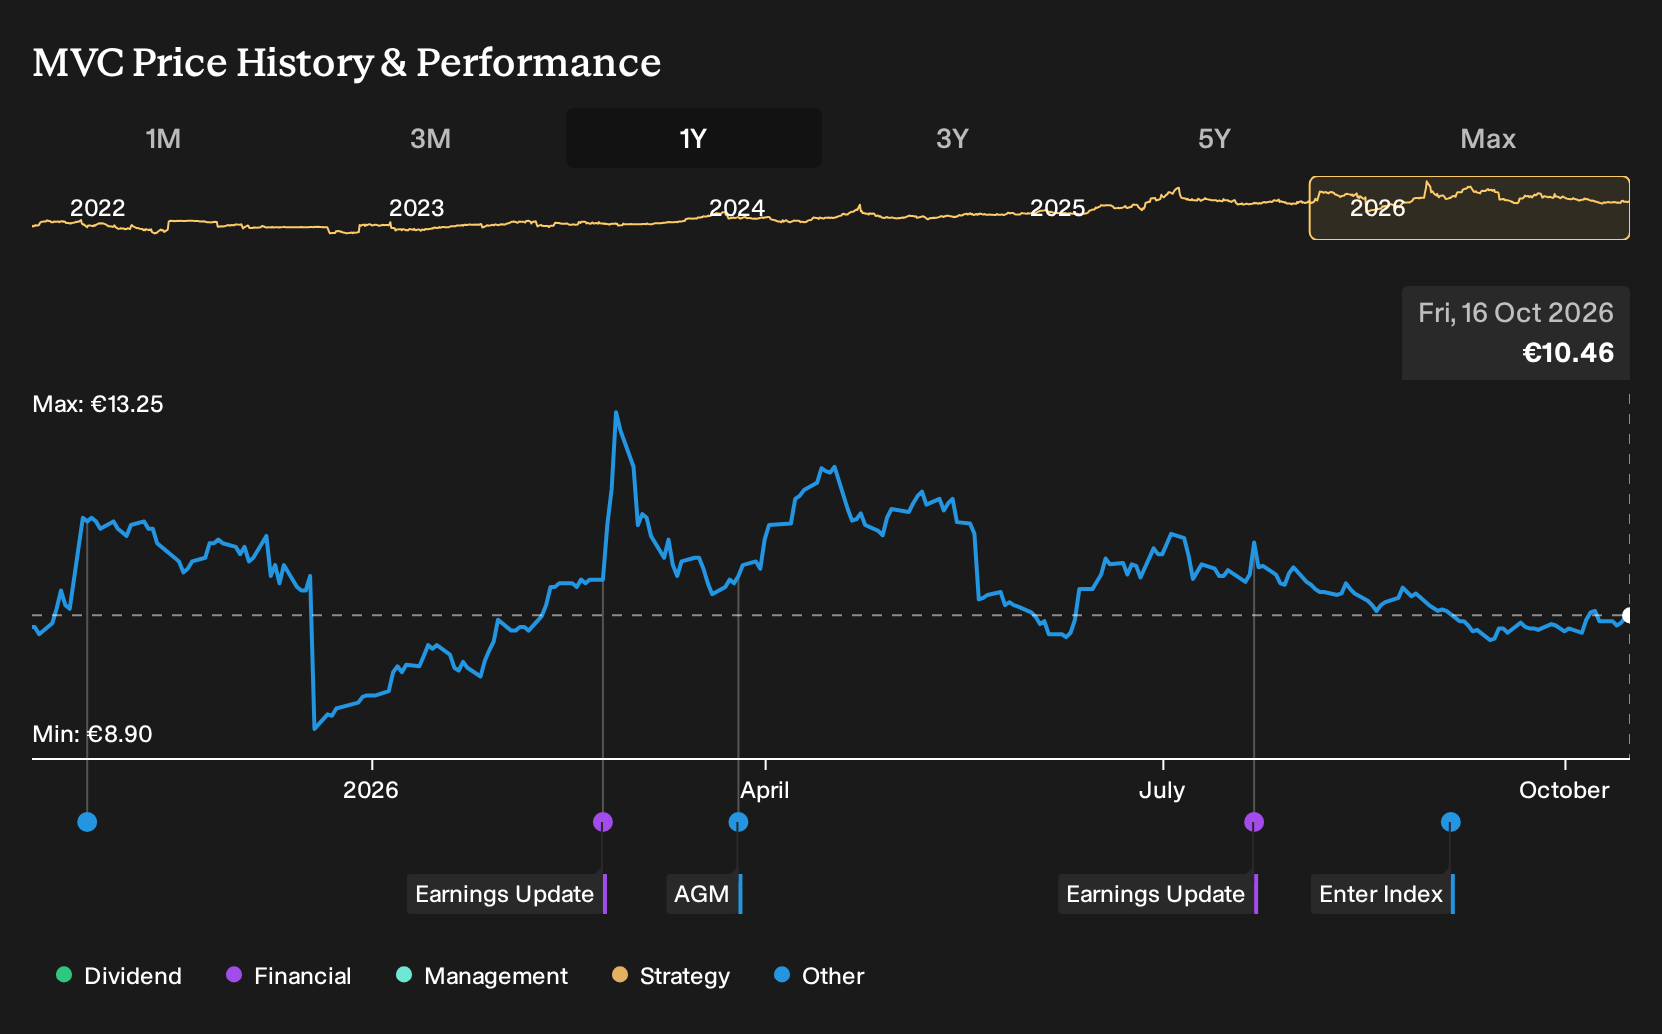
If Metrovacesa had been on your watchlist instead of in your portfolio, the result over the last year might feel like a missed chance. For Metrovacesa shareholders, the return over the past year was 23.8%, including dividends. That outcome now sits alongside record revenues, a 26.2% gross margin and a 17% dividend yield, which arrived after the fact. The real question is whether the early commitment to AA energy efficient projects was a clear enough clue at the start.
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Metrovacesa is not the only name tied to this theme. Zero in on 41 power grid technology and infrastructure stocks and compare how each one is priced.
The Argument Metrovacesa Investors Were Really Weighing
The shares cost €10.3 at the start of the period, and anyone looking at Metrovacesa then had to choose between two very different stories that both sounded plausible.
In the bullish Narrative, Fair Value sat at €11.8, or 15% above the start price. Supporters leaned on AA energy efficient projects that could justify premium pricing and cheaper green financing.
The bearish Narrative pointed to a Fair Value of €6.5, or 37% below the start price. Critics worried that stricter environmental rules and higher compliance costs might squeeze future margins.
What The Results Changed For The Metrovacesa Story
The clearest update arrived in the H1 2026 report. Metrovacesa recorded revenue of €317.381m and net income of €17.835m, compared with €132.522m and a loss of €15.492m a year earlier. Net margin moved from a loss of 11.7% to a gain of 5.6%. That shift in profitability supported the optimistic case more than the cautious one.
The hinge assumption was whether AA energy efficient projects and the wider plan could support healthier earnings. When you assess another developer, check if rising revenue is matched by a clear turn in net margin and net income, not just a strong story about green projects.
What Metrovacesa’s Price Seems To Assume Today
Metrovacesa now trades at €10.46, and the selected Narrative sets its Fair Value below that level, so that view treats the stock as already pricing in a lot of good news.
The focus shifts to how reliably the backlog turns into cash generative completions. A buyer today would need confidence that permitting delays and heavier use of lower margin land sales do not erode earnings power over time.
"Although Metrovacesa reports a sales backlog of about 2,900 units worth €1.1b with a high share already presold, permitting delays that are pushing many construction starts into the second half of 2026 create a risk that a growing portion of this contracted revenue is recognised later than expected. This could soften near term reported revenue and earnings momentum."
The price and this Narrative do not agree. → Uncover what this Narrative says Metrovacesa is actually worth
Another Angle On Metrovacesa
Metrovacesa lives in bricks and planning approvals. Your watchlist does not have to stop there.
Think about the same housing need met in a different way. One platform tries to turn home moves into something closer to e commerce.
Instead of building units, it buys properties, resells them, and wraps in brokerage and insurance services around each move.
That kind of model depends on tight control of margins, inventory risk and funding costs.
If it executes well, the interesting question is how much traditional developers and pure digital operators start to rhyme in your portfolio.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 102% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com