


Why Harmonic Drive Systems' Valuation Is Under the Microscope
Fresh analysis of Harmonic Drive Systems (TSE:6324) has zeroed in on its elevated P/S ratio versus peers, as the stock's strong run draws sharper questions about how firmly demand for its precision components can support that premium.
At around ¥5,350 per share, Harmonic Drive Systems has seen its 1-year total shareholder return reach 77.57%, even as the 30-day share price return declined 10.39% and the 90-day share price return fell 17.31%. This suggests that strong longer-term momentum is now cooling as investors reassess how much they are willing to pay for that high P/S multiple.
Compare Harmonic Drive Systems' rich P/S premium with other robotics and automation plays by scanning our hand picked 92 robotics and automation stocks for potential alternatives and counterparts.
Recent gains in Harmonic Drive Systems appear linked to both healthy reported growth in revenue and net income, as well as a rich P/S multiple that has come under pressure. How much of the premium reflects business strength versus a reset in sentiment?
Preferred Price-to-Sales of 8.1x: Is It Justified?
Harmonic Drive Systems looks expensive on a simple yardstick. The stock trades on a P/S ratio of 8.1x, while our data shows the broader JP Machinery industry around 0.9x and a peer set near 1.1x, even as the latest close sits at ¥5,350.
P/S compares the market value of the equity to annual revenue. For a business like Harmonic Drive Systems, which supplies precision speed reducers and mechatronics into robots and semiconductor equipment, investors often use this metric when earnings are volatile but sales trends are still a useful anchor.
The current valuation implies buyers are paying a steep premium for each ¥ of revenue relative to machinery peers. The estimated fair P/S ratio of 2.4x is also far below the present 8.1x. This points to a rich valuation level that the market could eventually move closer to if sentiment or expectations reset.
Explore the SWS fair ratio for Harmonic Drive Systems.
Result: Price-to-sales of 8.1x (OVERVALUED)
Still, the rich P/S story around Harmonic Drive Systems could unravel quickly if demand from industrial robots or semiconductor equipment customers softens unexpectedly.
Find out about the key risks to this Harmonic Drive Systems narrative.
Another View on Harmonic Drive Systems' Value
The SWS DCF model paints a different picture for Harmonic Drive Systems. At ¥5,350, the shares trade well above the estimated future cash flow value of ¥2,297.35, which points to an overvalued signal rather than a bargain. Which yardstick do you trust more for your own process?
Look into how the SWS DCF model arrives at its fair value.
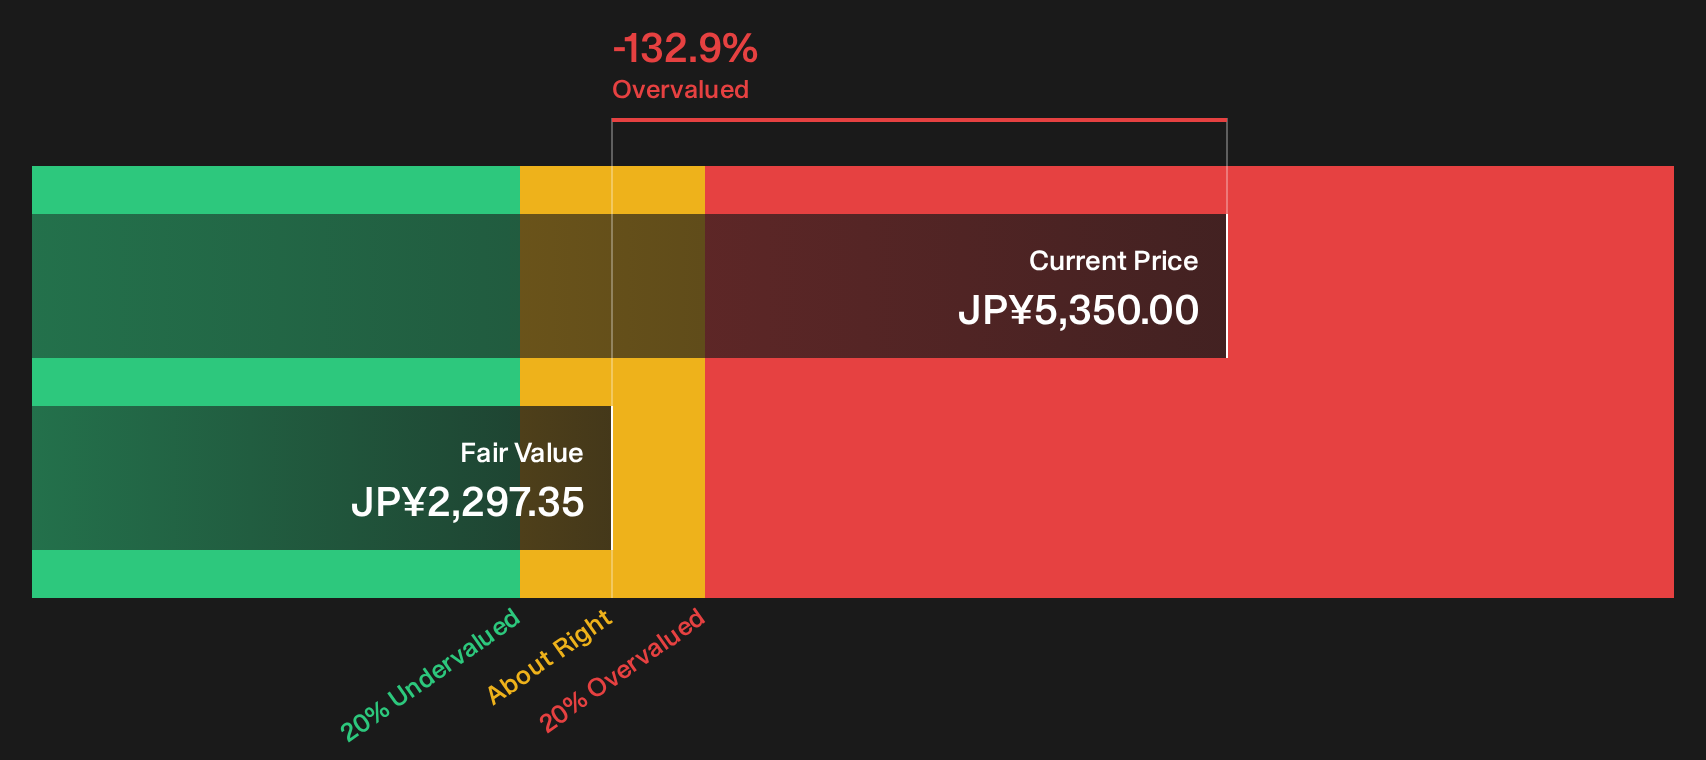
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Harmonic Drive Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Harmonic Drive Systems do not have to leave you on the fence. Move quickly to check the data, weigh the trade offs, and decide where you stand using the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Harmonic Drive Systems?
If Harmonic Drive Systems raises questions about valuation and risk, you can widen your opportunity set with data driven stock ideas tailored to different portfolio goals.
- Target potential mispricing by reviewing companies that screen as quality prospects trading below estimated worth through the 14 high quality undervalued stocks.
- Strengthen income potential by scanning for reliable payers with higher yields using the 29 dividend fortresses.
- Dial down portfolio stress by focusing on financially resilient businesses highlighted in the 22 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com