


Global borrowing costs are climbing just as Covid-era debts in many developing countries come due, and that mix is testing which financial stocks can handle real stress. Some banks and insurers with emerging-market sovereign and restructuring exposure may be positioned to benefit if policymakers follow through on a growth and investment reset. This article walks through 3 such stocks and explains how this news could matter for your portfolio.
The three financial stocks covered below are just a sample set, and the full screen surfaced 29 more banks and insurers with emerging-market sovereign or restructuring angles that carry equally detailed stories. To identify and analyze the highest-conviction plays that fit this theme, head straight into the Global Banks and Insurers with Emerging-Market Sovereign and Restructuring Exposure screener.
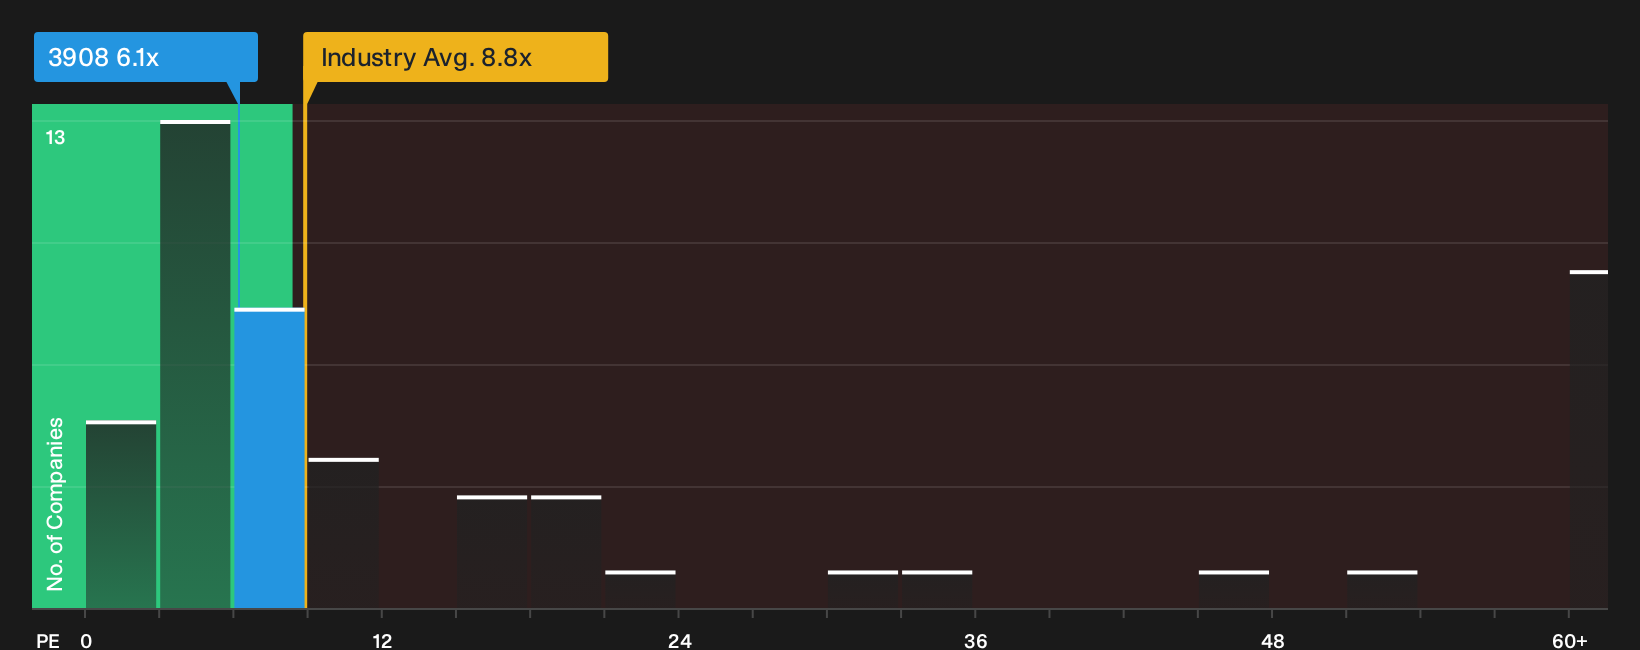
China International Capital (SEHK:3908)
Overview: China International Capital is a Beijing headquartered investment bank and wealth manager offering cross-border financing, trading, advisory, and asset management services.
Operations: The business earns most revenue from wealth management at CN¥12.2b, equities at CN¥9.5b, and investment banking at CN¥6.6b, with smaller contributions from FICC, private equity, asset management, and other activities.
Market Cap: HK$146.8b
China International Capital provides exposure to cross-border deal making linked to emerging-market sovereign debt, restructurings, and multilateral funding programs. The mix of investment banking, FICC, and wealth operations creates leverage to any reset in EM financing terms, while one unresolved funding dependence could influence how that affects future profitability.
That funding reliance is the crux, so go straight to the China International Capital financial health report to see how China International Capital’s balance sheet could amplify any reset in EM deal flow.
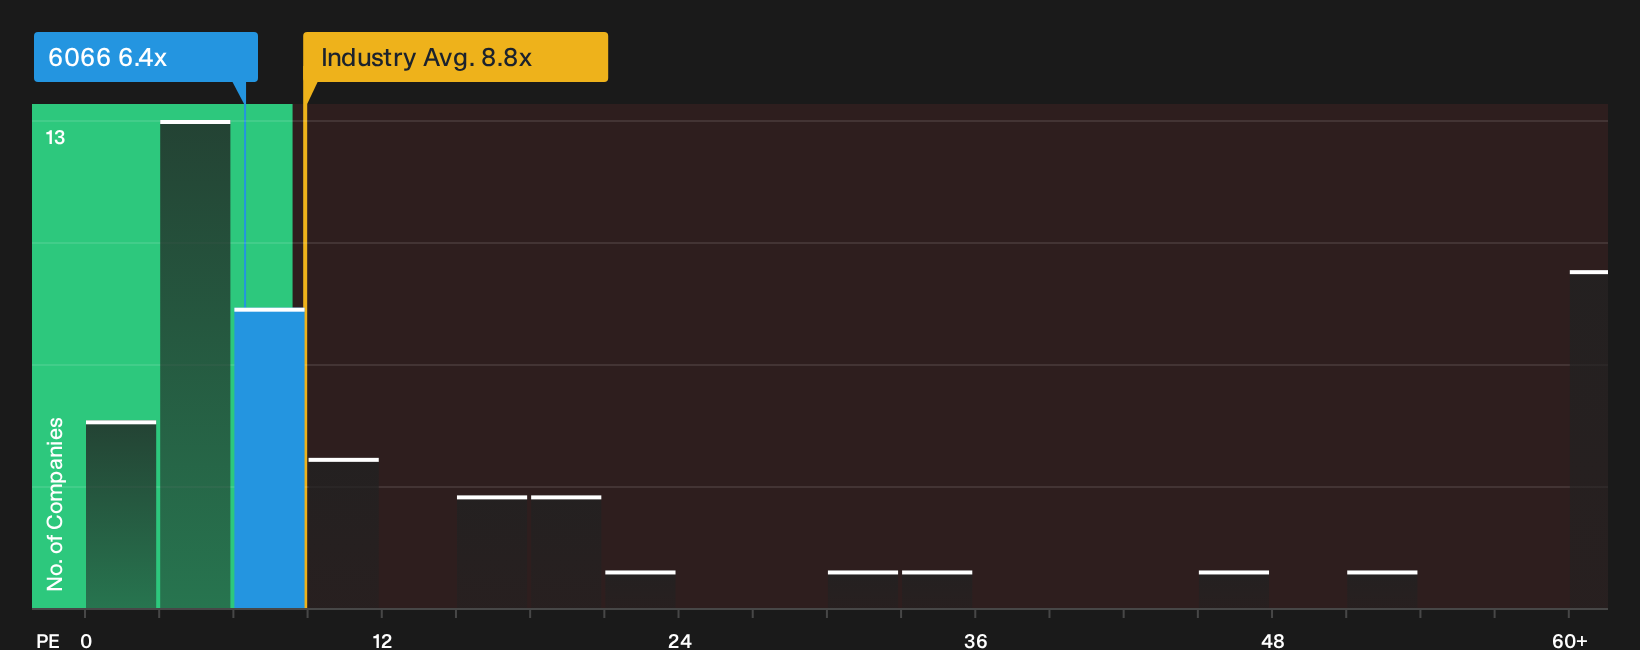
CSC Financial (SEHK:6066)
Overview: CSC Financial is a Beijing based securities firm and investment bank that arranges capital markets deals and cross border advisory work tied to emerging market sovereign and quasi sovereign clients.
Operations: CSC Financial generates most revenue from Transaction and Institutional Customer Service at CN¥13.9b, followed by Wealth Management at CN¥9.1b, Investment Banking at CN¥3.1b, and Asset Management at CN¥1.7b.
Market Cap: HK$188.3b
CSC Financial links directly into the screener theme as a large investment bank with international reach that underwrites debt, arranges equity offerings, and supports trade related financings for emerging market governments and state related borrowers. Investors get targeted exposure to that advisory and underwriting flow. However, what happens when one funding pressure point is tested will matter for how that exposure is rewarded.
That funding hinge is exactly what you can pressure test through the 4 key rewards and 1 important warning sign, and see how CSC Financial’s opportunity compares with its risk.
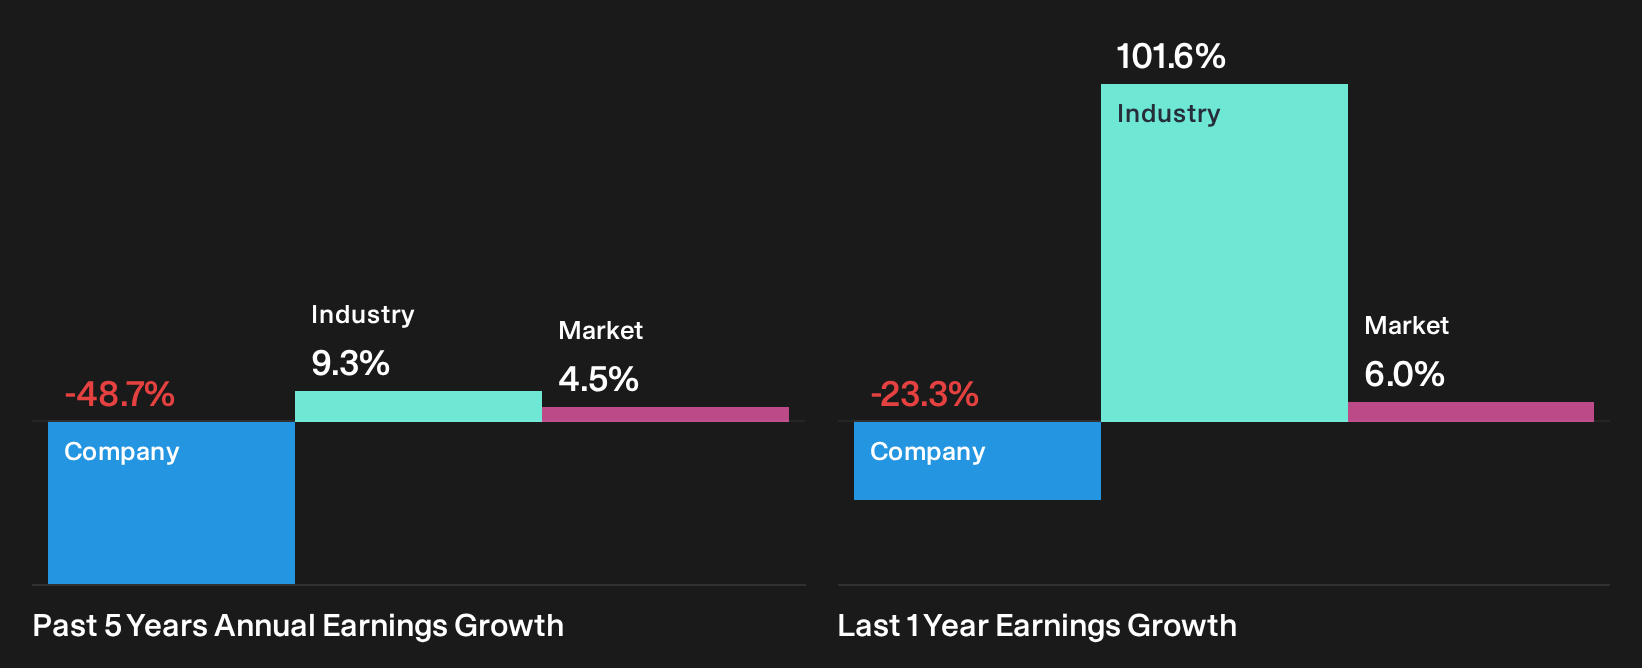
China Cinda Asset Management (SEHK:1359)
Overview: China Cinda Asset Management is a Beijing headquartered distressed asset specialist that acquires, works out, and sells troubled loans and investments across China and overseas.
Operations: China Cinda Asset Management generates CN¥13.7b from Financial Services and CN¥10.8b from Distressed Asset Management, with smaller eliminations of CN¥1.2b.
Market Cap: HK$33.97b
China Cinda Asset Management sits close to the heart of any emerging market debt clean up, handling distressed loans, restructurings, and cross border workouts that can follow IMF or World Bank backed programs. Investors get direct exposure to that repair work; however, what happens when a single funding constraint collides with a heavy restructuring pipeline will matter for how much of that opportunity actually reaches the bottom line.
When that funding constraint bites hardest, the 1 key reward and 3 important warning signs (2 are major!) shows where China Cinda Asset Management’s restructuring upside could decouple from the headline story.
Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, prices can move quickly and clean entry points can disappear before the crowd even looks. Scan these under the radar lists now and consider opportunities early.
- Spot companies quietly building strength before a potential breakout by reviewing a curated list of solid balance sheet and fundamentals (203 results) that keeps quality and resilience front and center.
- Track where income momentum could matter by scanning a focused group of 214 dividend fortresses that aim to keep payouts steady while attention is still light.
- Follow capital flows into AI infrastructure before they attract broader attention by using a targeted pool of 55 AI infrastructure stocks right now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com