


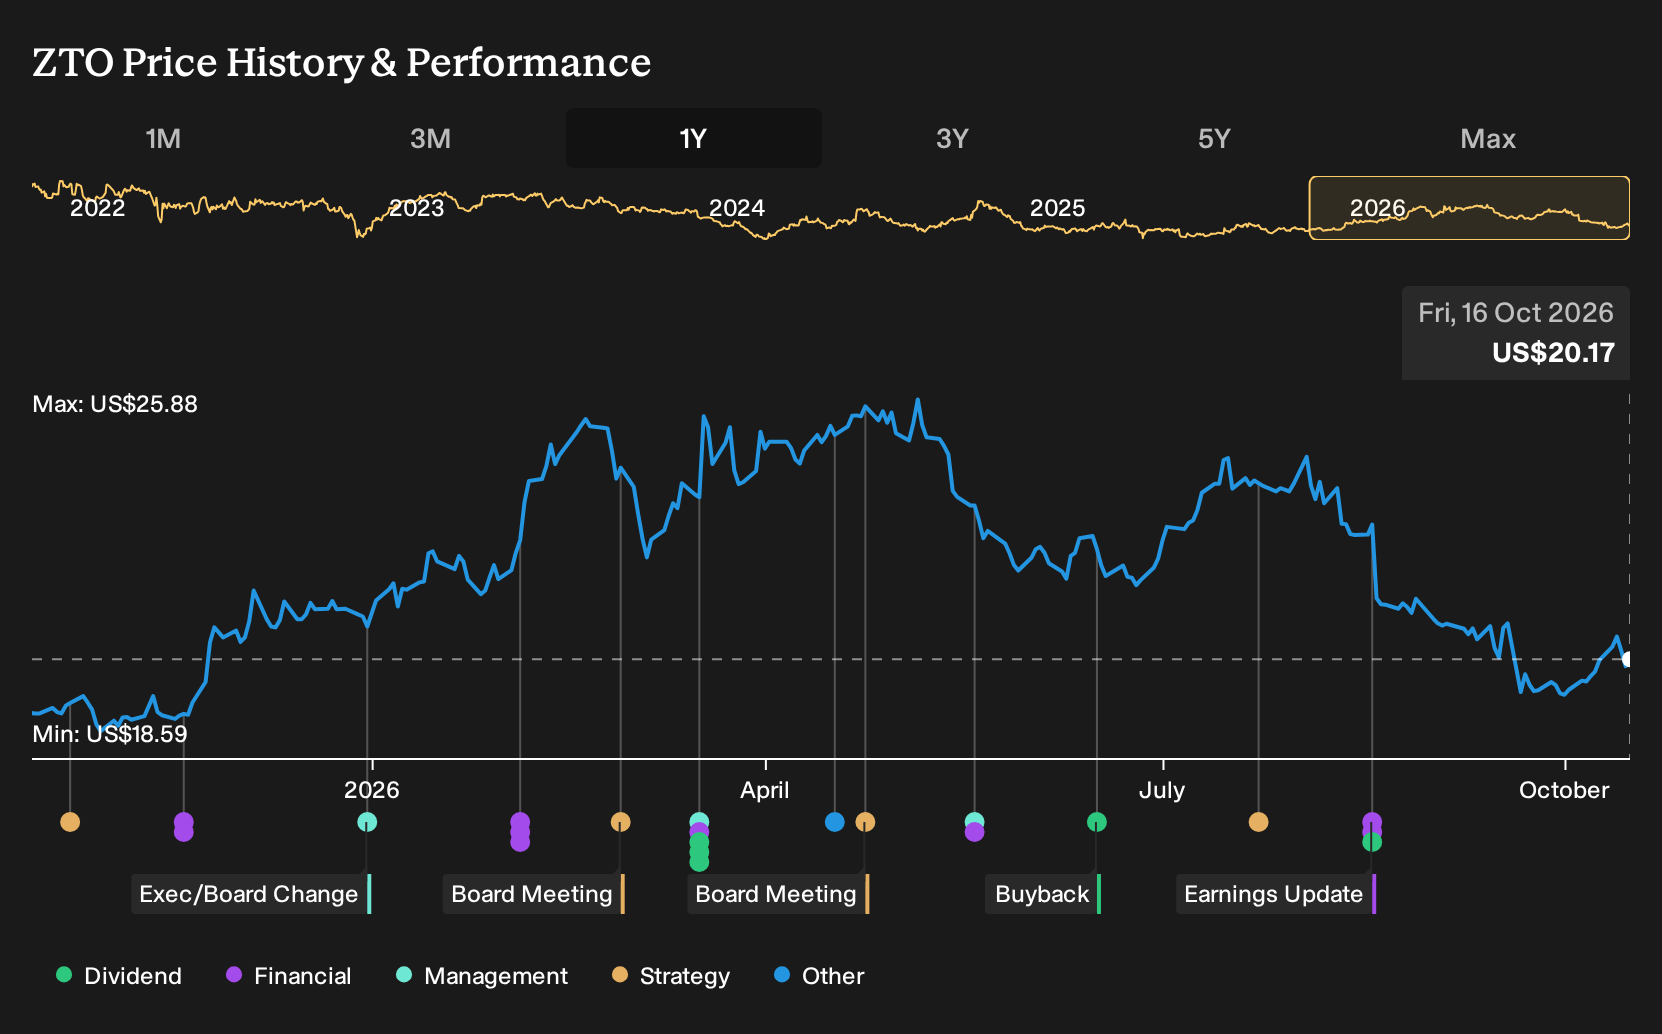
- ZTO Express (Cayman) recently faced a downgrade from Goldman Sachs, after the brokerage adopted a more cautious stance on the company’s outlook.
- The move highlights how sensitive the ZTO Express (Cayman) investment case can be to perceived execution risk around costs, demand durability and earnings resilience.
- This article examines how ZTO Express (Cayman)'s investment narrative is being tested as Goldman Sachs steps back from a previously more constructive stance.
Pressure test your thesis on ZTO Express (Cayman) by comparing it with a curated 32 resilient stocks with low risk scores that may better align with the cautious stance implied by this downgrade.
ZTO Express (Cayman) Investment Narrative Recap
To stay invested in ZTO Express (Cayman), you need to believe the parcel business can keep offsetting softer sector volumes with efficiency gains, a higher value retail mix and more rational pricing. The recent Goldman Sachs downgrade primarily calls execution into question around those levers rather than changing the core story. The near term swing factor is still how volumes and pricing hold up against rising labor and fuel costs.
The biggest risk remains that parcel growth slows again just as cost pressures from courier protections and fuel stay elevated, which could squeeze margins. On that front, the downgrade amplifies existing concerns but does not materially change them. The more important short term test now sits with upcoming earnings, where any sign of weaker profitability would matter more than the rating change itself.
The most immediate operational milestone for ZTO Express (Cayman) is the third quarter 2026 earnings release and conference call scheduled for November 17. That update should give you a clearer read on whether parcel volume trends are tracking within the reduced 2026 guidance range and how the mix toward higher value retail and reverse logistics is evolving. It is the moment when management can address questions now raised more sharply by the downgrade.
Focus on a few things when those numbers arrive: unit cost trends, including fuel and social security related expenses for couriers; any commentary on sector volume conditions after earlier guidance cuts; and evidence that automation and AI routing are still helping offset inflation in the network. Analyst sentiment has turned more cautious, but the operational data and guidance commentary on that call are likely to matter far more to the catalyst path.
ZTO Express (Cayman)'s current analyst narrative points to CN¥70.7b in revenue and CN¥12.9b in earnings by 2029, built on 9.2% yearly revenue growth and an earnings increase of about CN¥2.6b from CN¥10.3b today.
Uncover why ZTO Express (Cayman)'s fair value indicates a 38% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One big swing factor that bullish analysts focus on for ZTO Express (Cayman) is earnings power. Before the Goldman Sachs downgrade, the most optimistic forecasts were built around CN¥77.4b of revenue and CN¥14.4b of earnings by 2029, far above the CN¥12.9b consensus view. That gap shows how sharply opinions can diverge. It is worth watching how those forecasts shift once the downgrade and the upcoming November 17 earnings are fully reflected in the models.
Explore 5 other ZTO Express (Cayman) fair value estimates, including one that suggests as much as 280238% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ZTO Express (Cayman) research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for ZTO Express (Cayman). The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ZTO Express (Cayman)'s overall financial health at a glance.
Looking For More Investment Ideas Beyond ZTO Express (Cayman)?
If the Goldman Sachs downgrade has prompted you to stress test your view on ZTO Express (Cayman), it can help to broaden your watchlist and see how other listed businesses stack up on risk, quality and income potential.
- If capital protection is your priority, start with a basket of companies that screen well on balance sheet strength and downside risk using the 32 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, scan a curated group of financially robust businesses that currently trade below many fair value estimates via the 33 high quality undervalued stocks.
- If income is your focus, shortlist companies that combine higher yields with resilient fundamentals by reviewing the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com