


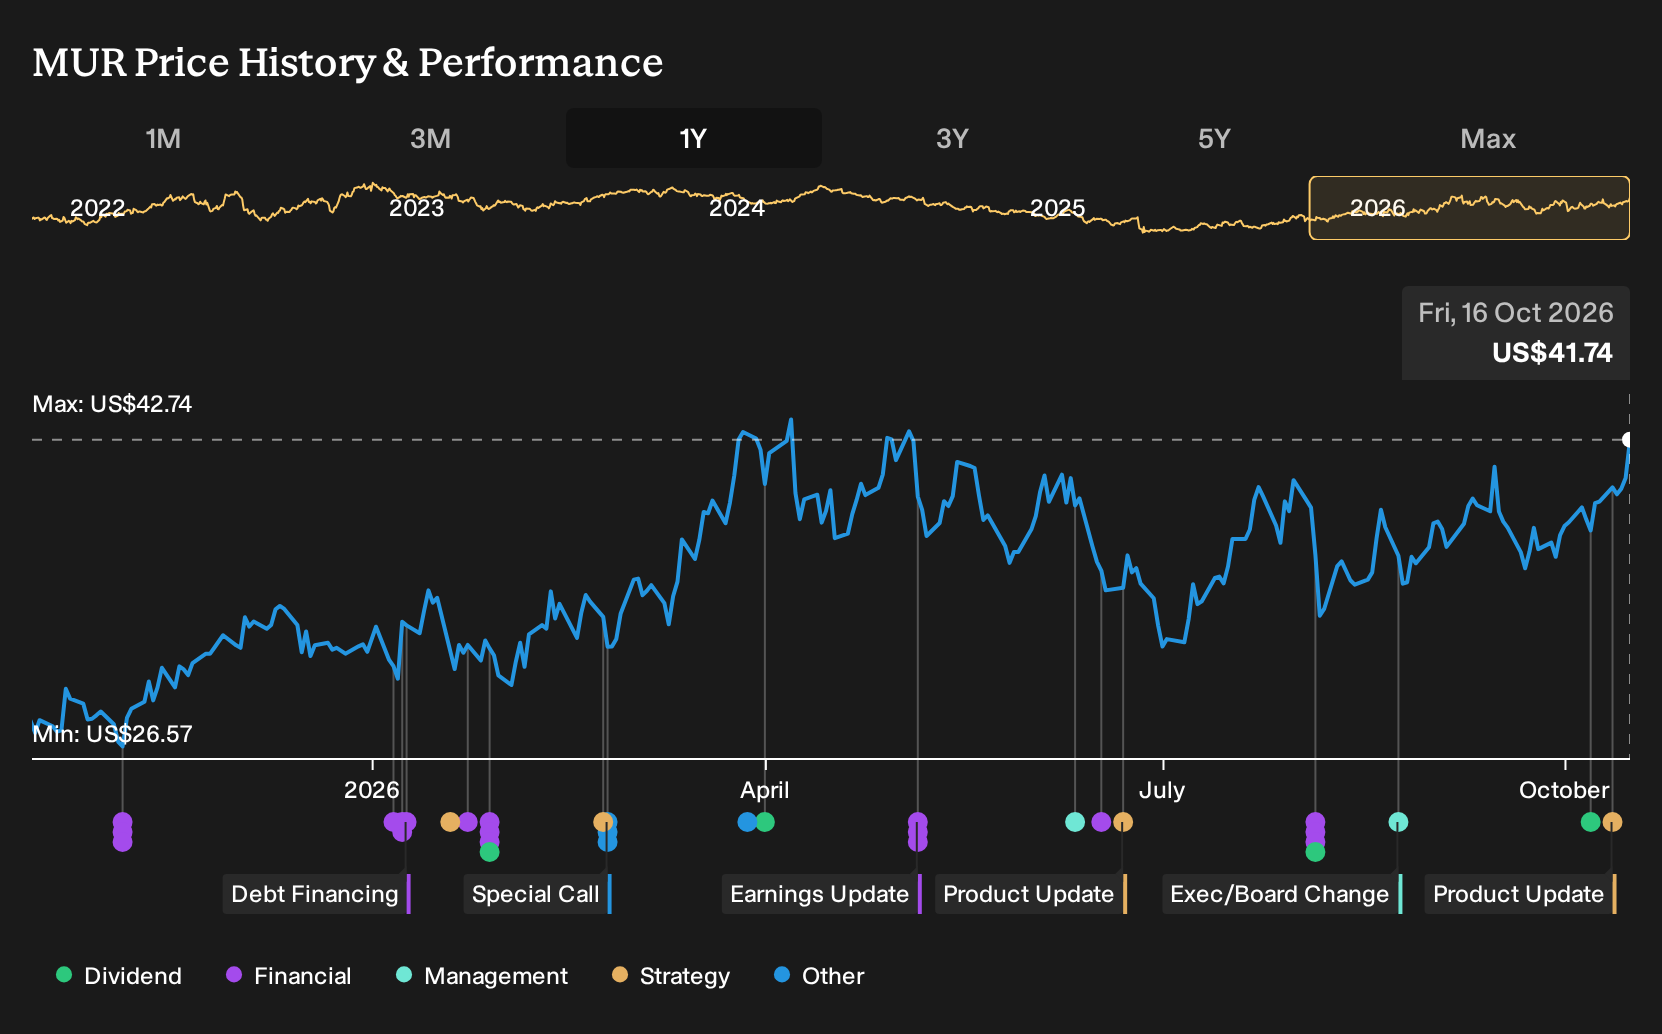
- Murphy Oil reported positive offshore results, including high quality oil at Bubale West in Côte d’Ivoire, an exploration success at Lac Da Trang North in Vietnam, first oil from the Lac Da Vang field, and new production from the Chinook #8 well in the Gulf of America.
- The combination of fresh discoveries, appraisal data and new producing wells signals that Murphy Oil is actively turning recent capital spending into additional resource visibility and near term output, which directly affects how durable its operating plan may look to investors.
- We will now examine how Murphy Oil's new Lac Da Vang production in Vietnam could reshape the existing investment narrative around its offshore growth.
Compare Murphy Oil's offshore momentum with other producers by scanning a hand-picked 17 top copper producer stocks that could be gearing up for their next phase of project-driven growth.
Murphy Oil Investment Narrative Recap
To own Murphy Oil, you need to believe that its heavier 2026 spending program can keep turning into tangible offshore barrels without eroding balance sheet flexibility or dividend capacity. The fresh Bubale West appraisal data, Vietnam discoveries and new wells support the idea that current capital is tied to real projects, not just seismic and concepts.
The key short term swing factor is execution risk on high cost offshore work, particularly Bubale, after well costs moved above earlier expectations. Cost creep, drilling issues or weaker than hoped follow up wells could squeeze returns on this expanded capital plan and limit how much free cash flow Murphy Oil has for debt, buybacks or higher payouts.
The Lac Da Vang first oil milestone is the most relevant update right now. This project has been flagged as a core future volume source and is now officially online, which starts the clock on how reliably it can deliver the planned ramp and cash flow profile that underpins a chunk of Murphy Oil’s offshore story.
Getting Lac Da Vang running is also an important cross check on execution, given the dry hole at Hai Su Vang reminded investors that Vietnam geology carries real downside. If Lac Da Vang stays on plan and the nearby Lac Da Trang North discovery progresses efficiently, it helps offset some of that perceived subsurface and cost risk in the wider portfolio.
What The Offshore Story Implies For Murphy Oil’s Numbers
Murphy Oil's offshore progress around Lac Da Vang, Bubale and the wider portfolio is already baked into the analyst spreadsheets you see quoted in consensus summaries. The same offshore barrels that investors are watching in Vietnam and Côte d’Ivoire underpin the revenue and earnings paths analysts are pencilling in through the back half of this decade.
Analysts are currently working off a set of assumptions that stitch these project updates into a financial arc. Revenue is modeled to grow by 2.6% a year over the next three years, while profit margins are expected to move from 9.9% today to 21.1% by 2029. Put simply, forecasts assume Murphy Oil squeezes more profit out of each dollar of future sales as projects like Lac Da Vang mature and higher margin barrels take a larger share of the mix.
Consensus estimates point to earnings of US$682.0 million by 2029, compared with US$295.2 million today. That implies an earnings uplift of about US$386.8 million over the next few years, even before factoring in how much dispersion there is between the bullish and bearish ends of the analyst range. Forecasts sit between roughly US$422.8 million at the low end and about US$1.2b at the top. This shows how differently analysts are interpreting the same offshore data points and project outcomes.
Valuation work in those reports ties directly back to these offshore expectations. To land on a consensus view that Murphy Oil could be fairly priced at current levels, analysts assume that by 2029 revenue reaches roughly US$3.2b, earnings land at US$682.0 million and the stock trades on a P/E of 10.6x using a discount rate of around 7.2%. The implied P/E multiple is below both Murphy Oil’s current level of 18.1x and the quoted 12.3x for the broader US oil and gas industry. As a result, the story only really hangs together if investors accept a step up in profitability alongside a step down in the multiple.
Murphy Oil's narrative projects US$3.2b revenue and US$682.0 million earnings by 2029. This rests on 2.6% yearly revenue growth and an earnings increase of about US$386.8 million from US$295.2 million today.
Uncover why Murphy Oil's fair value indicates a 4% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternative view leans hard on cost risk. In that storyline, Murphy Oil’s heavier offshore budget could struggle to earn its keep, which is why the most cautious analysts were only pencilling in about US$3.2b of 2029 revenue and roughly US$418.1 million of earnings before this Bubale and Lac Da Vang news. That is a much more pessimistic arc than the baseline. It shows how far opinions can stretch, and why you may want to compare several forecast paths before deciding how this latest update might shift the range.
Explore 2 other Murphy Oil fair value estimates, including one that suggests it could be worth just $40.21.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Murphy Oil research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Murphy Oil. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Murphy Oil's overall financial health at a glance.
Looking for more Murphy Oil sized ideas?
If the offshore story around Murphy Oil has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you line up other opportunities with very different risk and income profiles.
- If you want a shot at early stage growth stories with tighter balance sheets, scan through 14 elite penny stocks with strong financials that already clear a financial quality bar.
- For investors who care most about buying strong businesses at what could be reasonable prices, filter the market by focusing on 33 high quality undervalued stocks that pair fundamentals with potential mispricing.
- If a steadier ride appeals more than chasing every new offshore project, concentrate on income ideas drawn from 8 dividend fortresses that prioritize resilience and yield.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com