


- Planet Labs PBC recently launched 20 satellites and advanced projects with Google AI and the European Space Agency, including a Sinergise-led disaster response pilot in Slovenia.
- These projects highlight a push toward solution driven geospatial services, which could influence how consistently Planet Labs converts satellite capacity into contracted revenue.
- This article examines how Planet Labs’ investment narrative is affected by expanded satellite capacity tied to Google AI and ESA projects.
Compare Planet Labs PBC's AI linked momentum with a hand picked set of smaller AI infrastructure plays by scanning the 55 AI infrastructure stocks that are now shaping how data gets processed and sold.
Planet Labs PBC Investment Narrative Recap
To own Planet Labs PBC, you need to believe the firm can turn its growing satellite and AI footprint into higher value contracts and eventually better cash generation. The big near term swing factor is how quickly those 20 new satellites and AI linked projects translate into signed solution deals, not just more raw imagery.
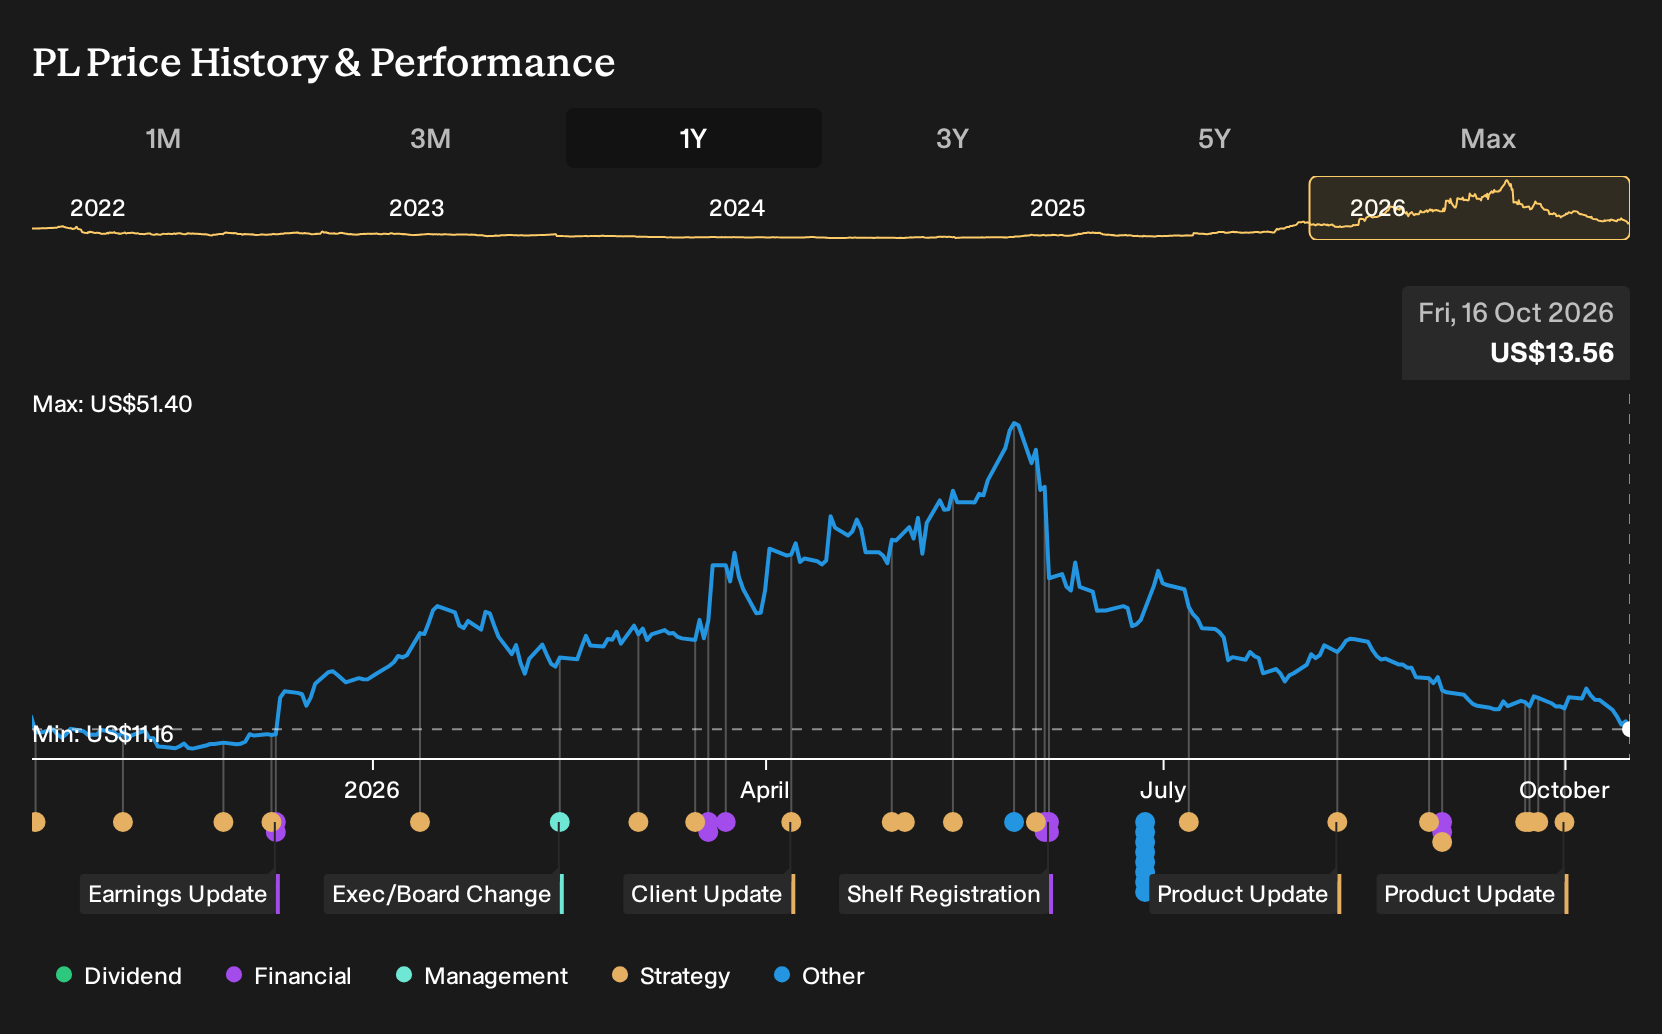
The main risk right now sits on the cost and capacity side. Heavy investment in new fleets and experimental AI efforts could weigh on cash flow if customer demand or large account wins do not keep pace. That matters even more with the stock already trading at a rich P/S multiple versus peers.
The most relevant development here is the Sinergise led European Space Agency disaster response pilot in Slovenia. It puts Planet Labs’ solution focused strategy to work in a real, time critical use case that leans heavily on automated analytics rather than just providing pixels from orbit.
If the 12 month ESA project proves the platform can deliver reliable, actionable insights for public sector clients, it strengthens the case for larger solution contracts elsewhere. The flip side is execution risk. Any delays, limited scope expansion, or muted follow on demand would underline how experimental some of Planet Labs PBC's AI and automation revenue opportunities still are.
Analysts frame Planet Labs PBC's setup around projected revenues of $786.3 million and earnings of $53.2 million by 2029, based on an assumed yearly revenue growth rate of 27.6%. This would represent a swing in earnings of roughly $413 million from a loss of $359.9 million today.
Uncover why Planet Labs PBC's fair value indicates a 135% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate, more optimistic angle focuses on Planet Labs PBC’s reported Rule of 40 scores above 70 and a cash balance near US$865m. Bullish analysts were already modeling roughly US$937.6m revenue and US$63.4m earnings by 2029 before this AI and ESA news; as a result, you may see those upbeat assumptions shift again as expectations reset.
Explore 8 other Planet Labs PBC fair value estimates, including one that suggests potential upside of as much as 269% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Planet Labs PBC research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Planet Labs PBC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Planet Labs PBC's overall financial health at a glance.
Looking for more investment ideas beyond Planet Labs PBC?
Once you have formed a view on Planet Labs PBC, it helps to stack that thesis against other opportunities so your portfolio is not anchored to a single story.
- For investors who want to stay focused on quality at a discount, scan the 33 high quality undervalued stocks to find companies that combine stronger fundamentals with pricing that still looks restrained.
- If capital protection sits near the top of your priorities, filter the market using a 32 resilient stocks with low risk scores to screen for businesses with fewer red flags on core risk checks.
- When balance sheet strength is non negotiable, narrow your watchlist through a list of solid balance sheet and fundamentals (25 results) that concentrates on companies with sturdier financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com