


Mirum Pharmaceuticals has delivered very large gains over the past five years. However, the recent pullback raises a simple question for you as a shareholder or prospective buyer: Is the current US$80.14 share price still supported by what the business is generating in sales today and what the market expects those sales to become?
- Over 5 years the stock has returned about 7x, which puts a lot of weight on whether its share price still lines up with the revenue base behind it.
- Fresh Phase 3 data for LIVMARLI in ultra rare liver diseases may support expectations for higher future product sales, which can influence how much investors are prepared to pay per dollar of current revenue.
- Your read on Mirum Pharmaceuticals is one view; the desks covering it have another. See what analysts think Mirum Pharmaceuticals's shares could be worth.
The issue now is whether Mirum Pharmaceuticals' current valuation is justified by its sales once you compare the share price to the revenue it generates.
If you want more context around a move like Mirum Pharmaceuticals' 426.9% five year return and the recent pullback, compare it against other 33 high quality undervalued stocks.
Is Mirum Pharmaceuticals Still Cheap on Sales?
P/S is usually the cleaner yardstick for a biotech like Mirum Pharmaceuticals because earnings can swing around early in a product cycle while revenue tells you what the market is already paying for its drugs.
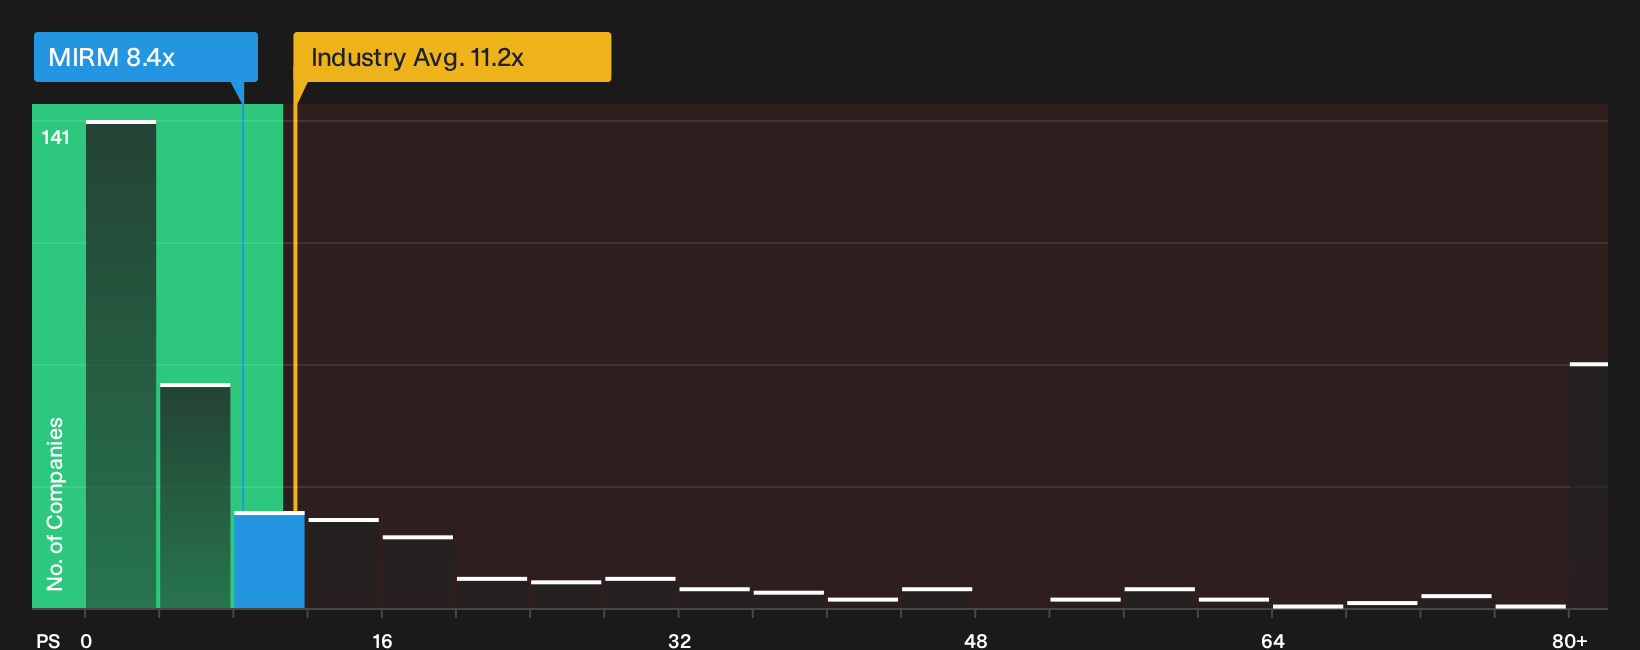
On this lens, Mirum Pharmaceuticals trades on a P/S of 8.4x, compared with about 11.2x for the broader biotech industry and roughly 12.4x for close peers. The Fair Ratio model, which adjusts for the company’s growth profile, margins, size and risk, points to a higher multiple than where the shares change hands today, so the stock screens as undervalued on this measure. Because the recent positive Phase 3 LIVMARLI result is already a concrete milestone, the current discount to both sector and peer averages suggests the market is still pricing Mirum with some caution despite that progress. Explore the numbers behind Mirum Pharmaceuticals's P/S valuation.
The Mirum Pharmaceuticals Narrative: What Would Justify Today's Price?
Mirum Pharmaceuticals' valuation puzzle only really makes sense once you spell out the future paths that could sit behind today’s price. This is exactly what Simply Wall St Narratives aim to do on the Community page by turning those implied assumptions on growth, margins and earnings into clear scenarios where the stock could be worth meaningfully more or less. Each narrative treats fair value as a thesis about the business that you can revisit over time rather than a one off snapshot.
One of the top community narratives on Mirum Pharmaceuticals: 48% undervalued
"Broader patient identification, international expansion, and supportive reimbursement environments are driving sustained revenue growth and improving margins for Mirum's portfolio…"
Discover why this Narrative puts Mirum Pharmaceuticals at 48% undervalued.
One more Mirum Pharmaceuticals check before you move on
Everything so far has focused on what Mirum Pharmaceuticals looks like right now. Analyst models sketch out where they expect the business to be in a few years, which gives you a separate yardstick to compare with today’s pricing. Explore where analysts expect Mirum Pharmaceuticals to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com